
What Kennametal Stock's NASCAR Tooling Deal Means For Shareholders
- Kennametal announced that NASCAR has named it the Official Tooling Supplier, providing advanced metal cutting solutions and on-site application expertise for the motorsport's manufacturing operations.
- This agreement elevates a long-running collaboration at NASCAR’s Research & Development Center into a formal supplier role, giving Kennametal deeper access to demanding machining use cases that can inform product development and process know-how.
- We will now examine how Kennametal's new role as NASCAR’s Official Tooling Supplier could shape the broader investment narrative for the business.
Scan how Kennametal’s NASCAR tooling deal compares with other precision engineering plays by reviewing our hand picked 38 robotics and automation stocks that are helping manufacturers push performance limits.
Kennametal Investment Narrative Recap
To own Kennametal, you need to believe that its metal cutting and wear solutions can hold or grow share even if key end markets stay mixed and pricing pressure remains intense. The NASCAR tooling deal may help the story at the margin by showcasing high performance applications, but it does not change the core dependency on Transportation, Oil & Gas, and Earthworks volumes.
In the near term, the key swing factor is execution on rightsizing and cost savings while protecting product quality and customer service. The biggest risk remains structurally weak demand that keeps revenue near current levels, which would make it harder to translate footprint rationalization and digital initiatives into sustainably better margins.
The Morgan Stanley Laguna Conference appearance on 15 September 2026 looks particularly relevant because it gives Kennametal a platform to explain how relationships such as the NASCAR partnership fit into its broader tooling and industrial strategy. Investors will likely focus on how management frames demand trends across its Metal Cutting and Infrastructure segments.
Conference remarks can also clarify how Kennametal balances growth projects with its restructuring program and dividend commitments, especially with earnings forecast to decline even as revenue is expected to grow. Any concrete detail on progress toward the planned US$125 million in run rate savings by fiscal 2028, or on capital allocation priorities, will feed directly into how you think about risk, potential catalysts, and the durability of the current P/E discount.
Kennametal Consensus Setup Behind The NASCAR Tooling Story
Kennametal's narrative projects US$3.6b revenue and US$273.0 million earnings by 2029. This assumes 15.0% yearly revenue growth and a US$69.4 million earnings decline from US$342.4 million today.
Uncover why Kennametal's fair value indicates a 12% potential upside to its current price that could narrow quickly.
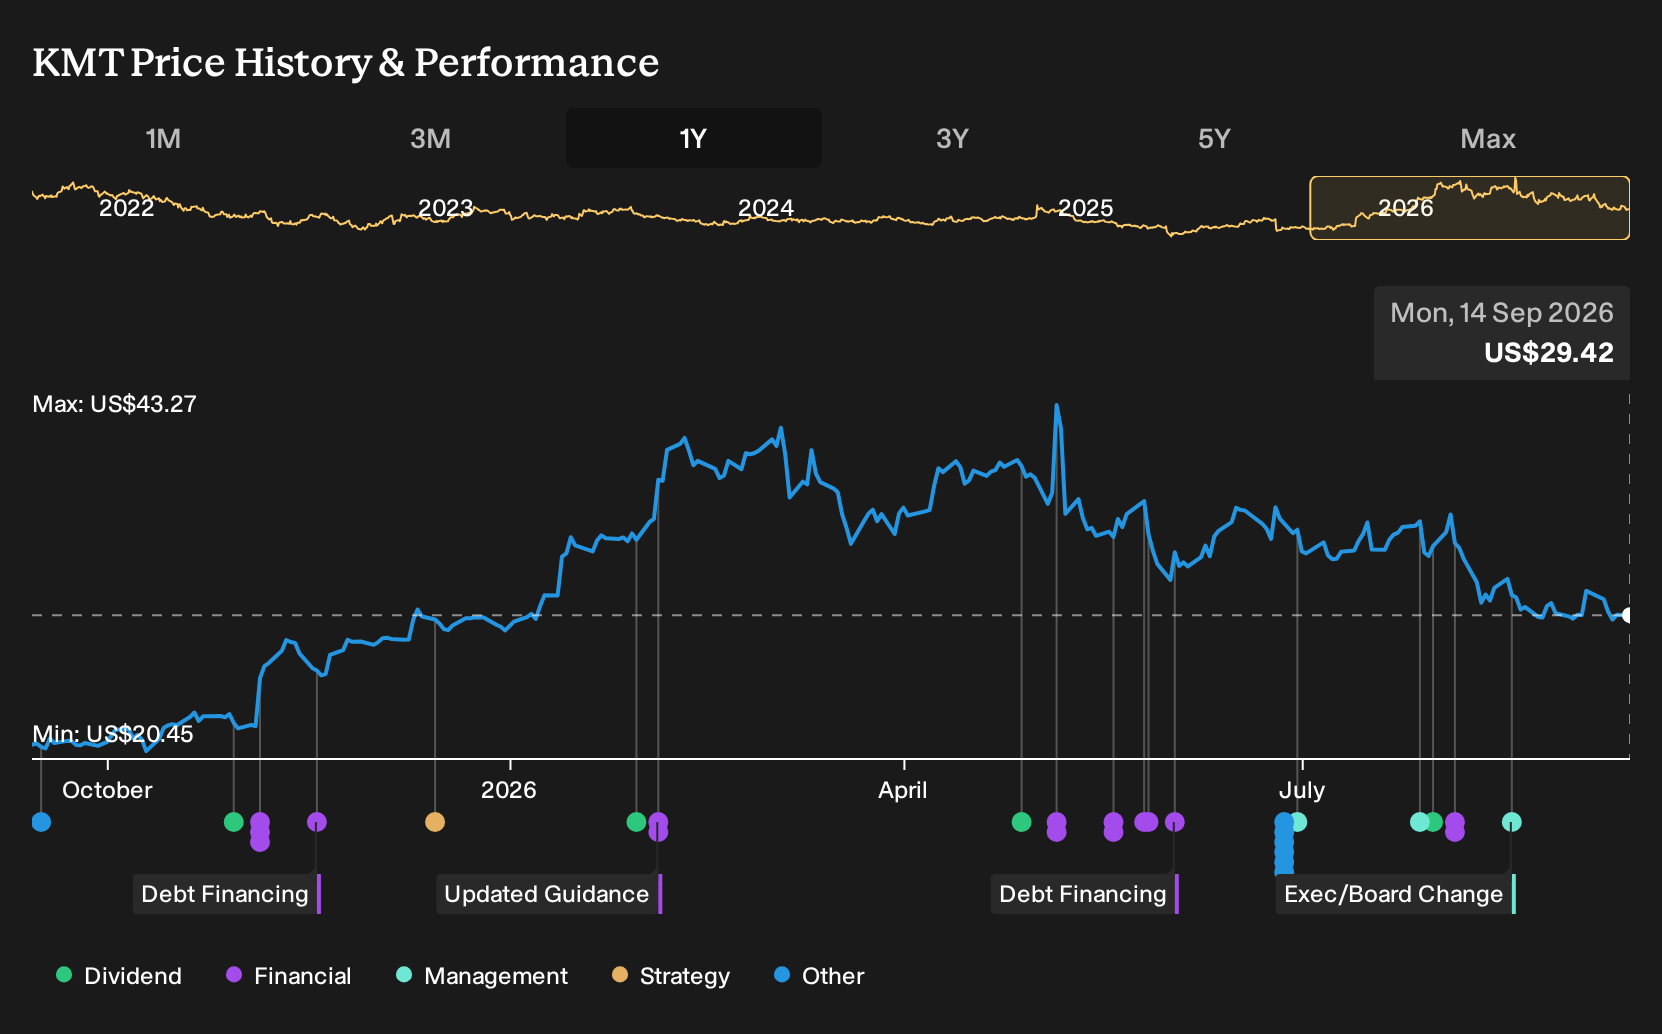
Exploring Other Perspectives
Some of the most optimistic analysts already framed Kennametal around potential share gains in Earthworks and mining, with forecasts for revenue to reach about US$3.4b and earnings of US$221.2 million by 2029. You might see the NASCAR tooling role as fresh evidence for that view, or you may question it entirely. Either way, opinions differ widely. Explore multiple angles before deciding how this new partnership could reshape your own Kennametal story.
Explore 2 other Kennametal fair value estimates, including one that suggests as much as 423% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kennametal research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kennametal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kennametal's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kennametal?
Once you have a view on Kennametal, it can help to compare it with other opportunities that share some of the same qualities, whether you care more about value, resilience, or balance sheet strength. The Simply Wall St Screener lets you do that in a structured way, starting with focused shortlists built around what matters most to you.
- If you want potential value combined with quality fundamentals, start with this hand picked set of 35 high quality undervalued stocks that already screen for strong cash flows and solid financial footing.
- For readers who care most about durability and capital preservation, narrow your search to a 11 resilient stocks with low risk scores that already filters for more resilient business profiles.
- If balance sheet strength sits at the top of your checklist, concentrate on companies from a list of solid balance sheet and fundamentals (23 results) so you are comparing Kennametal with peers that also emphasize financial stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com