
How Earnings Miss At Globe Life Has Changed Its Investment Story
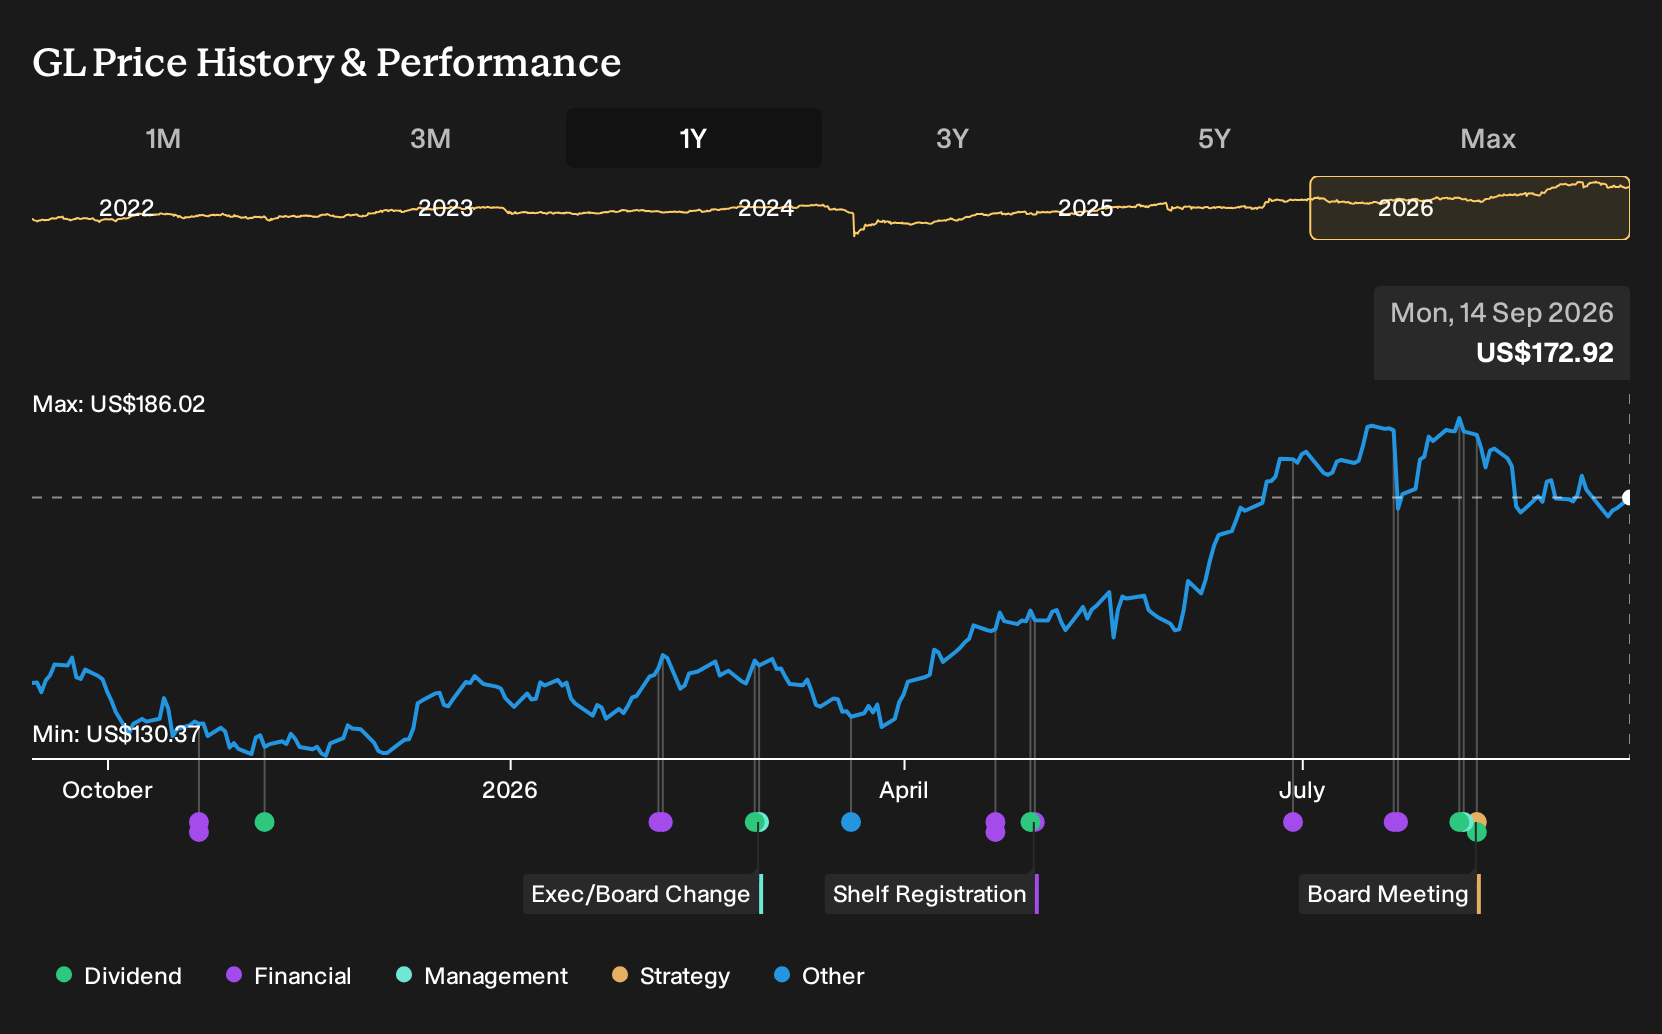
- Globe Life recently reported Q2 revenue of US$1.59b, which matched analyst expectations, while book value per share and EPS came in below estimates, contributing to a difficult quarter for both the business and the wider life insurance industry.
- The earnings miss lands just as Globe Life invests in AI, digital tools, and agent productivity, placing greater emphasis on execution in cost control and the payoff from technology investments.
- The Globe Life investment narrative will now be evaluated in the context of this recent EPS shortfall and what it may indicate about key profitability drivers.
Scan how Globe Life's Q2 stumble compares with peers facing similar pressures by reviewing our hand-picked 11 resilient stocks with low risk scores, which focuses on resilience when earnings disappoint.
Globe Life Investment Narrative Recap
For Globe Life, the core belief is that a focused life and supplemental health insurer serving working and middle income families can keep generating steady policy demand while squeezing more efficiency from both agents and digital channels. The recent Q2 EPS miss and share price reaction put near term pressure on that story, but revenue of US$1.59b and ongoing demand signals show the franchise is still functioning.
The key short term catalyst is execution on technology, including AI, and productivity tools that are meant to lift conversion in Direct to Consumer while supporting exclusive agents. The biggest risk is that these investments take longer to translate into underwriting margins and free cash flow, especially with existing debt levels and ongoing regulatory overhangs already in the background.
The most relevant recent development is management’s push into AI and broader technology upgrades. Globe Life is using these tools to streamline underwriting, sharpen customer targeting, and support agent workflows. For you as a shareholder, the near term question is whether these projects help offset the earnings pressure that showed up in the latest quarter.
That same tech agenda feeds directly into the main catalysts analysts have focused on. Better digital underwriting and higher Direct to Consumer conversion could support policy sales and marketing efficiency, while an eventual Bermuda reinsurance structure is intended to strengthen free cash flow. Against that, execution risk on both technology and capital initiatives, plus sensitivity to interest rates and credit quality, keeps the operational bar high.
Globe Life's current analyst narrative points to revenues of US$7.4b and earnings of US$1.3b by 2029, based on an assumed yearly top line growth rate of 6.2%. That earnings figure would represent a US$0.1b increase from US$1.2b in earnings today.
Discover how Globe Life's fair value indicates a 12% potential upside to its current price that could close sooner than expected.
Exploring Other Perspectives
For Globe Life, the biggest swing factor in the more optimistic narrative is expansion into underserved markets. The most bullish analysts were pencilling in revenue of about US$7.6b and earnings near US$1.4b by 2029, slightly above the consensus. After the recent EPS miss and share price reaction, you may see those views, and your own, shift.
Explore 3 other Globe Life fair value estimates, including one that suggests as much as 104% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Globe Life research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Globe Life. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Globe Life's overall financial health at a glance.
Looking for more Globe Life sized investment ideas?
Once you have formed a view on Globe Life, it can help to widen the lens and compare it with other potential opportunities that fit different portfolio goals.
- For investors who want income and resilience, consider stocks on our 6 dividend fortresses that focus on higher yields with robust underlying businesses.
- If capital preservation and financial strength sit at the top of your checklist, review the list of solid balance sheet and fundamentals (23 results) as a starting point for sturdier candidates.
- When you are hunting for future leaders before they are widely followed, scan the 15 high quality undiscovered gems to see companies with quality metrics that may still be off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com