
Kadokawa (TSE:9468) Expands On Manta As Its Valuation Starts To Look Fully Valued
Kadokawa (TSE:9468) is back in focus after digital comics platform Manta signed worldwide distribution deals to carry more than 300 manga titles from Kadokawa and other major Japanese publishers.
Recent price action already reflects some of this renewed attention. Kadokawa’s share price is now at ¥3,682, with a 90-day share price return of 18.47% and a year-to-date share price return of 17.79%. The 5-year total shareholder return of 37.40% points to a steadier long-run payoff profile.
Use Kadokawa’s global manga push as a starting point to scan for other media and content publishers with fresh catalysts in our curated 74 high quality undiscovered gems.
Kadokawa now trades above the consensus target and sits well above some intrinsic value estimates after a strong run. Where does fair value genuinely cluster within that spread, and how wide is the margin for error?
Preferred Price-to-Sales of 1.9x for Kadokawa: Is it justified?
Kadokawa now carries a P/S ratio of 1.9x, which places the stock on a richer tag than both its direct peers at 1.3x and the broader JP Media sector at 0.8x.
The P/S ratio compares a company’s market value with its revenue. For a group like Kadokawa that leans heavily on intellectual property across publishing, anime, games, and web services, investors often watch this measure to gauge how much they are paying for each unit of top-line output when earnings are currently negative.
Here, the market is assigning a premium to Kadokawa’s sales base compared with both its peer group and the domestic media industry. That points to investors pricing in stronger business quality or future earnings normalisation, even though the enterprise is unprofitable today and reports a loss of ¥6,120 million. At the same time, the estimated fair P/S ratio of 2.2x sits above the present 1.9x level. This suggests there is room for the valuation multiple to move closer to that fair-value reference if the investment case holds.
The gap to the sector is wide. Kadokawa’s 1.9x P/S is more than double the JP Media industry’s 0.8x and also above the 1.3x peer average. This signals investors are willing to pay a clearly higher price per yen of revenue than for many comparable media stocks.
Explore the SWS fair ratio for Kadokawa.
Result: Price-to-sales of 1.9x (OVERVALUED)
Still, Kadokawa’s premium P/S and current net loss of ¥6,120 million leave little cushion if manga partnerships underperform or if content spending fails to lift profitability.
Find out about the key risks to this Kadokawa narrative.
Another View on Kadokawa’s Value
The SWS DCF model paints a different picture for Kadokawa. At ¥3,682, the stock trades above an estimated future cash flow value of ¥2,584.15, which frames it as overvalued on this lens. If cash generation lags optimistic expectations, how much patience will investors really have?
Look into how the SWS DCF model arrives at its fair value.
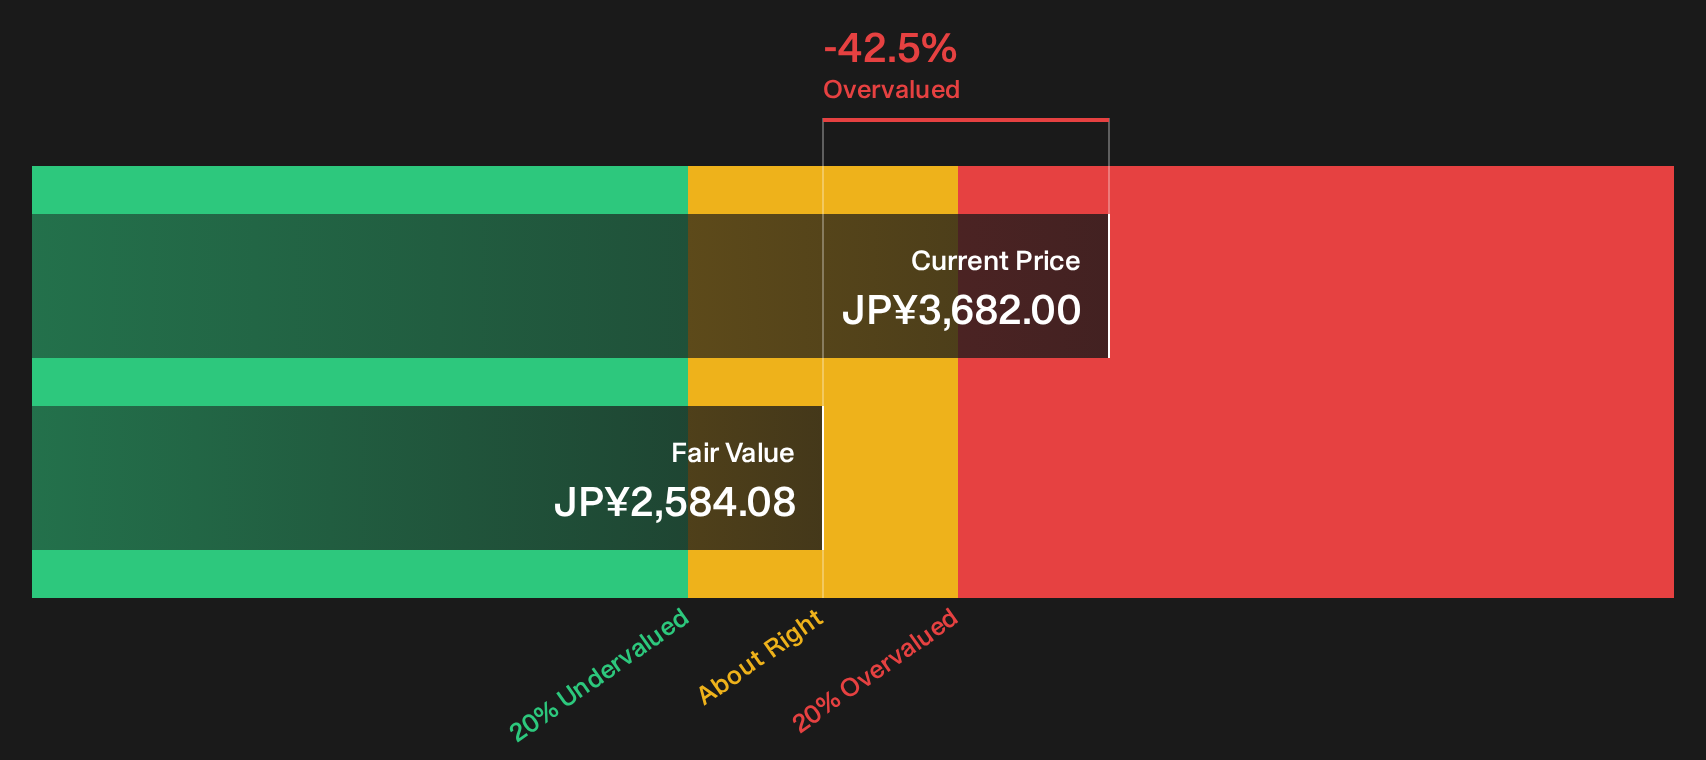
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kadokawa for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this read on Kadokawa feels mixed, treat that as a prompt to move fast and stress test the bullish angles yourself with the 1 key reward
Looking for more Kadokawa sized opportunities?
Do not park all your attention on Kadokawa. Use this momentum to broaden the watchlist and pressure test fresh ideas before the crowd catches on.
- Hunt for underappreciated quality by scanning companies that appear mispriced on fundamentals through the 17 high quality undervalued stocks.
- Build a sturdier core by focusing on companies with healthier finances using the list of solid balance sheet and fundamentals (19 results).
- Target fresh potential by searching for less followed businesses with strong foundations through the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com