
Uniphar (ISE:UPR) Could Be 25% Below Fair Value As Profit And Dividend Rise
What the latest results and dividend move signal for Uniphar shareholders
Uniphar (ISE:UPR) just paired higher half year sales and net income with a 4.2% uplift in its interim dividend, a combination that can sharpen the focus on income and growth potential.
That dividend lift comes at a moment when Uniphar’s share price has been under some pressure in the short term, with the stock falling 6.8% over the past 30 days and 15.6% over 90 days. This is in contrast to the year-to-date share price return of 14.9% and three year total shareholder return of 62.5%, which point to momentum that has built over a longer stretch. The latest half year results and commentary around ongoing M&A plans, dividend growth and potential share buybacks help explain the recent 1 day share price gain of 2.6%, as investors weigh near term volatility against a longer record of value creation on a total return basis.
Contrast Uniphar’s mix of dividend growth, earnings momentum and M&A plans with a curated 618 high quality undiscovered gems showing similar fundamentals but far less attention from the market.
Uniphar now pairs a softer recent share price with fresher earnings, a higher interim dividend and talk of buybacks. Does that tip the balance toward buying today or waiting for a cheaper entry before valuation stacks up for you?
Most Popular Narrative: 25% Undervalued
The most followed valuation narrative for Uniphar pegs fair value at about €5.34 per share, compared with the latest close at €4.00. This frames today’s price as a discount that depends heavily on how the acquisition pipeline and operating projects play out.
Disciplined capital allocation, with ROCE reported above the 12 to 15 percent hurdle and leverage maintained below 2.5 times, combined with a growing M&A pipeline in pharma services, may allow accretive bolt ons and organic investments to support revenue growth and progress toward the 200 million euro EBITDA target.
See why 2 investors see Uniphar as 25% undervalued.
Result: Fair Value of €5.34 (UNDERVALUED)
Still, the Uniphar story can change quickly if the new distribution center and S/4HANA rollout run into cost overruns, or if planned acquisitions underdeliver on returns.
Find out about the key risks to this Uniphar narrative.
Another View on Uniphar’s Valuation
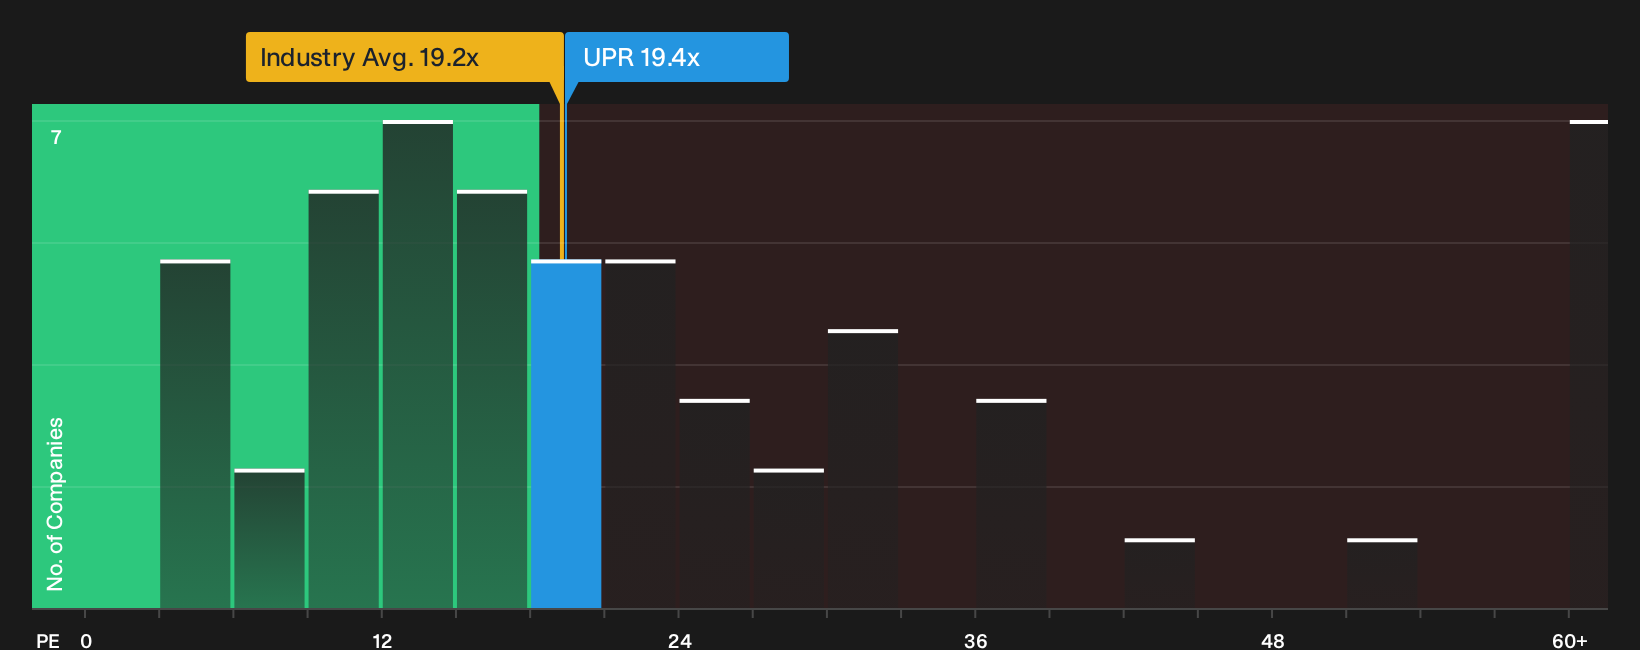
The first narrative leans on analyst targets and earnings forecasts to argue Uniphar looks undervalued around €4.00. A simpler lens, the current P/E of 19.4x, tells a quieter story. It roughly matches the European Healthcare average at 19.2x and even looks cheaper than peers at 22.3x.
That mix of apparent value versus peers but only slight difference versus the wider industry leaves a question: Is the real opportunity already baked into today’s P/E, or are analysts right that the upside case still has room to run?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and execution risks can be hard to process in one sitting, so move quickly, review the full risk and reward breakdown, and judge Uniphar on your own terms with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Uniphar?
If Uniphar has your attention, you may want to explore a few other angles that could sharpen your overall portfolio mix.
- Target resilient income first and review companies that show up as 161 dividend fortresses for potentially steadier cash flows even when share prices move around.
- Cut portfolio risk at the source and use the 103 resilient stocks with low risk scores to focus on businesses with fewer red flags and stronger downside protection.
- Spot potential future leaders early by scanning the 20 elite penny stocks with strong financials where smaller outfits might offer differentiated growth stories before they reach wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com