
Asian Growth Companies With High Insider Ownership To Watch
As global markets navigate the complexities of geopolitical tensions and fluctuating oil prices, Asian equities have shown resilience, with growth companies continuing to capture investor interest. In this environment, stocks with high insider ownership can be particularly appealing as they often indicate strong confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Zhejiang Taotao Vehicles (SZSE:301345) | 27.9% | 31.7% |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| SEERS (KOSDAQ:A458870) | 33.8% | 35.7% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 28.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's review some notable picks from our screened stocks.
Zhejiang Leapmotor Technology (SEHK:9863)
Simply Wall St Growth Rating: ★★★★★★
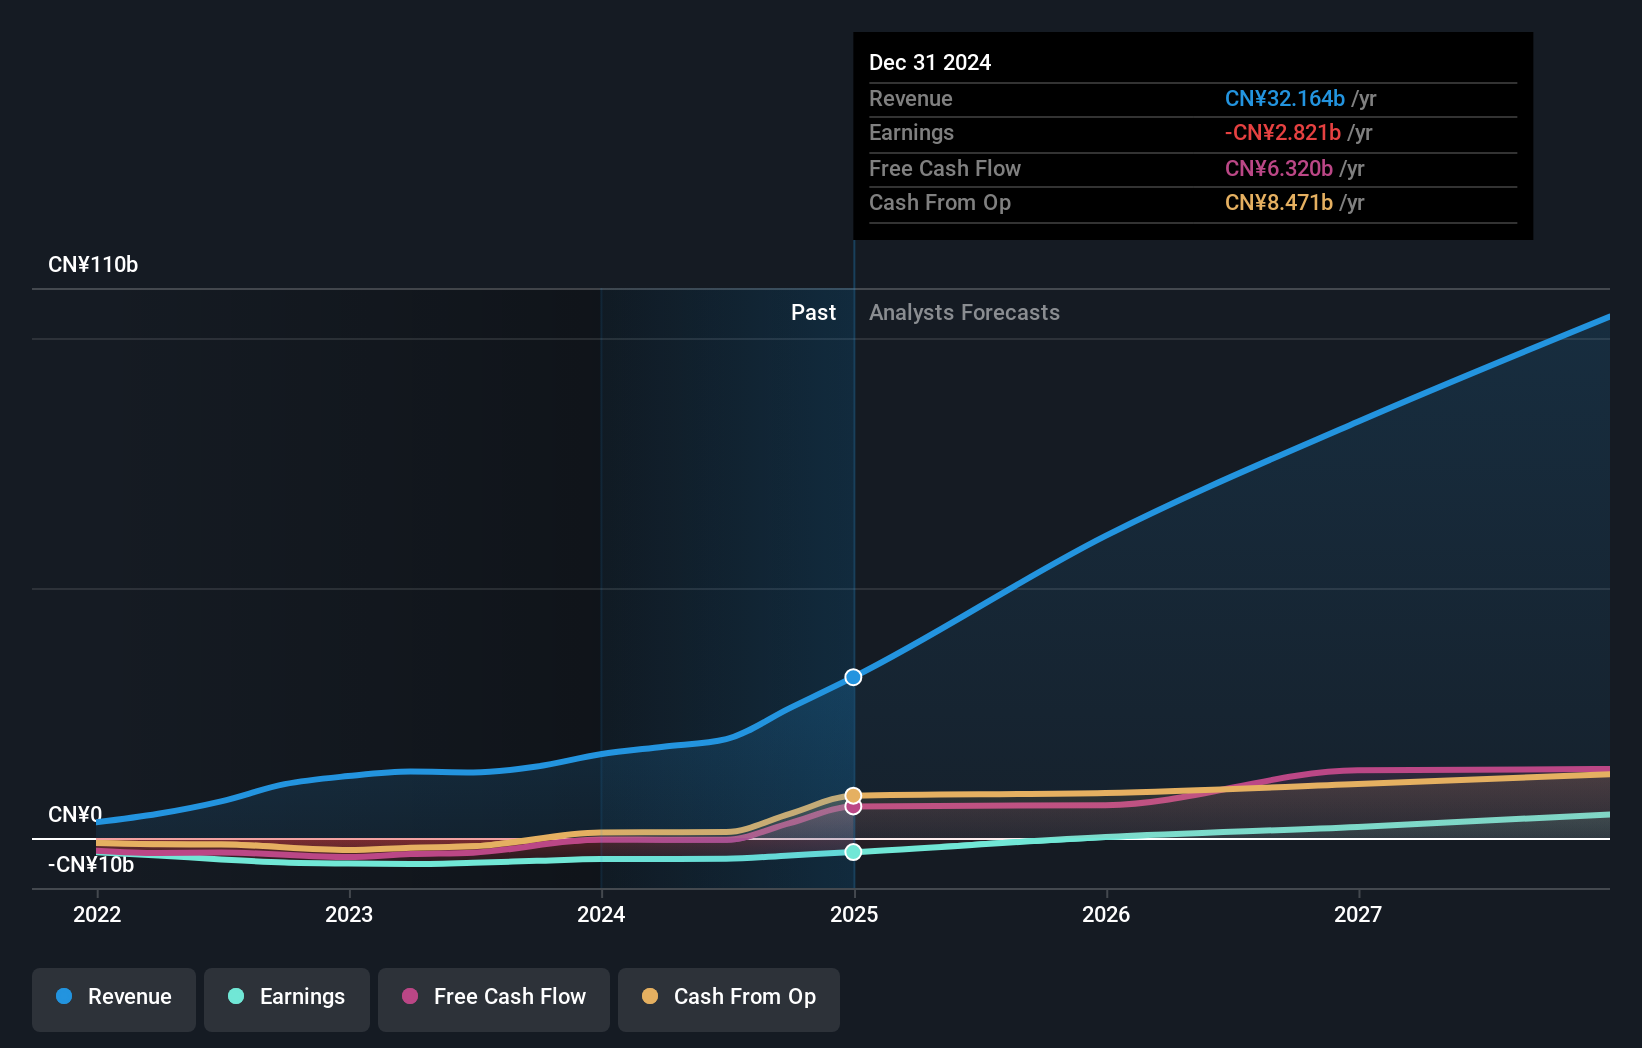
Overview: Zhejiang Leapmotor Technology Co., Ltd. focuses on the research, development, production, and sale of new energy vehicles in Mainland China and internationally, with a market cap of approximately HK$52.44 billion.
Operations: The company generates revenue of CN¥78.59 billion from the production, research and development, and sales of new energy vehicles.
Insider Ownership: 16.5%
Zhejiang Leapmotor Technology has demonstrated significant growth, with first-half 2026 sales reaching CNY 38.11 billion and net income rising to CNY 208.41 million. The company's earnings are expected to grow significantly at 43.29% annually, outpacing market averages, while revenue is projected to increase by 22.3% per year. Insider ownership is strong, with substantial buying activity observed recently and no major selling, indicating confidence in future prospects despite trading below estimated fair value.
- Navigate through the intricacies of Zhejiang Leapmotor Technology with our comprehensive analyst estimates report here.
- According our valuation report, there's an indication that Zhejiang Leapmotor Technology's share price might be on the expensive side.
KCE Electronics (SET:KCE)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: KCE Electronics Public Company Limited, along with its subsidiaries, manufactures and distributes electric printed circuit boards (PCBs) under the KCE trademark across America, Europe, and Asia, with a market capitalization of THB77.72 billion.
Operations: The company's revenue is primarily derived from its Printed Circuit Board Business at THB16.62 billion, followed by the Prepreg and Laminate Business at THB2.86 billion, and the Chemical Business at THB1.01 billion.
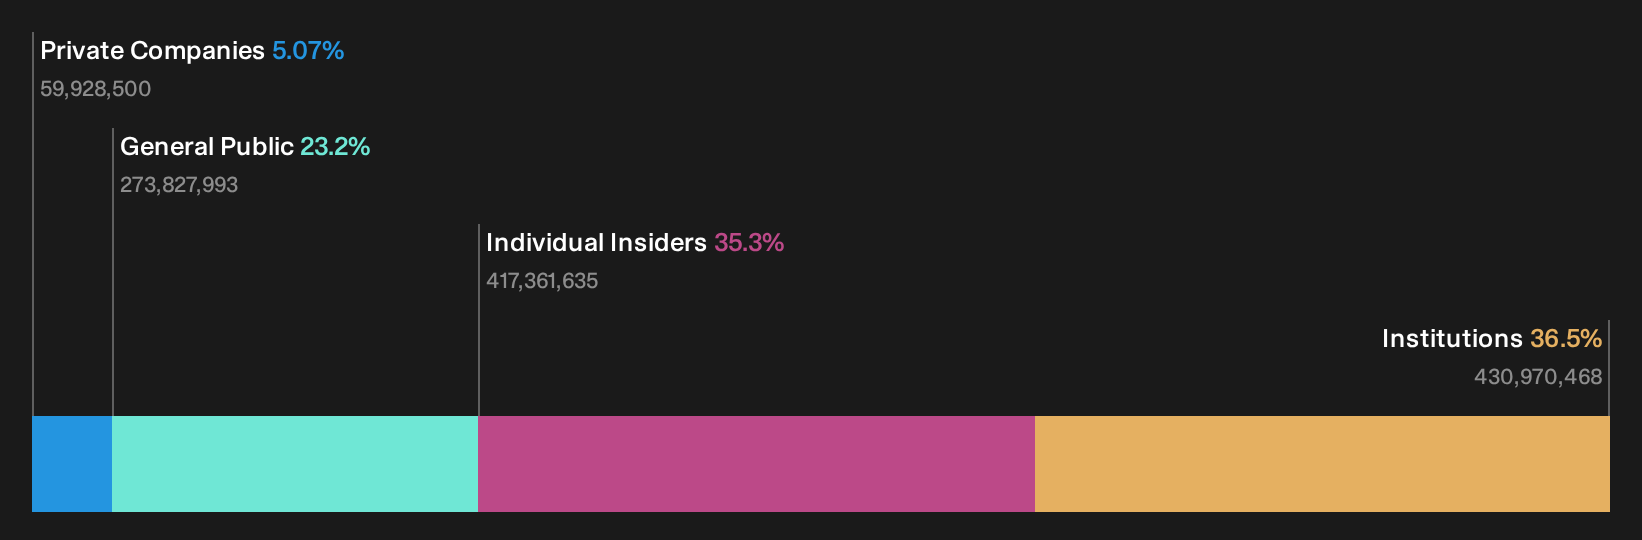
Insider Ownership: 35.3%
KCE Electronics is experiencing significant earnings growth, forecasted at 26.52% annually, outpacing the Thai market's average. Despite a volatile share price and slower revenue growth of 9.6% per year compared to its earnings, insider ownership remains high with no recent substantial trading activity. Recent financials show improved performance with second-quarter revenue rising to THB 3.67 billion and net income increasing to THB 275.92 million year-over-year, reflecting strong operational momentum.
- Get an in-depth perspective on KCE Electronics' performance by reading our analyst estimates report here.
- Our valuation report here indicates KCE Electronics may be overvalued.
Inner Mongolia Furui Medical Science (SZSE:300049)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Inner Mongolia Furui Medical Science Co., Ltd. operates in the medical science industry and has a market capitalization of CN¥11.87 billion.
Operations: Inner Mongolia Furui Medical Science Co., Ltd. generates its revenue through various segments within the medical science industry, although specific segment details are not provided in the available data.
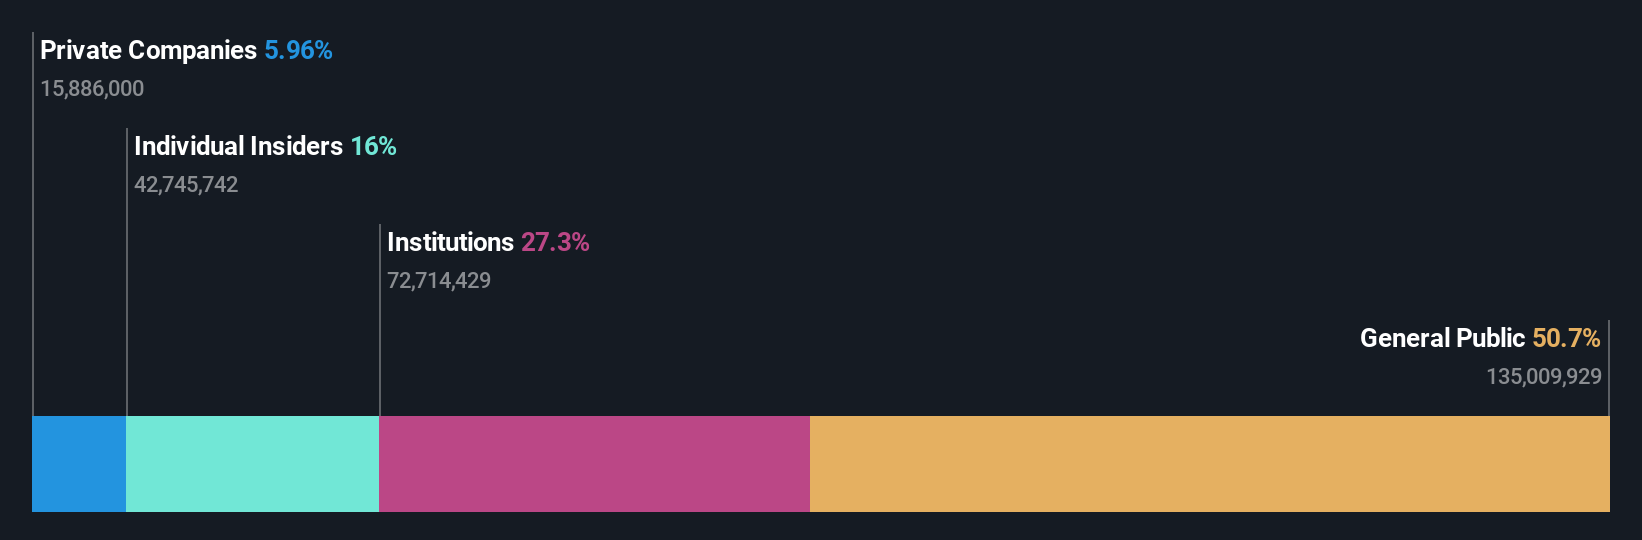
Insider Ownership: 16.3%
Inner Mongolia Furui Medical Science is experiencing robust growth, with earnings increasing by 84.8% over the past year and forecasts suggesting a continued annual profit growth of 39.54%, surpassing the Chinese market average. Revenue is expected to grow at 25.1% annually, outpacing the broader market's 17.1%. Recent financials show revenue reaching CNY 754.79 million for the first half of 2026, alongside net income rising to CNY 63.94 million, indicating strong business performance despite share price volatility and no substantial insider trading activity recently.
- Delve into the full analysis future growth report here for a deeper understanding of Inner Mongolia Furui Medical Science.
- Upon reviewing our latest valuation report, Inner Mongolia Furui Medical Science's share price might be too optimistic.
Taking Advantage
- Explore the 497 names from our Fast Growing Asian Companies With High Insider Ownership screener here.
- Want To Explore Some Alternatives? Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 27 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com