
3 Asian Stocks Estimated To Be Trading Below Intrinsic Value By Up To 26.9%
Amidst the backdrop of geopolitical tensions and fluctuating oil prices, Asian markets have experienced a period of volatility, impacting investor sentiment across the region. In such an environment, identifying stocks that are trading below their intrinsic value can present unique opportunities for investors seeking potential long-term growth.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wacom (TSE:6727) | ¥821.00 | ¥1597.92 | 48.6% |
| Thai Vegetable Oil (SET:TVO) | THB26.75 | THB51.97 | 48.5% |
| P.S.P. Specialties (SET:PSP) | THB7.65 | THB14.80 | 48.3% |
| PAL GROUP Holdings (TSE:2726) | ¥1507.00 | ¥2862.46 | 47.4% |
| Niterra (TSE:5334) | ¥7161.00 | ¥13725.77 | 47.8% |
| Innocean Worldwide (KOSE:A214320) | ₩18550.00 | ₩37080.65 | 50% |
| Ichikoh Industries (TSE:7244) | ¥554.00 | ¥1067.62 | 48.1% |
| BuySell TechnologiesLtd (TSE:7685) | ¥2880.00 | ¥5565.38 | 48.3% |
| AK Medical Holdings (SEHK:1789) | HK$4.91 | HK$9.60 | 48.9% |
| 3SBio (SEHK:1530) | HK$16.22 | HK$32.25 | 49.7% |
Here we highlight a subset of our preferred stocks from the screener.
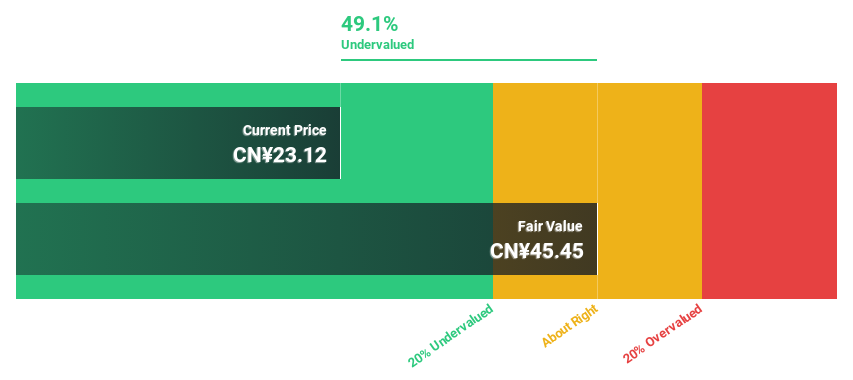
Shenzhen KSTAR Science and Technology (SZSE:002518)
Overview: Shenzhen KSTAR Science and Technology Co., Ltd. focuses on the research, development, production, and sale of uninterruptible power supply products both in China and internationally, with a market cap of CN¥21.60 billion.
Operations: The company's revenue is derived from its New Energy Industry segment, which generated CN¥2.29 billion, and its Data Center Industry segment, which brought in CN¥3.36 billion.
Estimated Discount To Fair Value: 14.8%
Shenzhen KSTAR Science and Technology's recent earnings report highlights robust financial growth, with revenue reaching CNY 2.59 billion for the half year ending June 2026. The stock trades at CN¥37.1, below its future cash flow value of CN¥43.56, suggesting undervaluation based on cash flows. Analysts project significant annual earnings growth of 33.7%, outpacing the Chinese market average, while revenue is forecast to grow at 25.3% per year, indicating strong future prospects despite an unstable dividend track record.
- Upon reviewing our latest growth report, Shenzhen KSTAR Science and Technology's projected financial performance appears quite optimistic.
- Click to explore a detailed breakdown of our findings in Shenzhen KSTAR Science and Technology's balance sheet health report.
WingArc1st (TSE:4432)
Overview: WingArc1st Inc. is a Japanese company that offers software and services, with a market cap of ¥113.66 billion.
Operations: The company generates revenue of ¥31.44 billion from its Data Empowerment Business segment in Japan.
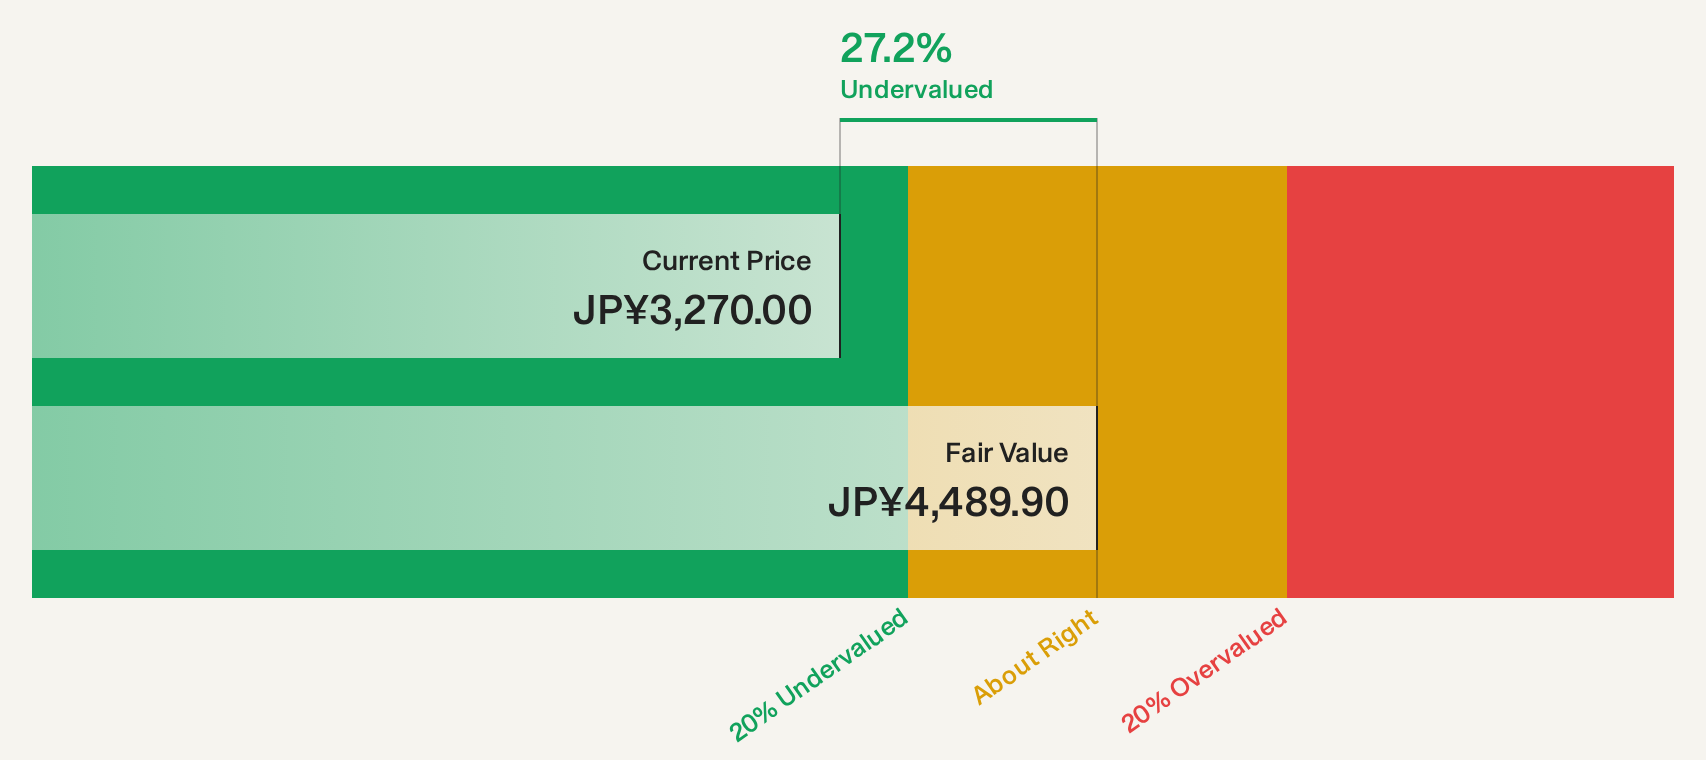
Estimated Discount To Fair Value: 26.9%
WingArc1st is trading at ¥3,270, below its estimated future cash flow value of ¥4,474.86, indicating potential undervaluation. The company's earnings are projected to grow 12.5% annually, surpassing the Japanese market average of 8.7%. Despite slower revenue growth forecasts of 8.7% per year compared to industry benchmarks, recent financials show increased sales and net income for Q1 2026. A share buyback program aims to enhance shareholder value and capital efficiency by May 2027.
- Our expertly prepared growth report on WingArc1st implies its future financial outlook may be stronger than recent results.
- Unlock comprehensive insights into our analysis of WingArc1st stock in this financial health report.
MediPal Holdings (TSE:7459)
Overview: MediPal Holdings Corporation operates in the prescription pharmaceutical wholesale sector in Japan and has a market capitalization of approximately ¥601.51 billion.
Operations: MediPal Holdings generates revenue from three main segments: ¥2.50 billion from the wholesale of medical pharmaceuticals and related products, ¥1.25 billion from cosmetics, daily necessities, and over-the-counter pharmaceutical wholesale, and ¥0.12 billion from businesses related to veterinary drugs and raw materials for food processing.
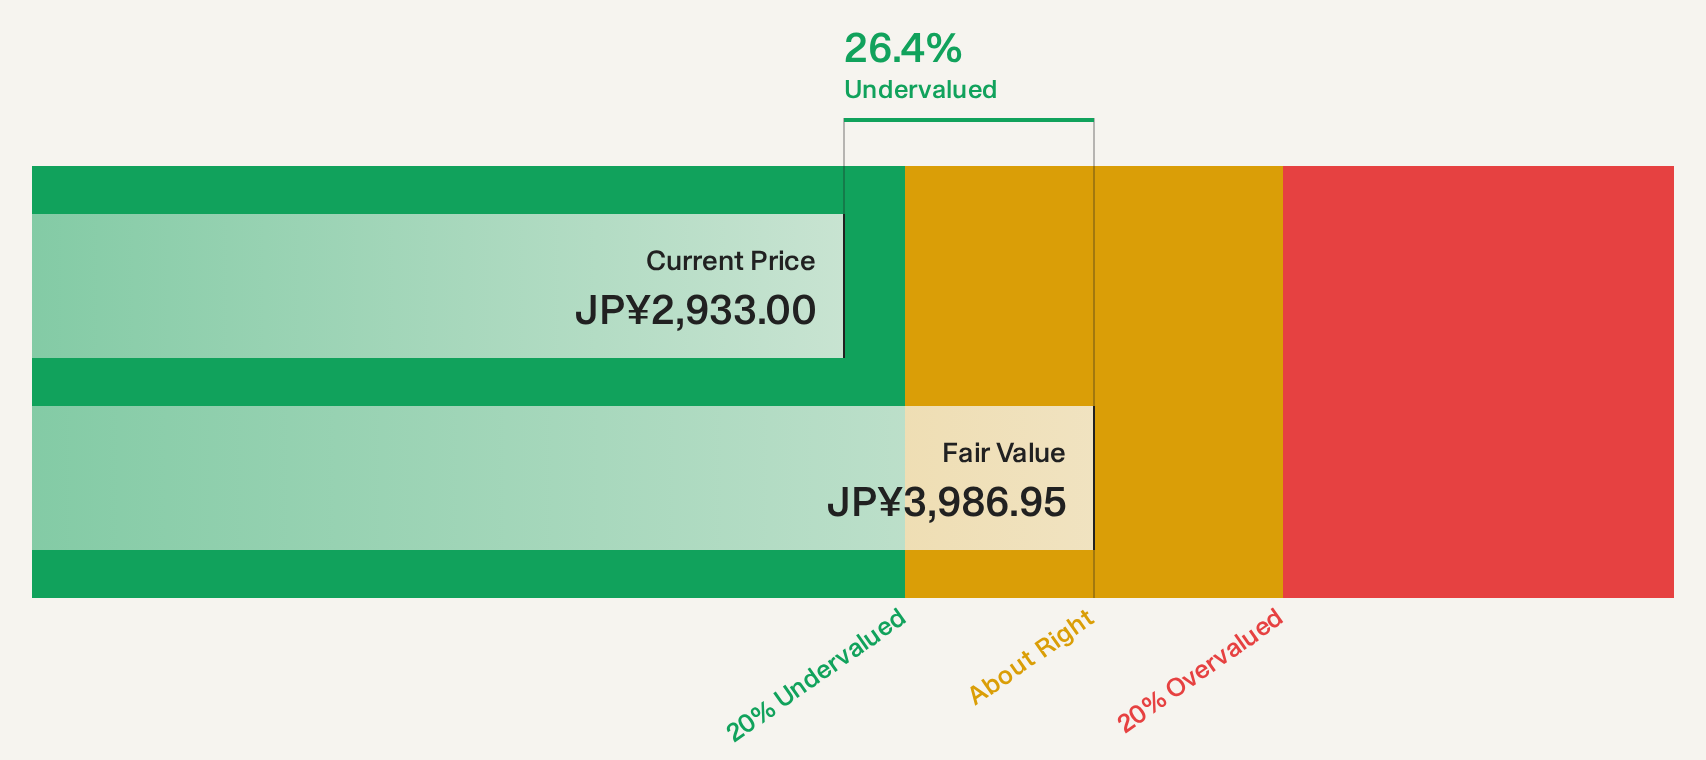
Estimated Discount To Fair Value: 26.3%
MediPal Holdings is trading at ¥2,938.5, significantly below its estimated future cash flow value of ¥3,986.95, suggesting it may be undervalued based on cash flows. Despite low forecasted revenue growth of 2.7% annually and a Return on Equity projected to remain under 10%, the company offers a reliable dividend yield of 2.99%. Recent investor activism highlights concerns over capital allocation and proposes measures like a special dividend to enhance shareholder returns without affecting operations or requiring new debt.
- Insights from our recent growth report point to a promising forecast for MediPal Holdings' business outlook.
- Get an in-depth perspective on MediPal Holdings' balance sheet by reading our health report here.
Seize The Opportunity
- Take a closer look at our Undervalued Asian Stocks Based On Cash Flows list of 82 companies by clicking here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com