
3 Undervalued European Small Caps With Insider Buying
The European market has recently been under pressure due to escalating geopolitical tensions and rising energy prices, which have contributed to inflation concerns and increased government bond yields. Despite these challenges, the current environment may present opportunities for investors interested in small-cap stocks, particularly those with strong fundamentals and insider buying activity.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 34.39% | ★★★★★★ |
| AddLife | 31.9x | 1.8x | 30.79% | ★★★★★★ |
| Franchise Brands | 27.6x | 2.0x | 46.90% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 13.64% | ★★★★☆☆ |
| Saniona | 7.6x | 3.3x | 29.04% | ★★★★☆☆ |
| Linc | 12.6x | 13.1x | 31.82% | ★★★★☆☆ |
| Vistry Group | 6.1x | 0.2x | -14.89% | ★★★☆☆☆ |
| Eurocell | 22.2x | 0.3x | 48.78% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 22.21% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -208.20% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
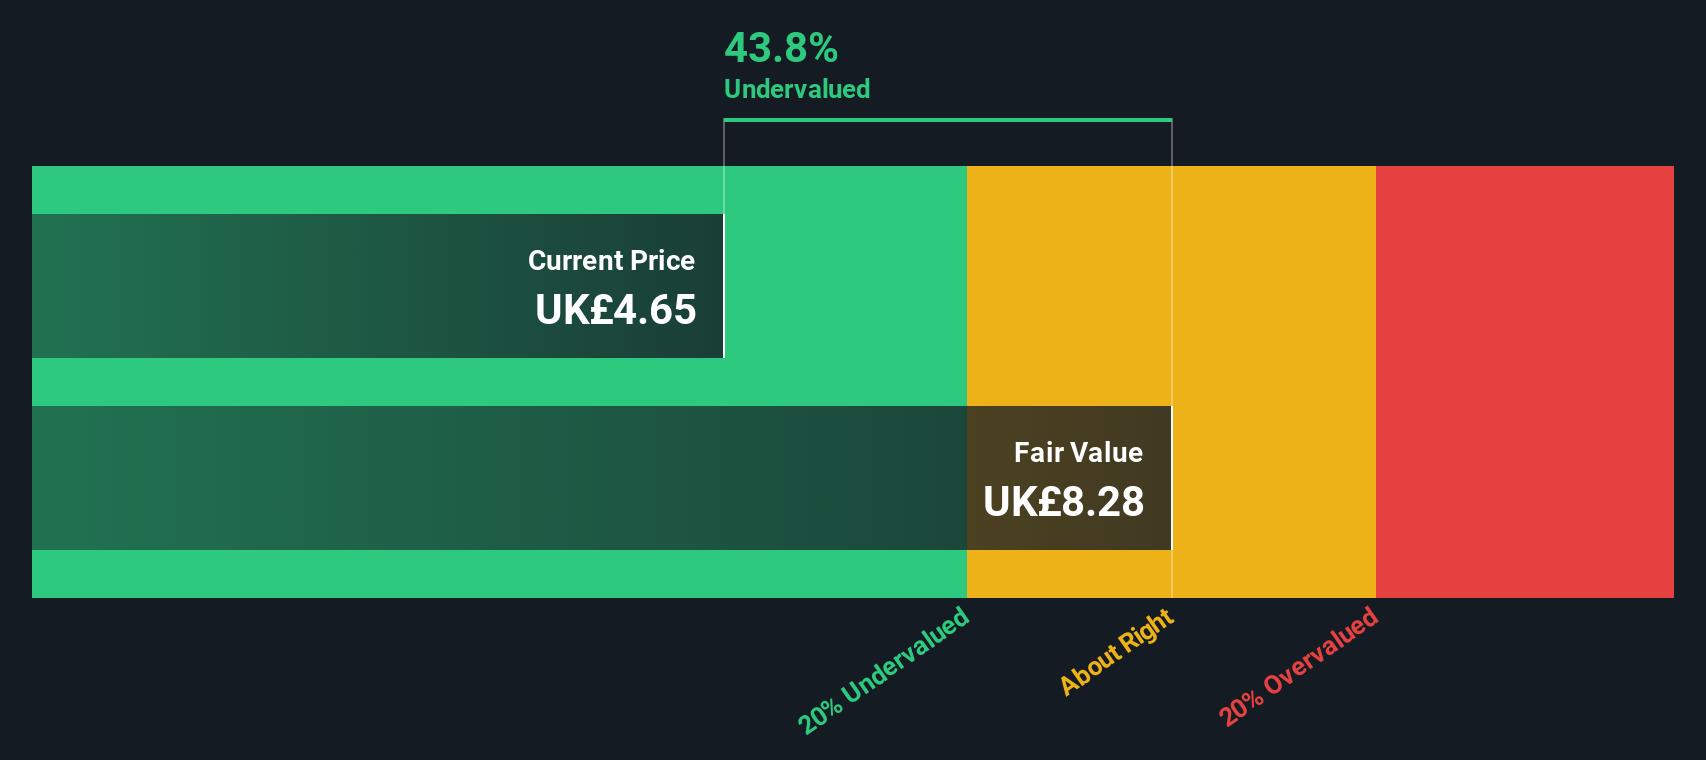
PayPoint (LSE:PAY)
Simply Wall St Value Rating: ★★★★★☆
Overview: PayPoint is a company that provides payment services and retail technology solutions, with operations primarily focused on facilitating transactions and offering a range of consumer payment services, and it has a market capitalization of approximately £0.42 billion.
Operations: PayPoint generates revenue primarily through its Love2shop and Pay Point segments, with recent figures showing £158.23 million and £178.78 million respectively. The company's gross profit margin has seen fluctuations, reaching a high of 66.43% in March 2021 before declining to 40.58% by September 2025. Operating expenses have consistently been a significant component of the cost structure, with general and administrative expenses being a major part of these costs over time.
PE: 9.3x
PayPoint, a European small-cap stock, shows potential for growth with earnings projected to increase by 10.55% annually. Despite relying entirely on external borrowing, indicating higher risk funding, insider confidence is evident through recent share purchases earlier this year. The company recently saw executive changes with the departure of Rakesh Sharma as director in July 2026. This dynamic environment suggests opportunities for investors interested in companies poised for future expansion amidst evolving leadership and financial strategies.
- Click to explore a detailed breakdown of our findings in PayPoint's valuation report.
Gain insights into PayPoint's historical performance by reviewing our past performance report.
Tullow Oil (LSE:TLW)
Simply Wall St Value Rating: ★★★★★☆
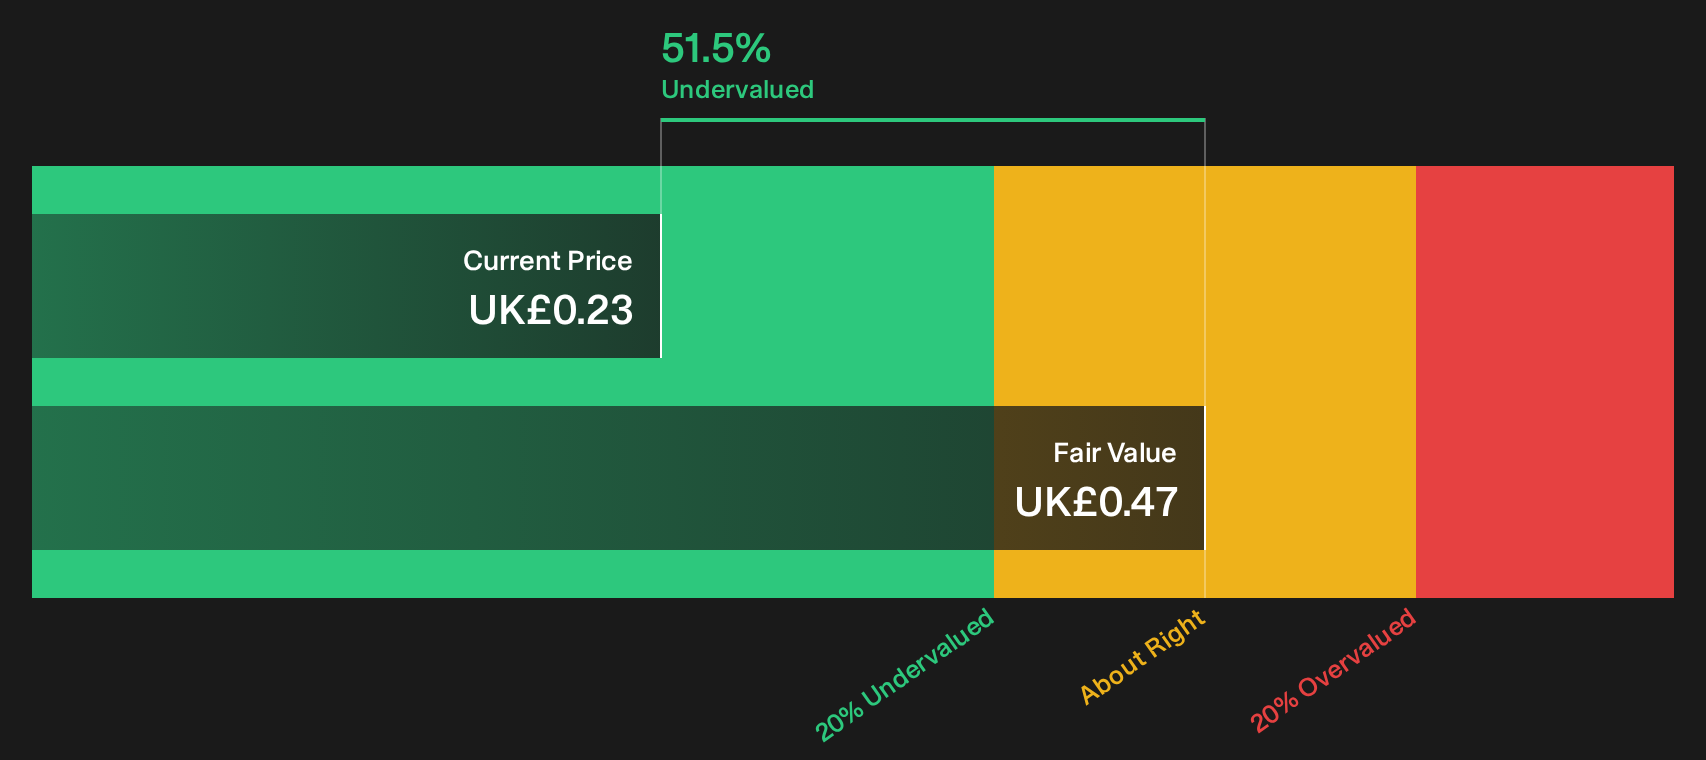
Overview: Tullow Oil is an independent oil and gas exploration and production company primarily operating in Ghana, with a market capitalization of approximately £0.47 billion.
Operations: The company's primary revenue stream is from its operations in Ghana, contributing significantly to its total revenue. Over recent periods, the gross profit margin has shown fluctuations, with a notable peak at 68.20% and a low of 24.56%. Operating expenses have varied widely, impacting net income significantly across different quarters.
PE: -3.9x
Tullow Oil, a smaller player in the European energy sector, has caught attention with its insider confidence. Roald Goethe's purchase of 960,000 shares for £130,560 in recent months indicates belief in the company's potential. Despite volatile share prices and reliance on higher-risk external borrowing, Tullow forecasts earnings growth of over 51% annually. Recent production updates show promising output levels and optimistic guidance for 2026, suggesting room for future growth amidst current financial challenges.
- Delve into the full analysis valuation report here for a deeper understanding of Tullow Oil.
Evaluate Tullow Oil's historical performance by accessing our past performance report.
JM (OM:JM)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: JM is a residential development company operating primarily in Sweden, Norway, and Finland with a market capitalization of SEK 20.5 billion.
Operations: JM's revenue is primarily derived from its operations in Norway, Sweden, and Finland. The company experienced fluctuations in its gross profit margin over the periods reviewed, reaching a peak of 21.86% in Q1 2023 before declining to 10.98% by Q2 2026. Operating expenses have consistently impacted profitability, with general and administrative expenses being a significant component of these costs across the periods analyzed.
PE: -70.6x
JM AB, a player in the European market, recently faced a challenging period with sales dropping to SEK 2.3 billion and a net loss of SEK 88 million for Q2 2026. Despite these hurdles, insider confidence is evident as President & CEO Mikael Åslund increased their holdings by over 56%, investing approximately SEK 600,000. The company is actively expanding with projects like the Freya and Spinnerifabriken developments underway. While reliant on external borrowing, JM's strategic moves could position it well for future growth opportunities.
- Unlock comprehensive insights into our analysis of JM stock in this valuation report.
Examine JM's past performance report to understand how it has performed in the past.

Taking Advantage
- Get an in-depth perspective on all 40 Undervalued European Small Caps With Insider Buying by using our screener here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com