
3 U.S. Financial Stocks With More to Gain From Higher Cash Yields
With the Fed under pressure to tame stubborn inflation and bond markets already pushing up long-term yields, cash and short-duration fixed income are suddenly the main stage rather than the sideshow. That shift can reshape how certain business models earn fees, handle client cash and price risk. This article unpacks what that backdrop might mean for three U.S.-listed stocks exposed to these rate moves and why their stories deserve your attention now.
The stocks discussed below are just a first pass, and the full screen surfaced 56 more U.S.-listed companies tied to brokerage, custody, clearing and cash-like fixed income activities with similarly interesting rate-sensitive stories that are not covered here. To identify, compare and analyze the highest-conviction ideas in this theme, head straight into the U.S. Interest-Rate Beneficiaries in Cash & Bond-Market Infrastructure screener.
FirstSun Capital Bancorp (FSUN)
FirstSun Capital Bancorp is a regional banking platform built around deposits, lending and cash management, which puts it squarely in focus for a screen looking at businesses tied to short-term rates and the economics of customer cash.
"FirstSun operates across both consumer and business segments in high-growth Southwestern and newly entered California markets."
What really matters now is how one less visible pressure on its balance sheet shapes future pricing power and margin resilience.
That pressure on margins is only half the story, and the full narrative for FirstSun Capital Bancorp shows how FirstSun Capital Bancorp could still turn rate volatility into an accelerating cash engine.

Triumph Financial (TFIN)
Triumph Financial plugs directly into the screener’s rate and cash-flow theme through its mix of banking, payments, and freight-focused factoring. This gives investors exposure to both client cash yields and transaction-heavy short-term credit flows.
Triumph Financial earns most of its US$450.8 million revenue in the United States, with banking at about US$227 million, factoring at US$130 million, and payments at US$74 million, and carries a market cap near US$1.6b.
"The continued scaling of TriumphPay and related payment services is driving strong revenue growth and efficiency, as evidenced by rising EBITDA margins (with a stated long-term goal of 40%). This is benefiting from network effects and the digitalization of freight finance, which is expected to further boost net margins and overall profitability."
What happens if one unseen pressure on Triumph Financial’s freight-focused credit quality changes the trajectory of those margin ambitions?
If that credit pressure has your attention already, the full narrative for Triumph Financial shows where Triumph Financial’s freight network, payments engine and risk controls could be quietly decoupling.

Bank of Marin Bancorp (BMRC)
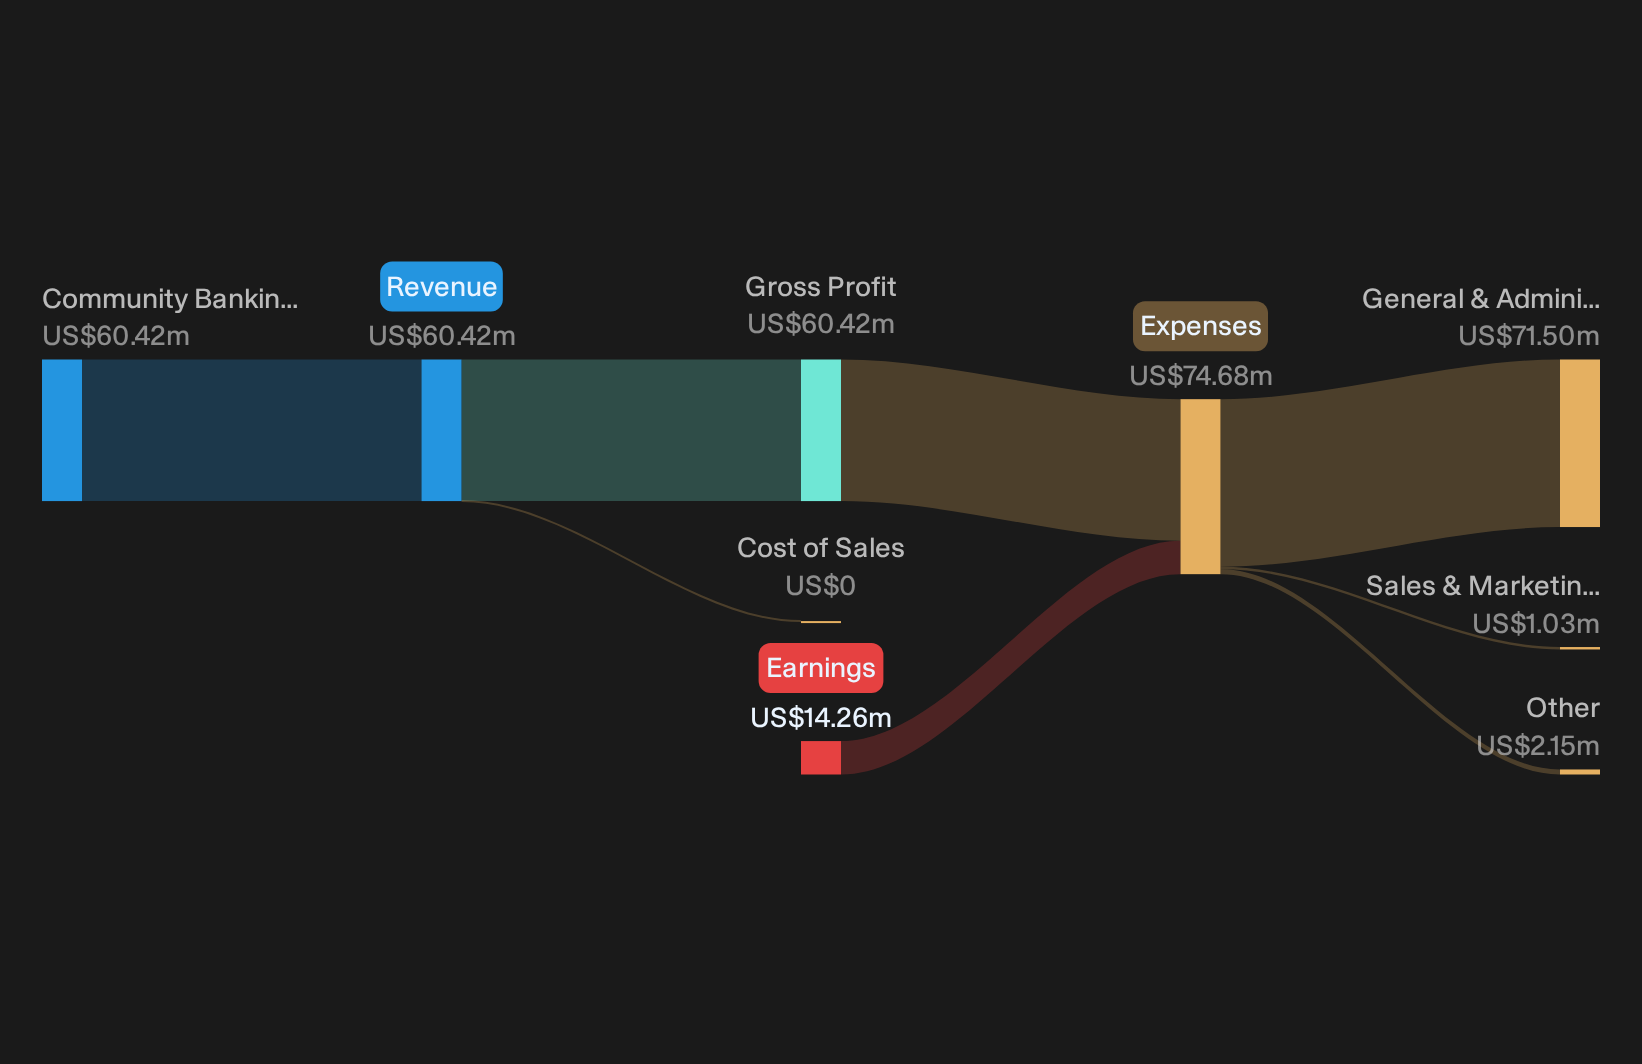
Bank of Marin Bancorp plugs into the interest rate theme through its mix of loans, cash accounts and trust custody services for local businesses and real estate clients, earning about US$60 million from community banking in the United States, with a market cap near US$444 million.
Bank of Marin Bancorp is already wired into how short term rates shape funding costs and cash returns for its Northern California client base. This makes the next leg of the rate cycle especially important for how its business model evolves from here.
"Ongoing targeted investment in digital infrastructure and technology, including mobile banking and online lending upgrades, positions the bank to drive operational efficiency and improve customer engagement, which should support margin expansion and lower long-term costs."
What really moves the story from here is how one quiet shift in its funding mix and loan pricing balance filters through to those future margins.
That quiet shift is exactly what the full narrative for Bank of Marin Bancorp unpacks, showing where Bank of Marin Bancorp’s funding mix and pricing power could be quietly accelerating.
Seeking Alternatives Before The Crowd?
Fresh themes move fast. Breakout momentum can be caught or missed while ideas stay under the radar for now. Consider researching opportunities early, rather than waiting until prices have already moved.
- Spot under-the-radar momentum shifts by scanning a curated 35 high quality undervalued stocks that may be trading below what their cash flows and balance sheets imply.
- Explore the AI theme more selectively by filtering for 75 profitable AI stocks that aren't just burning cash where revenue and costs already align instead of focusing on less proven experiments.
- Target staying power in choppy markets by zeroing in on a 11 resilient stocks with low risk scores that score well on resilience and financial robustness before they become more widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com