
Is Lung Cancer Trial Win Altering The Investment Case For Merck (MRK)?
- Perspective Therapeutics previously announced a trial collaboration in which Merck supplies Keytruda for combination testing with [212Pb]PSV359 in FAP-a expressing non small cell lung and colorectal cancers, while Akeso and Summit Therapeutics recently reported Phase 3 survival data showing ivonescimab outperformed Keytruda in lung cancer.
- The mix of fresh competitive oncology data against Keytruda and Merck’s own partnership and pipeline activity highlights how the group’s long term cancer revenue mix and investment priorities may need to adjust over time.
- We will examine how Merck's investment narrative is tested by ivonescimab's survival data against Keytruda in lung cancer treatment.
Merck Investment Narrative Recap
To own Merck, you need to believe the pharma group can turn its broad pipeline and recent launches into enough cash flow to soften future Keytruda exclusivity risk and pricing pressure. The immediate story is about execution. That includes turning forecast earnings growth, a rich late stage portfolio and heavy manufacturing spend into cleaner margins after recent one off hits.
The short term swing factor still sits in oncology and immunology updates that can support confidence in that pipeline. Ivonescimab’s survival data is an operational wake up on competition rather than a thesis breaker. The bigger current risk remains whether new products can offset pricing, tariffs and any further softness in key vaccines like Gardasil.
The fresh clinical trial collaboration with Perspective Therapeutics looks most relevant in this context. Merck is supplying Keytruda to test it alongside [212Pb]PSV359 in FAP a expressing non small cell lung and colorectal cancers. The trial has already completed enrollment in the first three monotherapy dose cohorts, so the combination arm slots into an ongoing program rather than starting from scratch.
For you as a shareholder, the interest is that this kind of partnership gives Merck extra shots on goal around Keytruda at a time when competition from drugs like ivonescimab is intensifying. It speaks directly to execution on oncology catalysts, while still leaving the well flagged risks in tariffs, vaccine trends, high debt and upcoming Keytruda loss of exclusivity firmly on the table.
What The Current Merck Consensus Is Asking You To Believe
Merck's consensus story from analysts is built on a fairly tight set of numerical assumptions rather than loose optimism. Forecasts point to revenue rising by 4.1% a year over the next three years, with profit margins moving from 4.8% today to 29.9% by around 2029. That margin shift underpins a jump in expected earnings from US$3.2b today to US$22.4b in the same timeframe.
At face value, that means earnings would need to rise by roughly US$19.2b to reach the 2029 consensus. The gap between current profitability and those future targets is wide, so oncology execution, price pressure, tariff risk and any hit from a Keytruda loss of exclusivity all matter for how realistic that bridge looks. For an investor watching new lung cancer competition like ivonescimab, the question is not just whether Merck can grow, but whether the pipeline and collaborations can support a move toward that margin profile without relying on one flagship drug.
Merck's narrative projects US$75.1b revenue and US$22.4b earnings by 2029. This assumes 4.1% yearly revenue growth and an earnings increase of about US$19.2b from US$3.2b today.
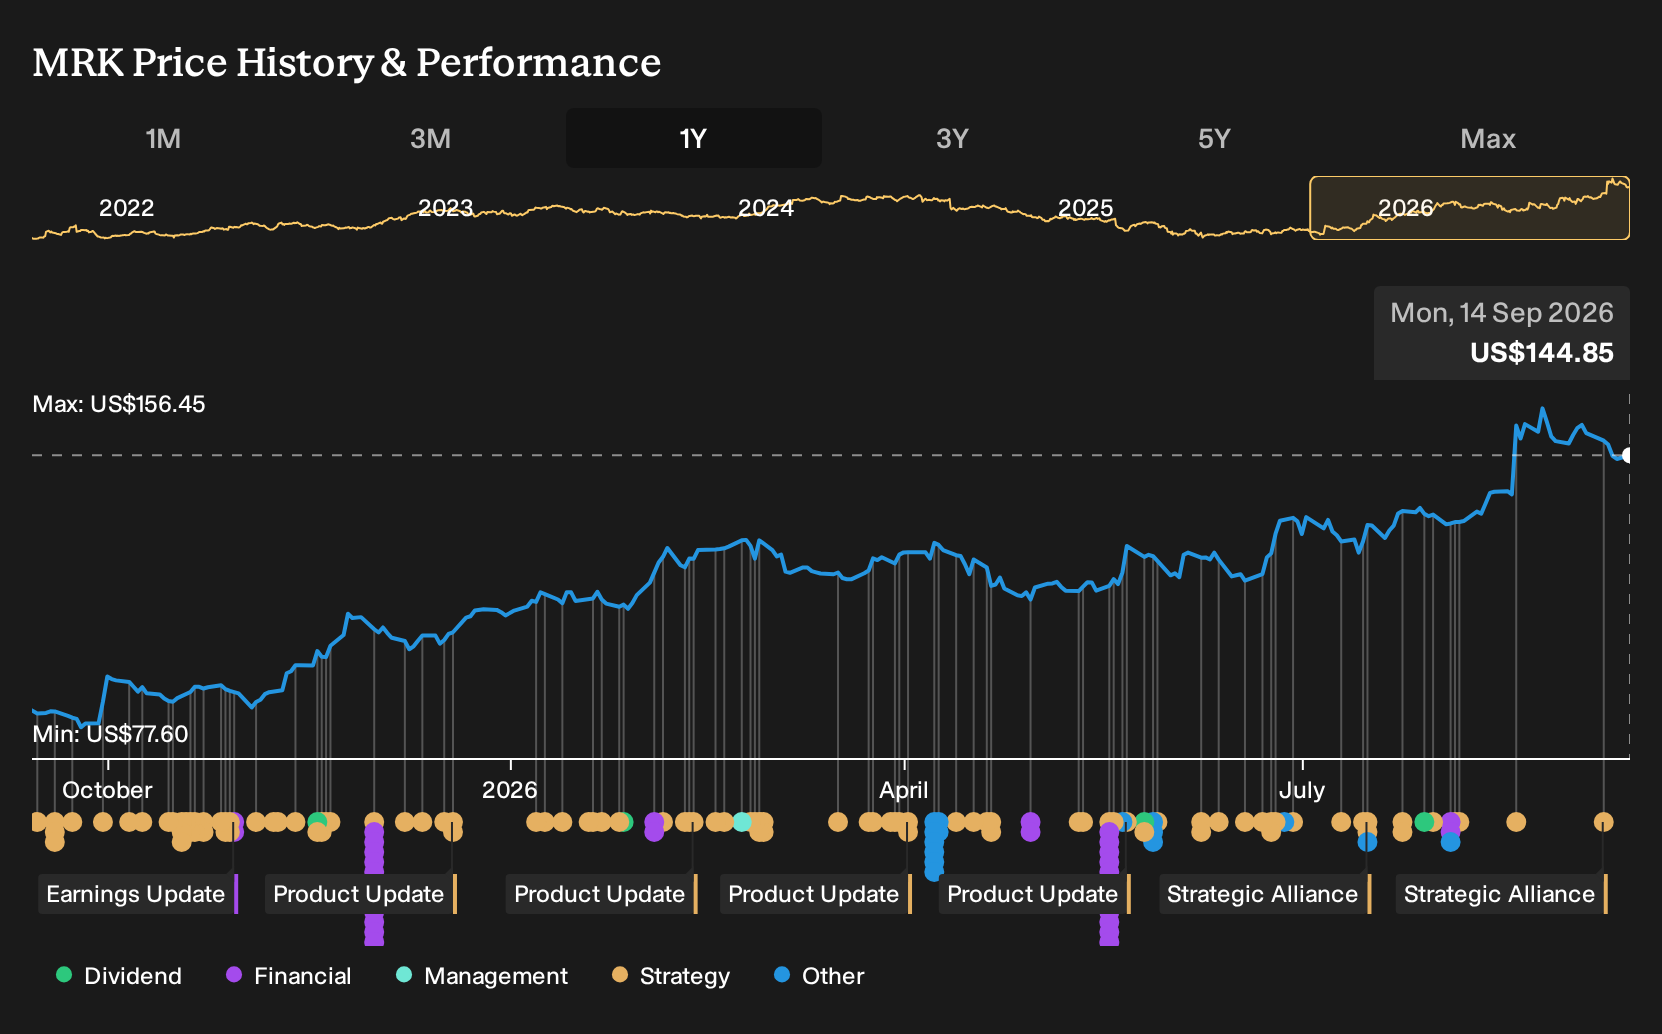
Uncover why Merck's fair value points to a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For some of the most optimistic analysts, the real swing factor is Merck’s earnings power rather than just Keytruda competition. Before this news, the bullish camp was modelling revenue of US$81.9b and earnings of US$29.5b by 2029, far above consensus. You should expect views like that to be revisited as new oncology data is released.
Explore 6 other Merck fair value estimates, including one that suggests the potential for as much as 62% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Merck research is our analysis highlighting 2 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Merck. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Merck's overall financial health at a glance.
Looking For More Investment Ideas Beyond Merck?
Once you have a handle on Merck, it can help to widen the lens and compare it with other opportunities that fit different risk, income and balance sheet profiles.
- For income focused investing, scan for companies that combine sturdy cash generation with yields above 5% using our 6 dividend fortresses to see which ones warrant a closer look.
- If capital preservation and steadier business models appeal more, filter for companies with lower risk scores through our 11 resilient stocks with low risk scores and see how they compare with your current holdings.
- To source potential future winners before they are widely followed, use the 15 high quality undiscovered gems and see which under the radar businesses match your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com