
Does Yves Return Change The Bull Case For Maple Leaf Foods Stock?
- Maple Leaf Foods has brought back the Yves Veggie Cuisine brand to Canadian grocery shelves, reintroducing six refrigerated plant-based staples including multiple Veggie Ground Round flavours and deli-style slices such as Veggie Ham, Bologna, and Turkey with support from national retailers.
- The return of Yves concentrates Maple Leaf Foods' plant-based efforts around an established label, which may help utilisation of existing production capacity and sharpen category focus in a segment where consumer preferences continue to evolve.
- We will now explore how Maple Leaf Foods' decision to relaunch Yves Veggie Cuisine could influence the broader investment narrative around its protein portfolio.
Scan how Maple Leaf Foods' renewed push into plant-based protein compares with other protein players backed by strong balance sheets using the list of solid balance sheet and fundamentals (7 results).
Maple Leaf Foods Investment Narrative Recap
To own Maple Leaf Foods, you need to believe in a protein-focused portfolio that can keep lifting earnings through efficiency gains, higher value products and disciplined capital use. The short term swing factor is execution on cost programs and pricing in core meat, not Yves. The Yves relaunch looks incremental rather than a material near term earnings catalyst.
The biggest near term risk stays the same. Margin progress still leans on pork market conditions, consumer acceptance of pricing and marketing spend that raises SG&A. Plant based adds complexity and some brand upside, but it also adds category risk if demand is choppy or promotions fail to pull through volume.
There has been no other fresh announcement flagged around this Yves news, so the cleanest link is to Maple Leaf Foods' broader push into higher value protein. Management is already investing in automation, such as the London Poultry facility and Bacon Center of Excellence, and is emphasizing efficiency-driven EBITDA benefits.
This operational backdrop matters for how investors see the Yves return. If the plants run fuller and fixed costs are spread over more volume, that supports the earnings growth profile analysts expect, even with only modest revenue growth assumptions. If cost savings disappoint or category spending runs hot, the extra complexity from another plant based push could instead contribute to earnings volatility.
Analysts project Maple Leaf Foods' revenues will reach CA$5.6b and earnings will be CA$467.3m by 2028, which implies 4.2% yearly revenue growth and an earnings increase of about CA$372.7m from CA$94.6m today.
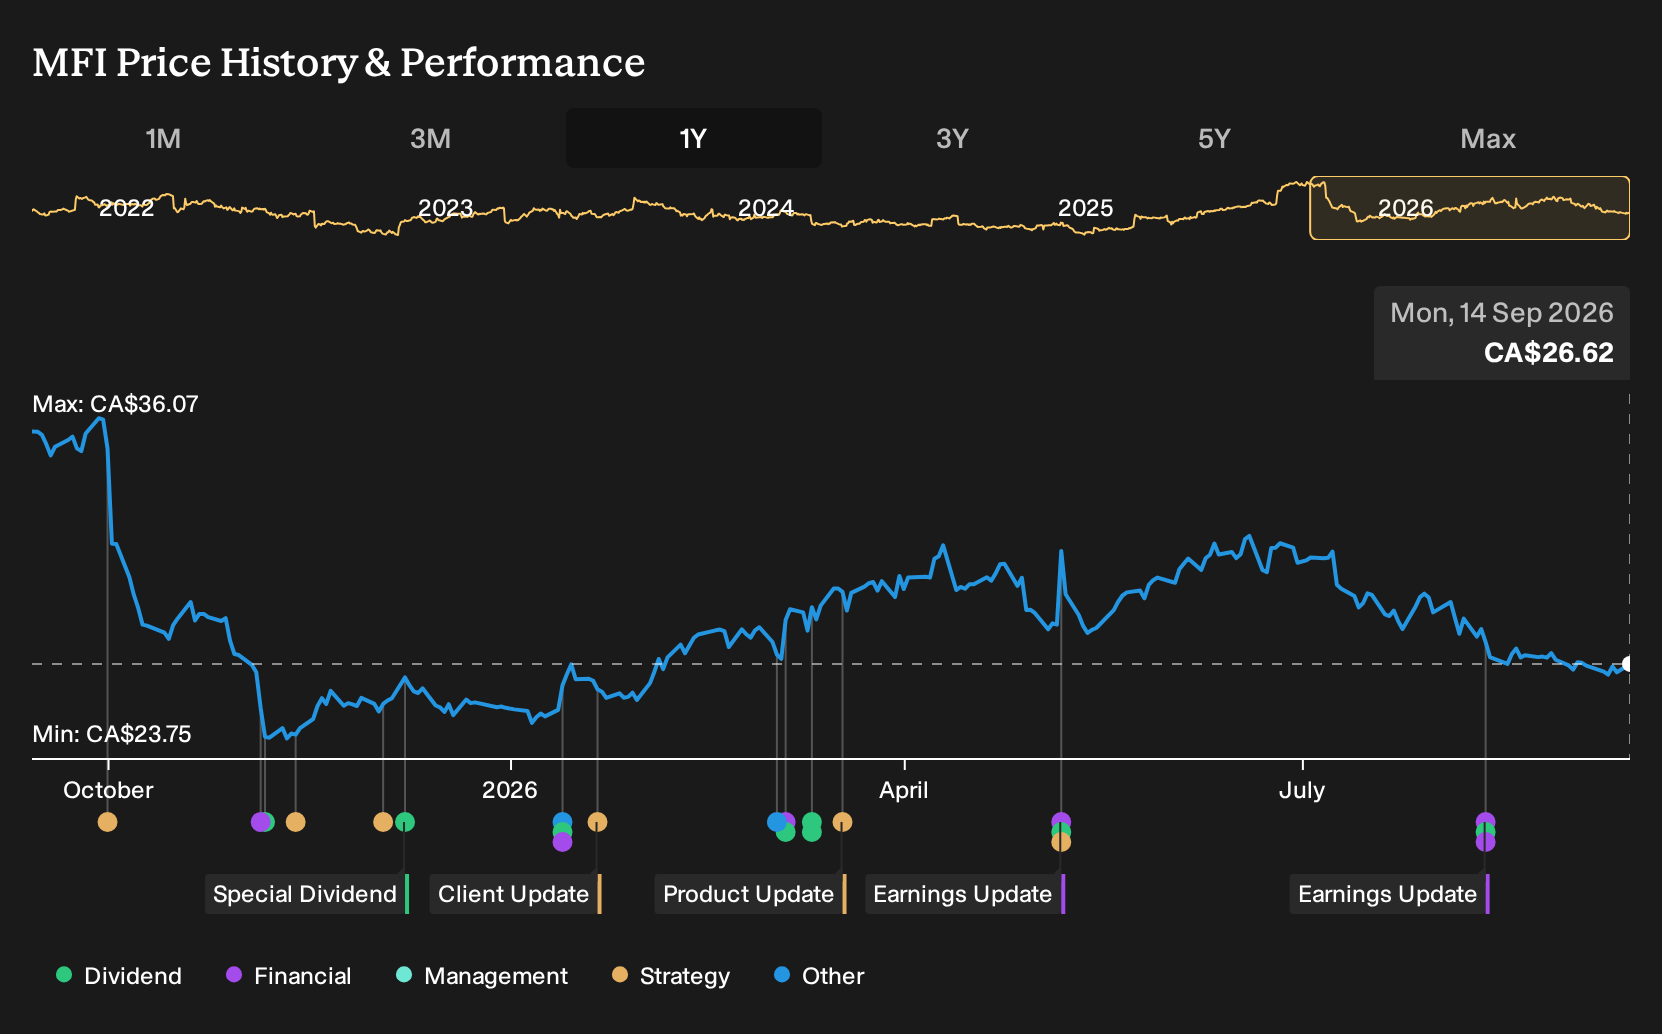
Uncover how Maple Leaf Foods' fair value indicates a 35% potential upside to its current price that could narrow quickly if sentiment toward Maple Leaf Foods shifts.
Exploring Other Perspectives
Simply Wall St Community members put fair values for Maple Leaf Foods between CA$35.90 and CA$83.26, based on just 2 individual models, which shows how far opinions can stretch. Add in risks around pork markets, higher SG&A and the Canada Packers spin-off, and you have plenty of reasons to test multiple viewpoints yourself.
Explore another Maple Leaf Foods fair value estimate, including one that suggests potential upside of up to 213% from the current price.
The Verdict Is Yours
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Maple Leaf Foods research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Maple Leaf Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Maple Leaf Foods' overall financial health at a glance.
Looking For More Investment Ideas Beyond Maple Leaf Foods?
Once you have a view on Maple Leaf Foods, it often helps to widen the lens and compare it with other businesses that match your risk tolerance, income needs and return goals. The Simply Wall St Screener can surface opportunities that fit different styles, whether you want potential mispricing, resilience or income.
- If you are hunting for companies where quality and price might be out of sync, scan through 3 high quality undervalued stocks that could be trading below what their fundamentals suggest.
- If capital preservation sits high on your priority list, narrow your search to 1 resilient stocks with low risk scores that score well on financial strength and volatility.
- If you prefer to back future growth stories before they hit the mainstream, focus on 9 high quality undiscovered gems that pair solid fundamentals with limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com