
Samsara (IOT) Turned Profitable And Raised Guidance, Is The Valuation Already Priced In?
Samsara (IOT) is back in focus after its latest earnings release showed revenue of US$508.44 million, a swing to net income, and raised guidance that reinforced the company’s view of continued business momentum.
The latest jump in Samsara’s share price, with an 11.80% 1-day share price return and 31.42% 90-day share price return to US$42.91, aligns with the move to profitability and higher guidance. However, the 8.77% 1-year total shareholder return points to a more modest longer-term journey so far.
Capitalize on Samsara’s profitability turn by scanning a hand picked group of fast growing software and IoT platforms in the 15 high quality undiscovered gems.Samsara now trades about 22% below the average analyst target after a sharp run toward profitability. Is that a cautious market misread, or a fair response to how much is already priced in?
Most Popular Narrative: 34% Undervalued
Compared with Samsara’s last close at $42.91, the most followed narrative argues for a fair value of $65.00. This frames the recent profitability turn as only part of a bigger story on recurring revenue and data scale.
Samsara is building a platform that digitizes the physical world through a combination of software, hardware, and AI. The company provides tangible improvements in safety and operational efficiency while rapidly expanding its AI capabilities.
See why 12 investors see Samsara as 34% undervalued.
Result: Fair Value of $65.00 (UNDERVALUED)
Still, Samsara’s thin profitability and exposure to fleet and infrastructure spending mean that softer customer budgets or intensifying competition could quickly challenge that 34% undervalued narrative.
Find out about the key risks to this Samsara narrative.
Another View On Samsara’s Valuation
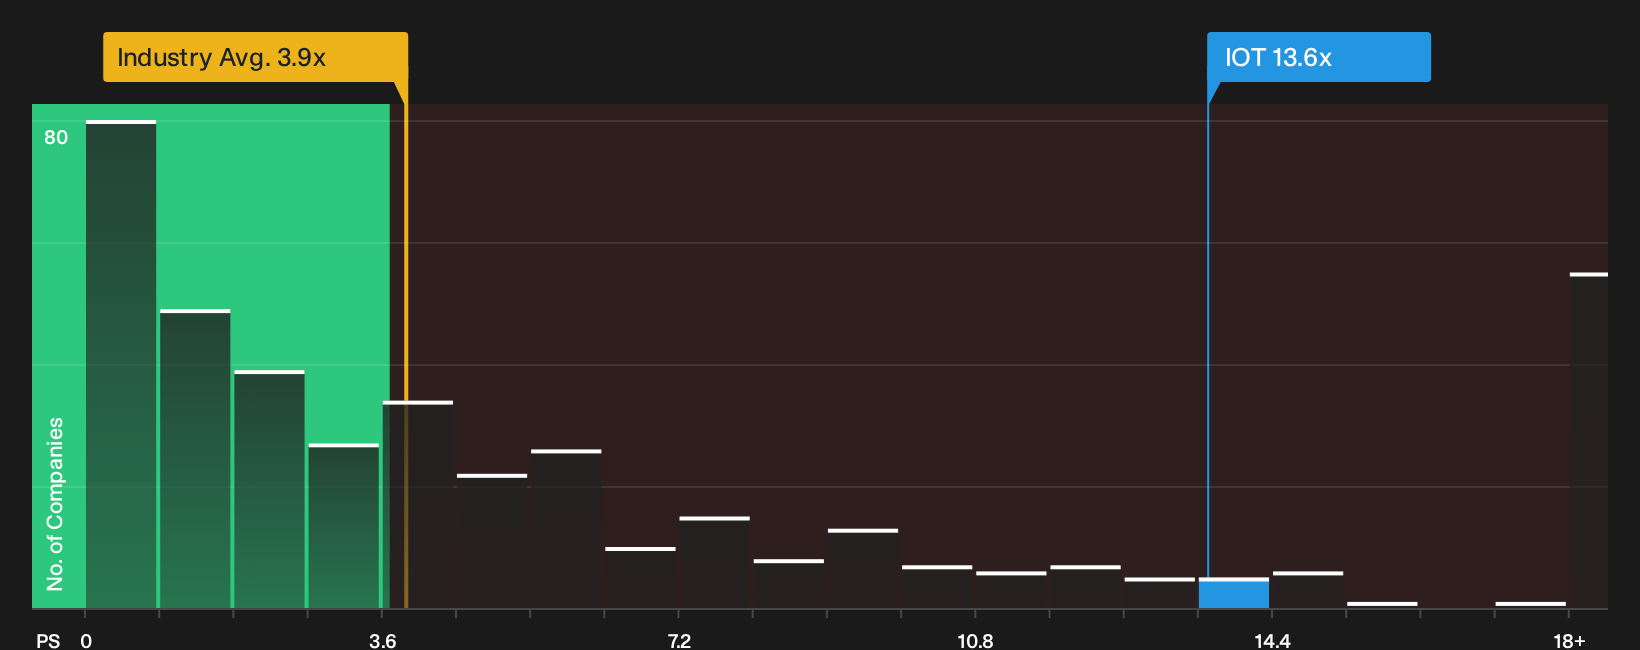
The first narrative leans on a $65.00 fair value for Samsara, yet the SWS fair ratio comparison tells a different story. At a P/S of 13.6x versus a fair ratio of 8.9x and a US software average of 3.9x, investors are paying a hefty premium that could cut both ways.
That gap suggests meaningful valuation risk if sentiment cools or peers start to close the growth and profitability gap. The key question is whether Samsara’s data and AI edge can keep that premium feeling justified for long.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Samsara is split between enthusiasm for the profitability turn and caution around valuation risk. This means the real edge comes from doing your own homework quickly and stress-testing both sides of the story. To weigh those trade offs clearly, start with the 3 key rewards and 2 important warning signs.
Looking for more Samsara-like investment ideas?
If Samsara has sharpened your focus on where capital might work harder, do not stop at a single ticker. Broader idea hunting can quickly reshape your watchlist and highlight opportunities you might otherwise miss.
- Target fresh upside potential by scanning a curated pool of small, higher risk opportunities through the 3 elite penny stocks with strong financials.
- Zero in on pricing gaps by reviewing companies that pair stronger fundamentals with appealing entry points in the 35 high quality undervalued stocks.
- Strengthen portfolio resilience by assessing businesses with steadier balance sheets and cleaner financial profiles in the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com