
Alliant Energy (LNT), What Is Behind The Latest Attention?
Alliant Energy (LNT) is back in focus after a recent share move that left the stock down 5.2% over the past month and 9.4% over the past 3 months. Investors are reassessing expectations.
That pullback comes after a softer run in the short term, with the share price sliding over the past week and month, even though Alliant Energy still shows a positive year to date share price return and a higher one year total shareholder return that reflects dividends reinvested.
Scan how Alliant Energy compares with other utilities showing recent pullbacks and potential resilience across a hand picked set of 11 resilient stocks with low risk scores.
After that slide, Alliant Energy now trades at a small discount to one estimate of intrinsic value and a wider gap to analyst targets. Is the market’s caution sensible, or has pricing drifted too far?
Most Popular Narrative: 15% Undervalued
On the most followed view, Alliant Energy screens slightly cheap, with that framework pointing to a fair value of $79.13 against the recent $66.92 close. That gap rests on a very specific growth and data center story.
The accelerating construction and onboarding of large-scale data centers in Alliant's Midwest service areas highlight a strong, sustained uptick in electricity demand, directly linked to population and economic growth in the region, which is expected to drive significant increases in revenue and top-line growth over the next several years.
The company's adaptive resource planning and regulatory flexibility in Iowa and Wisconsin allows rapid deployment of new generation capacity, positioning Alliant to capture higher allowed returns and efficiently expand its regulated asset base, supporting long-term earnings growth and margin expansion.
See why 5 investors see Alliant Energy as 15% undervalued.
Result: Fair Value of $79.13 (UNDERVALUED)
Still, the bullish Alliant Energy story relies heavily on large data center deals and supportive regulators, and any delay or pushback could quickly weaken that thesis.
Find out about the key risks to this Alliant Energy narrative.
Another View on Alliant Energy’s Price Tag
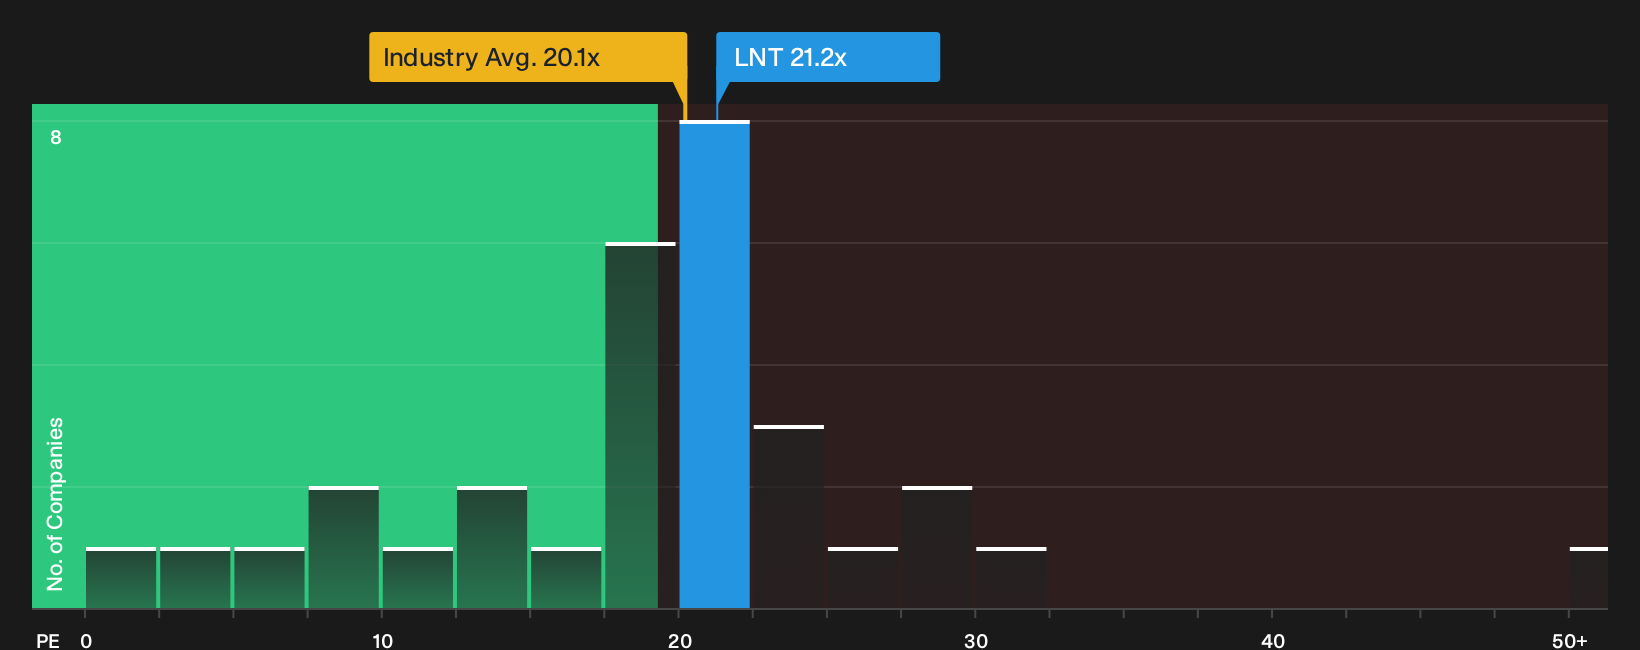
There is a wrinkle. On earnings, Alliant Energy trades on a P/E of 21.2x, which is higher than both the US Electric Utilities industry on 20.3x and its peer group at 18.8x, even though the fair ratio sits only slightly higher at 21.7x.
That mix of a small discount to the fair ratio but a premium to the sector and peers points to limited room for error rather than a clear bargain. How comfortable are you paying up for this story if the growth narrative softens at all?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Alliant Energy’s valuation can be confusing, so move quickly, review the full picture of risks and rewards, and weigh the 2 key rewards and 2 important warning signs carefully.
Looking for more Alliant Energy sized opportunities?
If Alliant Energy has you rethinking what value and resilience look like, do not stop here. Use the screener to surface a wider bench of potential candidates before the next move gets crowded.
- Target steadier compounding by scanning a curated set of companies with strong cash positions and lower leverage via our list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced potential by reviewing a focused group of quality businesses trading below estimated worth using the 35 high quality undervalued stocks.
- Strengthen your income stream by checking out reliable payers and their yields through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com