
Undiscovered Gems in Global Markets to Watch in September 2026
As geopolitical tensions and rising oil prices exert pressure on global markets, small-cap indices like the Russell 2000 have experienced notable declines, reflecting broader economic concerns. In this environment of heightened volatility and inflationary pressures, identifying stocks with resilient business models and growth potential becomes crucial for investors seeking to navigate these challenges.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Dogan Sirketler Grubu Holding (IBSE:DOHOL)
Simply Wall St Value Rating: ★★★★★☆
Overview: Dogan Sirketler Grubu Holding A.S. operates in diverse sectors including electricity generation, industry and trade, automotive trade and marketing, finance and investment, internet and entertainment, and real estate investment across Turkey with a market capitalization of TRY56.82 billion.
Operations: Dogan Sirketler Grubu Holding A.S. generates significant revenue from its financing and investment segment at TRY37.29 billion, followed by industry and trade at TRY24.32 billion, and automotive trade and marketing at TRY13.76 billion. The company's net profit margin shows notable trends over time, reflecting its operational efficiency across diverse sectors in Turkey.
Dogan Sirketler Grubu Holding, a relatively smaller player in the market, has shown impressive earnings growth of 161% over the past year, outpacing the Specialty Retail industry. Despite this growth, its debt to equity ratio has risen from 30.1% to 37.4% over five years. The company is trading at a substantial discount of 73.5% below its estimated fair value and maintains high-quality earnings with sufficient interest coverage. Recent results highlight a significant turnaround with net income reaching TRY 3,291 million compared to TRY 99 million last year for Q2, although future earnings are projected to decline by an average of 26%.
- Click to explore a detailed breakdown of our findings in Dogan Sirketler Grubu Holding's health report.
Gain insights into Dogan Sirketler Grubu Holding's past trends and performance with our Past report.

Specialized Medical (SASE:4019)
Simply Wall St Value Rating: ★★★★★☆
Overview: Specialized Medical Company owns and operates hospitals, clinics, and medical centers in the Kingdom of Saudi Arabia with a market cap of SAR4.06 billion.
Operations: Specialized Medical generates revenue primarily from medical services, which contributed SAR1.28 billion, and from pharmacies, which added SAR296.17 million.
Specialized Medical, a smaller player in healthcare, has shown impressive earnings growth of 84% over the past year, outpacing the industry average. The company reported sales of SAR 401 million for Q2 2026, with net income reaching SAR 45 million. Earnings per share improved to SAR 0.18 from SAR 0.15 last year. Despite a high net debt to equity ratio of 48%, interest payments are well covered by EBIT at a multiple of 6.2x. A recent project award valued at approximately SAR 3.8 billion enhances its portfolio and positions it for future growth in mental health services under a long-term contract with the Saudi Ministry of Health.
- Navigate through the intricacies of Specialized Medical with our comprehensive health report here.
Explore historical data to track Specialized Medical's performance over time in our Past section.

NSD (TSE:9759)
Simply Wall St Value Rating: ★★★★★★
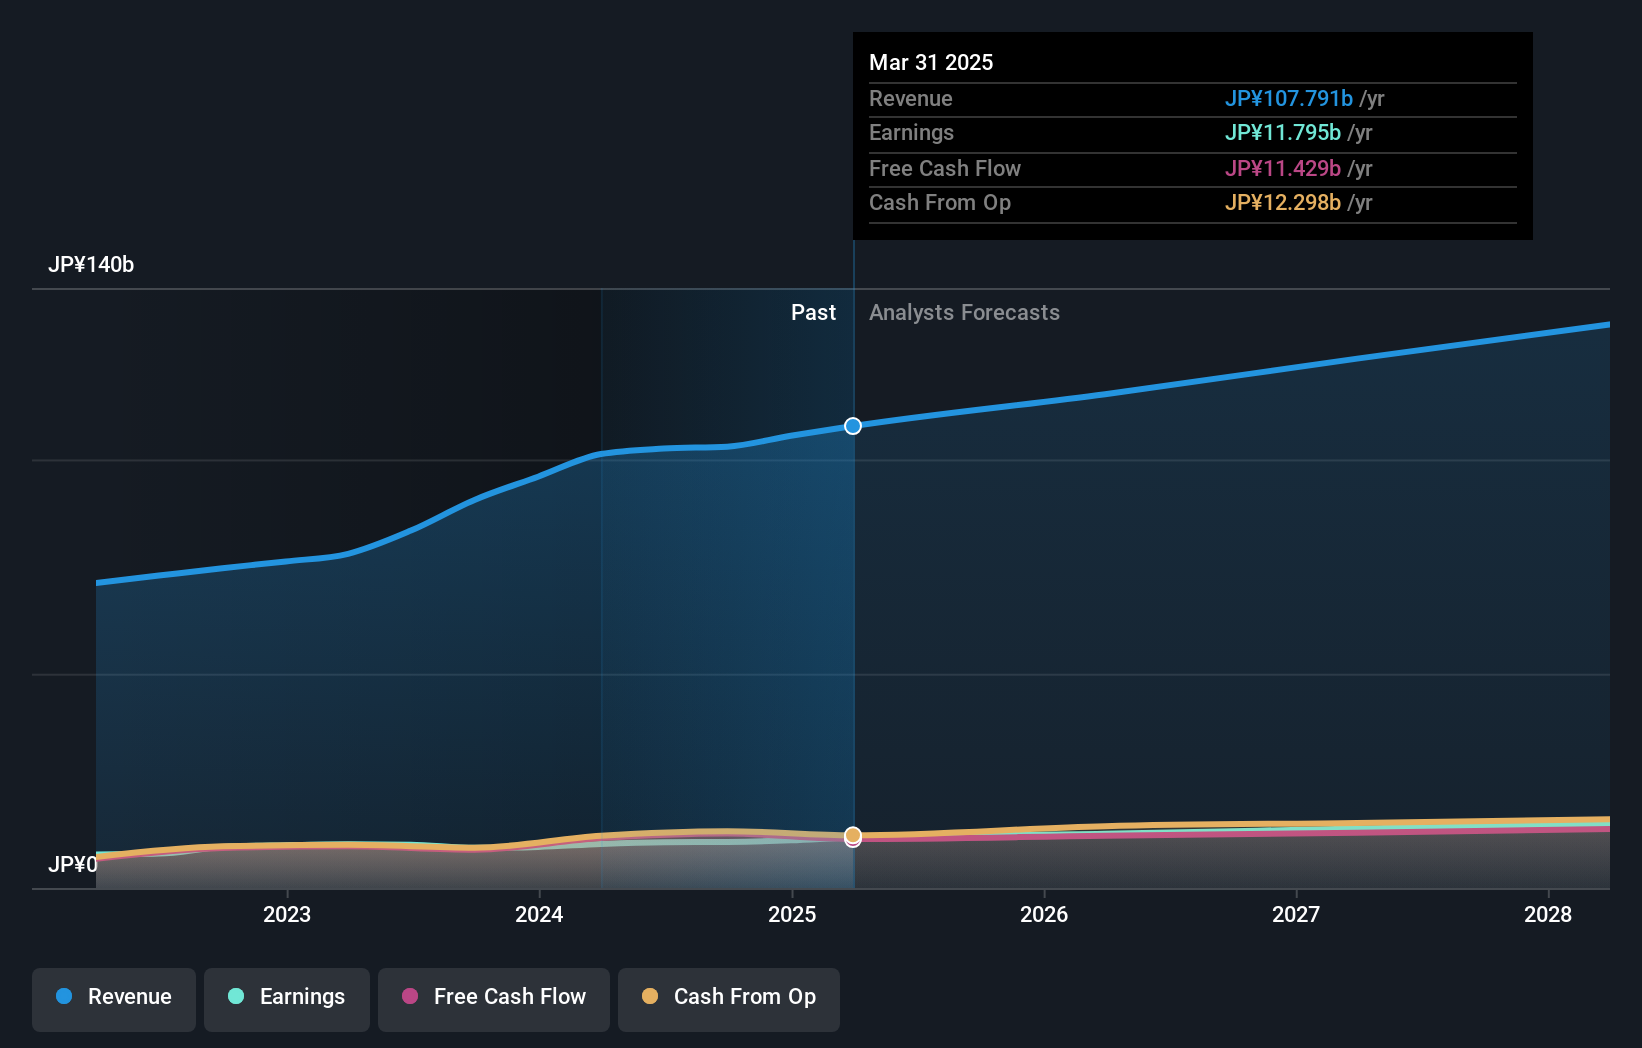
Overview: NSD Co., Ltd. is a company that offers a range of IT solutions in Japan, with a market capitalization of ¥218.73 billion.
Operations: NSD generates revenue primarily through its System Development Business, with the Financial IT segment contributing ¥36.30 billion and the Industrial IT segment adding ¥28.44 billion. The company's Solution Business also plays a significant role, bringing in ¥18.37 billion.
NSD Co., Ltd. showcases a promising profile with its debt-free status and high-quality earnings, making it an attractive player in the IT sector. The company has seen a 12% increase in earnings over the past year, outpacing the industry average of 11.9%. Recent sales figures highlight growth, with August net sales reaching ¥10,510 million compared to ¥9,710 million last year. Additionally, NSD is trading at 21% below its estimated fair value and expects further growth with projected annual earnings expansion of 7%. A recent share buyback of 215,500 shares for ¥558 million underscores management's confidence in its valuation.
Seize The Opportunity
- Investigate our full lineup of 163 Global Undiscovered Gems With Strong Fundamentals right here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com