
September 2026 Global Undervalued Small Caps With Insider Buying
In September 2026, global markets have been navigating a challenging landscape marked by escalating geopolitical tensions and rising oil prices, which have fueled inflation concerns and increased Treasury yields. Amid this backdrop, small-cap stocks have experienced notable volatility, with indices such as the Russell 2000 dropping significantly as investors weigh the impact of these broader economic pressures. In such an environment, identifying potentially undervalued small-cap opportunities requires careful consideration of market dynamics and insider activity that may signal confidence in a company's future prospects.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 34.39% | ★★★★★★ |
| China Aircraft Leasing Group Holdings | 7.3x | 1.0x | 35.69% | ★★★★★☆ |
| Franchise Brands | 27.6x | 2.0x | 46.90% | ★★★★☆☆ |
| Linc | 12.6x | 13.1x | 31.82% | ★★★★☆☆ |
| Sagicor Financial | 7.2x | 0.5x | -85.76% | ★★★★☆☆ |
| Firan Technology Group | 35.0x | 2.6x | 26.34% | ★★★☆☆☆ |
| Eurocell | 22.2x | 0.3x | 48.78% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -208.20% | ★★★☆☆☆ |
| Mattr | 40.1x | 0.9x | 45.62% | ★★★☆☆☆ |
| Hong Fok | 23.7x | 6.8x | 30.16% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
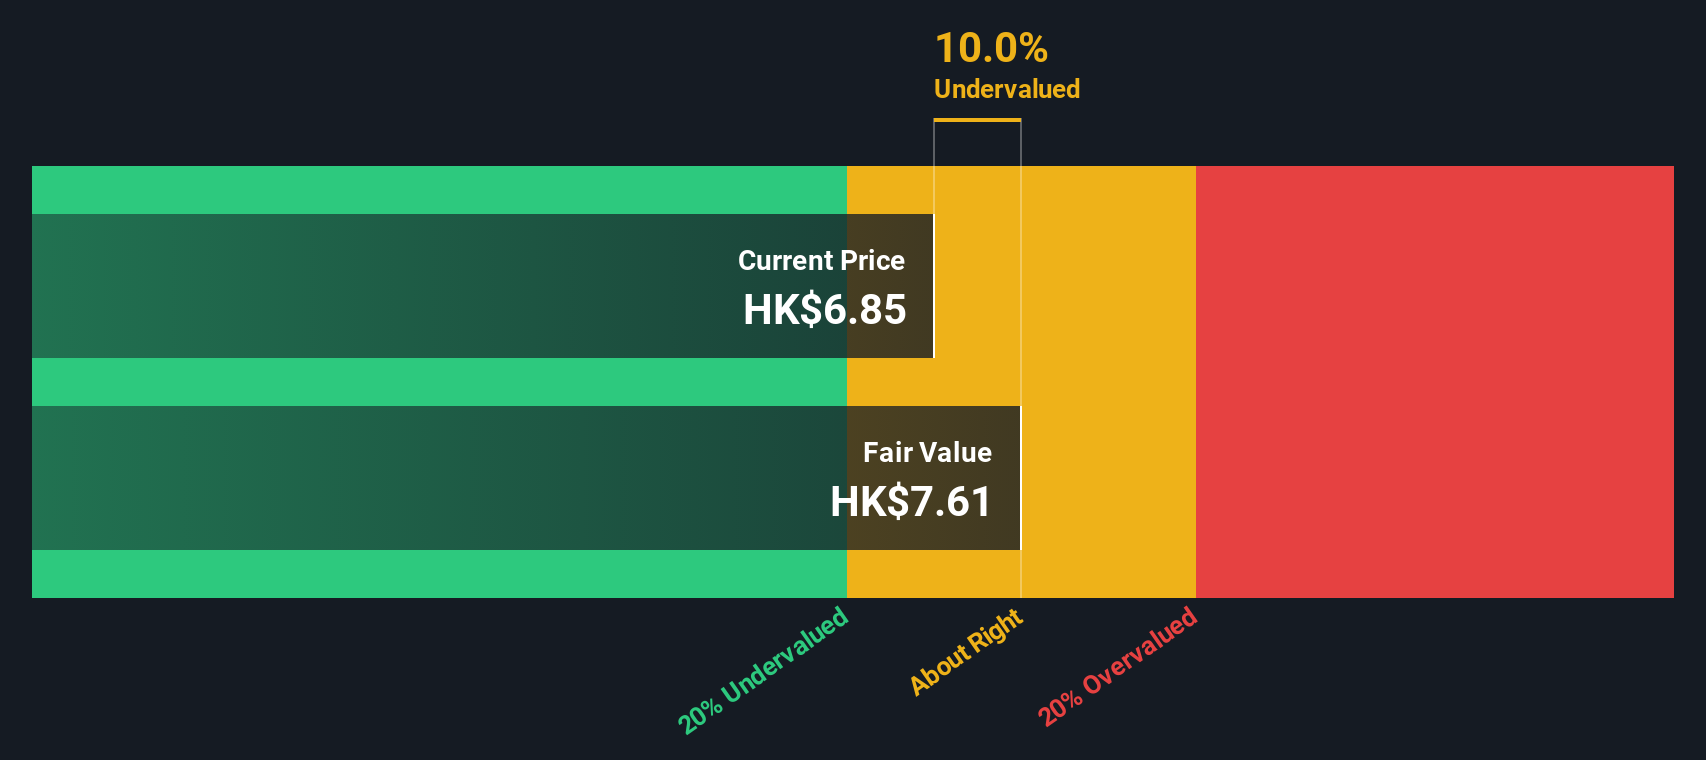
Nissin Foods (SEHK:1475)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Nissin Foods is a company involved in the production and distribution of instant noodles and related food products, with operations primarily in Mainland China and Hong Kong, holding a market capitalization of HK$11.35 billion.
Operations: The company's revenue primarily comes from its operations in Mainland China and Hong Kong and Other Regions. Over recent periods, the gross profit margin has shown an upward trend, reaching 35.46% as of June 30, 2026. Operating expenses are largely influenced by sales and marketing efforts, alongside general and administrative costs.
PE: 19.6x
Nissin Foods, a smaller player in its sector, recently reported half-year sales of HK$2.07 billion, up from HK$2.01 billion the previous year, with net income rising to HK$175 million. Insider confidence is evident as Kiyotaka Ando acquired 204,000 shares valued at approximately HK$1.44 million in recent months. Despite relying entirely on external borrowing for funding—a riskier strategy—earnings are projected to grow by 12.7% annually, suggesting potential upside for investors seeking value opportunities in this space.
- Get an in-depth perspective on Nissin Foods' performance by reading our valuation report here.
Explore historical data to track Nissin Foods' performance over time in our Past section.
Hong Fok (SGX:H30)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Hong Fok is a company engaged in property investment, management, development, and construction with a market capitalization of SGD 1.02 billion.
Operations: The company's primary revenue streams are derived from property investment and property development and construction, with property investment contributing the largest share. Over recent periods, the gross profit margin has shown fluctuations, reaching 71.11% in December 2023 before adjusting to 71.79% by June 2026.
PE: 23.7x
Hong Fok, a small cap company, recently reported half-year sales of S$54.74 million, up from S$46.91 million the previous year. Their net income also rose to S$7.6 million from S$5.42 million, indicating potential growth despite reliance on external borrowing for funding. Insider confidence is evident with recent share purchases by company insiders in 2026, reflecting belief in future prospects amidst high-quality earnings and limited one-off financial impacts.
- Click to explore a detailed breakdown of our findings in Hong Fok's valuation report.
Assess Hong Fok's past performance with our detailed historical performance reports.

Mattr (TSX:MATR)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Mattr specializes in composite and connection technologies, with a focus on innovative solutions, and has a market cap of approximately CA$1.29 billion.
Operations: Mattr generates revenue primarily from its Composite Technologies and Connection Technologies segments, with the latter contributing a higher share. The company's gross profit margin has shown variability, reaching 31.72% in September 2023 before declining to 25.93% by June 2026. Operating expenses are a significant part of the cost structure, with general and administrative expenses being a major component.
PE: 40.1x
Mattr, a smaller company in its sector, has shown promising signs of being undervalued. Recent corporate guidance raised expectations for 2026 earnings following a strong second quarter where revenue hit C$396.19 million, up from C$320.96 million the previous year. Despite high-risk funding reliance and interest payments not well-covered by earnings, insider confidence is evident through share repurchases totaling 653,876 shares for C$7.04 million since June 2025. Earnings are projected to grow annually by nearly 41%, suggesting potential future value despite current financial challenges.

Key Takeaways
- Click this link to deep-dive into the 117 companies within our Undervalued Global Small Caps With Insider Buying screener.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com