
Earnings Forecast Cuts Might Change The Case For Investing In Alaska Air Group (ALK)
- Alaska Air Group recently faced fresh earnings pressure as analysts cut forecasts, with consensus pointing to a sharp year-over-year decline in upcoming EPS.
- The earnings reset highlights how cost pressures and a tougher profit outlook could test Alaska Air Group’s longer-term expansion and integration ambitions.
- We will now assess how Alaska Air Group's investment narrative holds up against the backdrop of sharply reduced earnings expectations and outlook concerns.
Broaden your watchlist beyond Alaska Air Group by scanning a curated set of resilient balance sheet plays using the list of solid balance sheet and fundamentals (23 results).
Alaska Air Group Investment Narrative Recap
For you to own Alaska Air Group, you need to be comfortable with an airline that is still working through losses, higher input costs and a heavy integration agenda. The key near term swing factor is whether unit costs tied to labor, fuel, maintenance and airport real estate can be kept in check while demand in its core West Coast and Hawaii routes remains steady.
The recent reset in earnings expectations raises the bar for that cost discipline, but does not change the core story that execution on fleet modernization, premium seating and technology should matter most over the next few years. The biggest risk right now is that integration and labor pressures keep margins weak for longer than the business can comfortably fund through current cash generation.
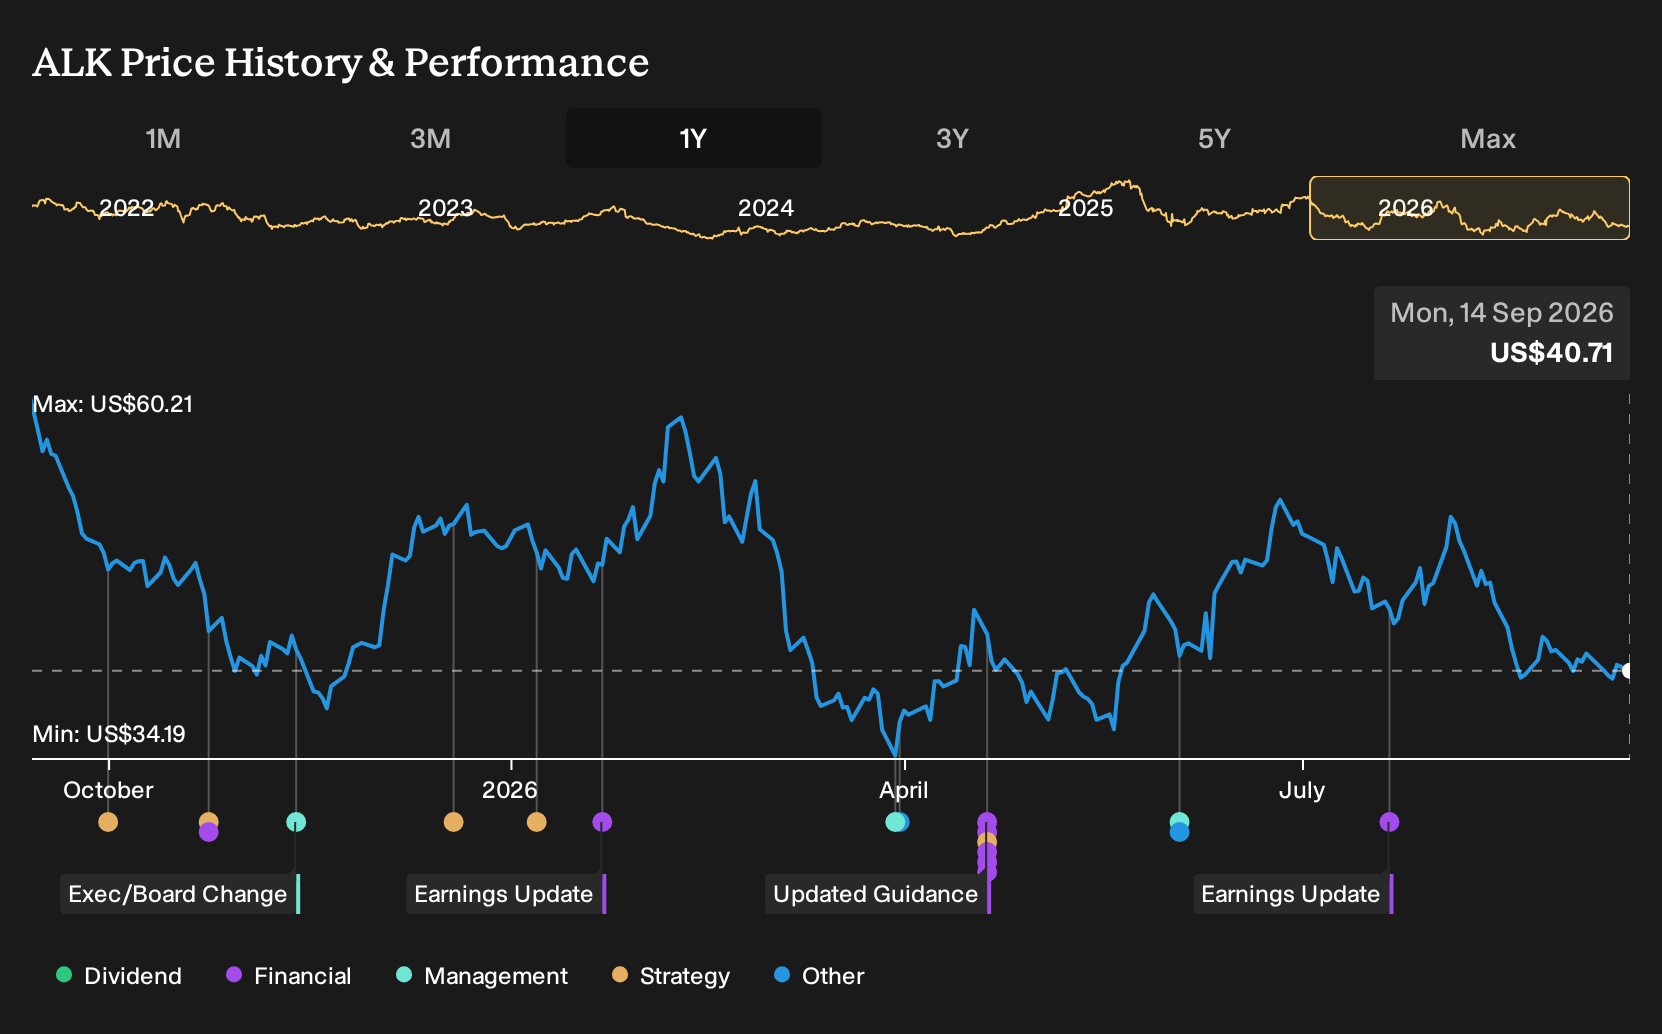
Recent commentary around Alaska Air Group has centered on weaker share performance and a sharply lower near term earnings outlook. That connects directly to concerns already on the table about unit costs, reliance on certain geographies and the time and spend required to integrate Hawaiian Airlines while also upgrading the fleet.
For you as a shareholder, the relevance is straightforward. Any stumble in combining operating certificates, reservation systems or labor structures can keep net income under pressure and slow progress toward profitability targets that analysts currently expect. The more the market focuses on short term EPS volatility, the more execution on these operational milestones becomes the practical catalyst to watch.
Alaska Air Group's narrative projects US$18.5b revenue and US$1.4b earnings by 2029. This implies 7.9% yearly revenue growth and an earnings increase of about US$1.6b from a loss of US$175.0m today.
Uncover why Alaska Air Group's fair value indicates a 46% potential upside to its current price before that valuation gap starts to close.
Exploring Other Perspectives
Some of the lowest Alaska Air Group forecasts lean into demand risk rather than cost control. Those analysts were only looking for revenue of about US$17.9b and earnings of roughly US$1.1b by 2029, which is meaningfully below the consensus path. That more cautious story may shift again once the latest EPS reset is reflected.
Explore 3 other Alaska Air Group fair value estimates, including one that suggests it could be worth just $58.53!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent research.
- A great starting point for your Alaska Air Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alaska Air Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alaska Air Group's overall financial health at a glance.
Looking for more investment ideas beyond Alaska Air Group?
If the Alaska Air Group story has you thinking about portfolio balance, use the Simply Wall St Screener to line up other opportunities that match your risk, income, and quality preferences.
- For investors hunting for stronger fundamentals at reasonable prices, review a curated set of 35 high quality undervalued stocks that may warrant a closer look.
- If capital preservation is high on your list, scan a 11 resilient stocks with low risk scores that score well on resilience and financial strength.
- For those willing to trade liquidity for potential upside, filter through 3 elite penny stocks with strong financials that clear higher bars on balance sheet quality and track record.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com