
Sanmina (SANM) Adds A Board Veteran, Is The Stock Still Cheap?
Sanmina (SANM) has drawn fresh attention after adding long time enterprise technology executive Shanker Trivedi to its board of directors, giving investors a new lens on the stock's governance and sector exposure.
Sanmina’s recent board appointment lands after a volatile run, with the share price down 9.24% over the last day and 21.28% over 90 days, yet still showing a 23.07% year to date share price return and a very large 5 year total shareholder return of 421.11%. This indicates strong long term momentum despite shorter term pressure around governance headlines and legal settlement news.
Scan other manufacturers and tech suppliers reacting to the same AI and data center trends by reviewing our hand picked 60 AI infrastructure stocks alongside Sanmina’s latest boardroom move.
Bulls argue that Sanmina’s AI-linked board refresh and long-run record support a richer multiple. Bears point to recent share price pressure and legal noise. Which story does the valuation actually support?
Most Popular Narrative: 25% Undervalued
Sanmina's most followed valuation storyline puts fair value at $260 per share, compared with the last close of $196.04, which frames the latest board addition against a wider earnings and cash generation debate.
The imminent acquisition of ZT Systems is expected to add $5–6 billion of annual run-rate revenue, positioning Sanmina to double its net revenue within three years and capitalize on explosive growth in data center and AI infrastructure investment. This should provide a multi-year boost to overall revenue and EPS accretion from synergies and integration.
See why 16 investors see Sanmina as 25% undervalued.
Result: Fair Value of $260 (UNDERVALUED)
Still, that story can break if the ZT Systems deal puts a strain on working capital or if any of Sanmina’s largest customers sharply cut orders.
Find out about the key risks to this Sanmina narrative.
Another View On Sanmina’s Valuation
On a simple earnings multiple, Sanmina screens differently to that $260 fair value story. The stock trades on a P/E of 34.1x, which is higher than the US Electronic industry on 28.9x, yet below a fair ratio estimate of 43.1x that the market could migrate toward over time.
That mix of richer pricing than the wider sector but cheaper than the fair ratio highlights both valuation risk if sentiment cools and potential upside if earnings keep supporting a higher multiple. Which side of that trade do you think current boardroom and AI data center momentum supports?
See what the numbers say about this price — find out in our valuation breakdown.
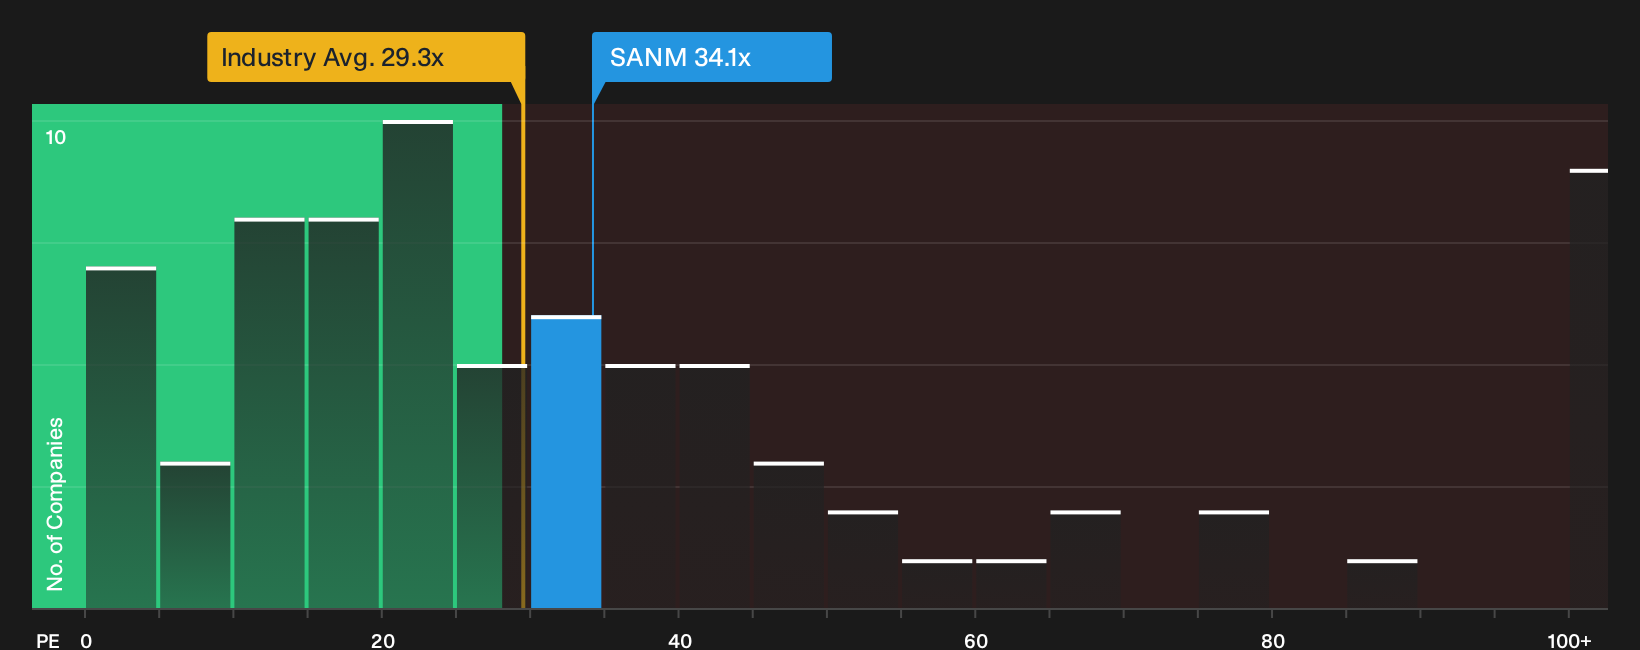
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sanmina for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed about Sanmina after all of that. Act quickly, look through the full picture of risks and rewards, and weigh the 2 key rewards and 2 important warning signs.
Looking for more Sanmina style investment ideas?
If Sanmina has sharpened your focus on where capital might work harder, broaden your search now so you are not leaving better risk reward trade offs unexplored.
- Target potential mispricings early by scanning our 15 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Secure more dependable balance sheets by reviewing the list of solid balance sheet and fundamentals (23 results) that can better withstand sector shocks.
- Lock in a steadier income stream by checking companies in the 6 dividend fortresses that offer higher yields with robust backing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com