
Three Stocks That May Be Trading Below Estimated Value In September 2026
Over the last 7 days, the United States market has experienced a 1.5% drop, although it has risen by 13% over the past year, with earnings projected to grow by 17% annually. In this context of fluctuating performance and optimistic growth expectations, identifying stocks that might be trading below their estimated value can present intriguing opportunities for investors seeking potential gains.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valley National Bancorp (VLY) | $13.84 | $27.10 | 48.9% |
| SouthState Bank (SSB) | $106.11 | $190.74 | 44.4% |
| Provident Financial Services (PFS) | $23.34 | $42.78 | 45.4% |
| Pegasystems (PEGA) | $38.71 | $70.56 | 45.1% |
| Northeast Bank (NBN) | $132.23 | $247.03 | 46.5% |
| Futu Holdings (FUTU) | $111.11 | $210.88 | 47.3% |
| Civista Bancshares (CIVB) | $27.53 | $53.11 | 48.2% |
| Capital Bancorp (CBNK) | $36.47 | $66.81 | 45.4% |
| Autodesk (ADSK) | $228.93 | $414.92 | 44.8% |
| Addus HomeCare (ADUS) | $117.33 | $226.18 | 48.1% |
Here we highlight a subset of our preferred stocks from the screener.
Autodesk (ADSK)
Overview: Autodesk, Inc. provides 3D design, engineering, and entertainment technology solutions globally with a market cap of approximately $44.39 billion.
Operations: The company's revenue is primarily derived from its CAD / CAM Software segment, which generated $7.79 billion.
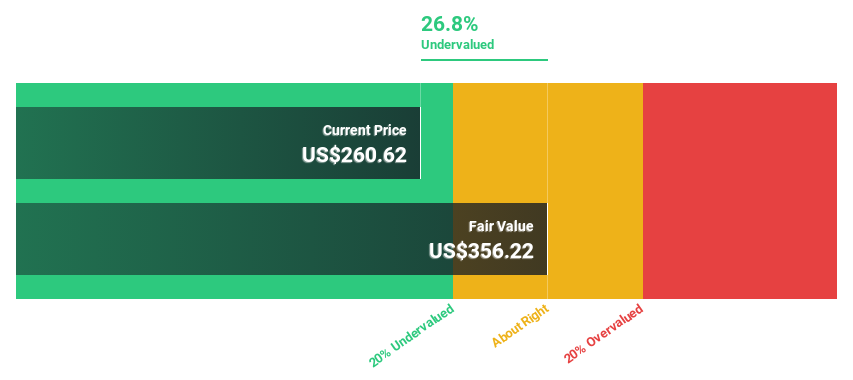
Estimated Discount To Fair Value: 44.8%
Autodesk is trading at 44.8% below its estimated fair value and is undervalued based on discounted cash flow analysis, with a current price of US$228.93 against a future cash flow value of US$414.92. Despite revenue growth forecasts lagging behind the market, Autodesk's earnings are expected to grow annually by 13.32%. Recent strategic partnerships like Workbench 360 integration enhance product offerings, while fixed-income offerings bolster financial flexibility for potential acquisitions and expansions.
- Upon reviewing our latest growth report, Autodesk's projected financial performance appears quite optimistic.
- Navigate through the intricacies of Autodesk with our comprehensive financial health report here.
Pegasystems (PEGA)
Overview: Pegasystems Inc. is a global enterprise software company that develops, markets, licenses, hosts, and supports its products across multiple regions including the Americas, Europe, the Middle East, Africa, and Asia-Pacific with a market cap of approximately $5.96 billion.
Operations: The company's revenue is primarily derived from its Software & Programming segment, which generated $1.74 billion.
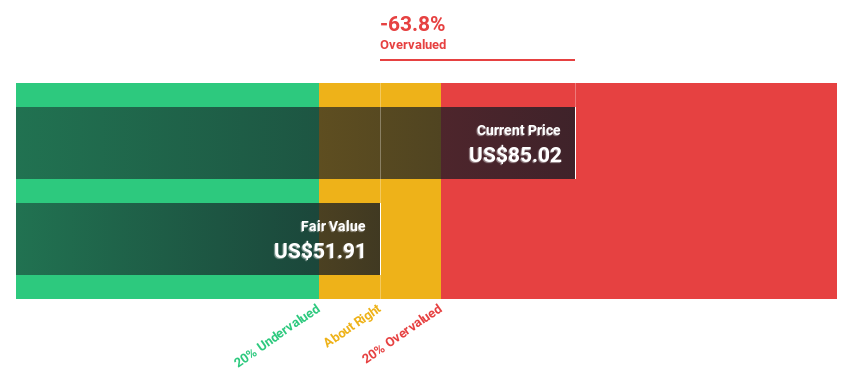
Estimated Discount To Fair Value: 45.1%
Pegasystems is trading at US$38.71, significantly below its estimated future cash flow value of US$70.56, indicating undervaluation based on discounted cash flow analysis. Despite slower revenue growth forecasts compared to the broader market, Pegasystems has achieved a notable 47.2% earnings increase over the past year and maintains strong partnerships, such as with Coforge Limited, enhancing its AI-driven offerings and global market reach while supporting enterprise transformation initiatives.
- According our earnings growth report, there's an indication that Pegasystems might be ready to expand.
- Click here to discover the nuances of Pegasystems with our detailed financial health report.
Teradata (TDC)
Overview: Teradata Corporation, along with its subsidiaries, offers AI and knowledge platforms both in the United States and internationally, with a market cap of approximately $2.59 billion.
Operations: The company's revenue is primarily derived from Product Sales, which account for $1.51 billion, and Consulting Services, contributing $182 million.
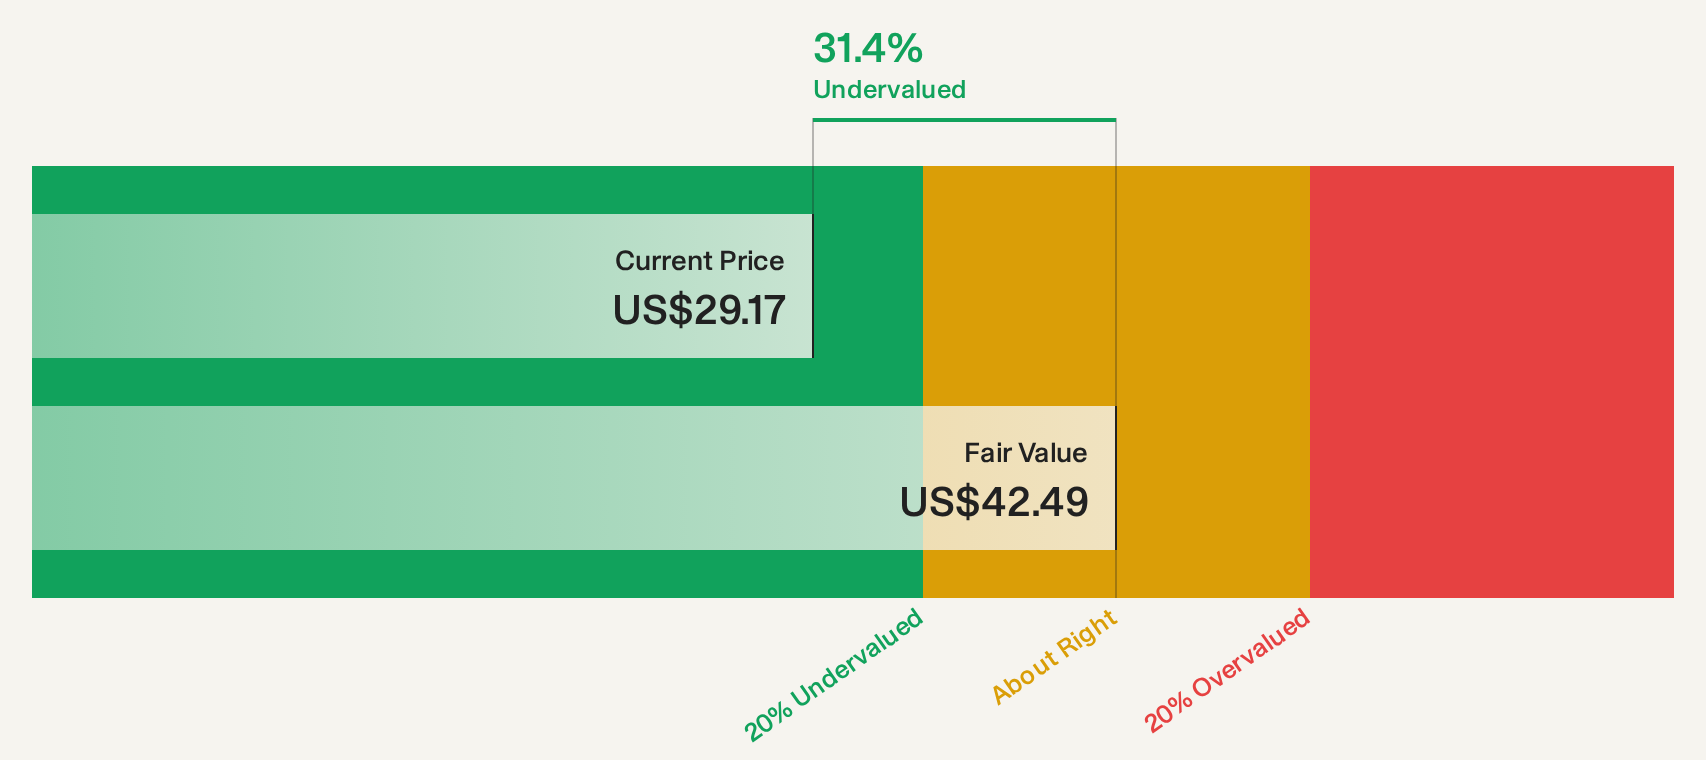
Estimated Discount To Fair Value: 30.6%
Teradata, trading at US$29.37, is undervalued with a future cash flow value of US$42.33. Despite recent earnings growth driven by large one-off items and strategic integrations like the Microsoft OneLake collaboration, its forecasted earnings decline poses challenges. The company has expanded its AI capabilities across platforms without requiring data migration, enhancing operational efficiency for clients. However, revenue growth remains sluggish compared to the market average, impacting long-term valuation prospects.
- Insights from our recent growth report point to a promising forecast for Teradata's business outlook.
- Click here and access our complete balance sheet health report to understand the dynamics of Teradata.
Next Steps
- Gain an insight into the universe of 45 Undervalued US Stocks Based On Cash Flows by clicking here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com