
SharkNinja (SN) Could Be 29% Undervalued After New Product Launches
Why SharkNinja Stock Is Back in Focus After Its New Product Push
SharkNinja (SN) has put fresh products at the center of its story, with the Ninja NeverQuit Cookware and NeverDull Pro Cutlery lines reinforcing its focus on durability, safety, and everyday kitchen use.
These launches, paired with recent recognition in Fast Company’s Innovation by Design Awards for the Shark FacialPro Glow system, give investors new data points on how the business thinks about product design, pricing, and long-term brand positioning.
SharkNinja’s recent cookware and cutlery launches, together with its Fast Company design recognition and upcoming appearance at the Goldman Sachs Global Consumer and Retail Conference, come against a backdrop of mixed short-term moves but strong momentum over longer periods. The share price is at $169.62 after a 1-day share price return of 5.49%, a 30-day share price return that declined 8.36%, a 90-day share price return of 24.46% and a year-to-date share price return of 48.99%. Total shareholder return over 1 year is 48.14% and over 3 years is more than 4x, which points to investors reassessing both growth potential and risk around the brand.
Scan other consumer brands with a similar product-driven story by running through our hand picked 15 high quality undiscovered gems alongside SharkNinja’s latest cookware and cutlery launches.
SharkNinja has already delivered a multi year rerating, and the latest run of product launches and design recognition suggests the story is still evolving. Is most of the upside already captured, or do the current valuation markers argue otherwise?
Most Popular Narrative: 53% Overvalued
SharkNinja’s last close at $169.62 sits well above the $110.73 fair value implied by the most followed narrative, which leans on detailed growth and margin assumptions to make its case.
SharkNinja makes products people genuinely seem to love. My brother-in-law hasn't stopped talking about his Ninja coffee machine. Every gym-goer seems to own a Ninja ice cream maker churning out protein ice cream. And don't get me started on how everyone now owns an air fryer. This is a brand that has quietly embedded itself into daily life and that kind of word-of-mouth loyalty is genuinely hard to manufacture.
See why 8 investors see SharkNinja as 53% overvalued.
According to AshleighG, that affection for the Shark and Ninja labels sits alongside more cautious revenue and margin forecasts, which produce a $110.73 valuation using a 9% discount rate and a 21x future earnings multiple. With the current share price well above that narrative fair value, the view is that the market is already baking in a more optimistic outcome than those assumptions support.
Result: Fair Value of $110.73 (OVERVALUED)
Still, SharkNinja’s story could change quickly if consumer budgets tighten further or if tariffs and trade policies shift in ways that pressure its current economics.
Find out about the key risks to this SharkNinja narrative.
Another View On SharkNinja’s Value
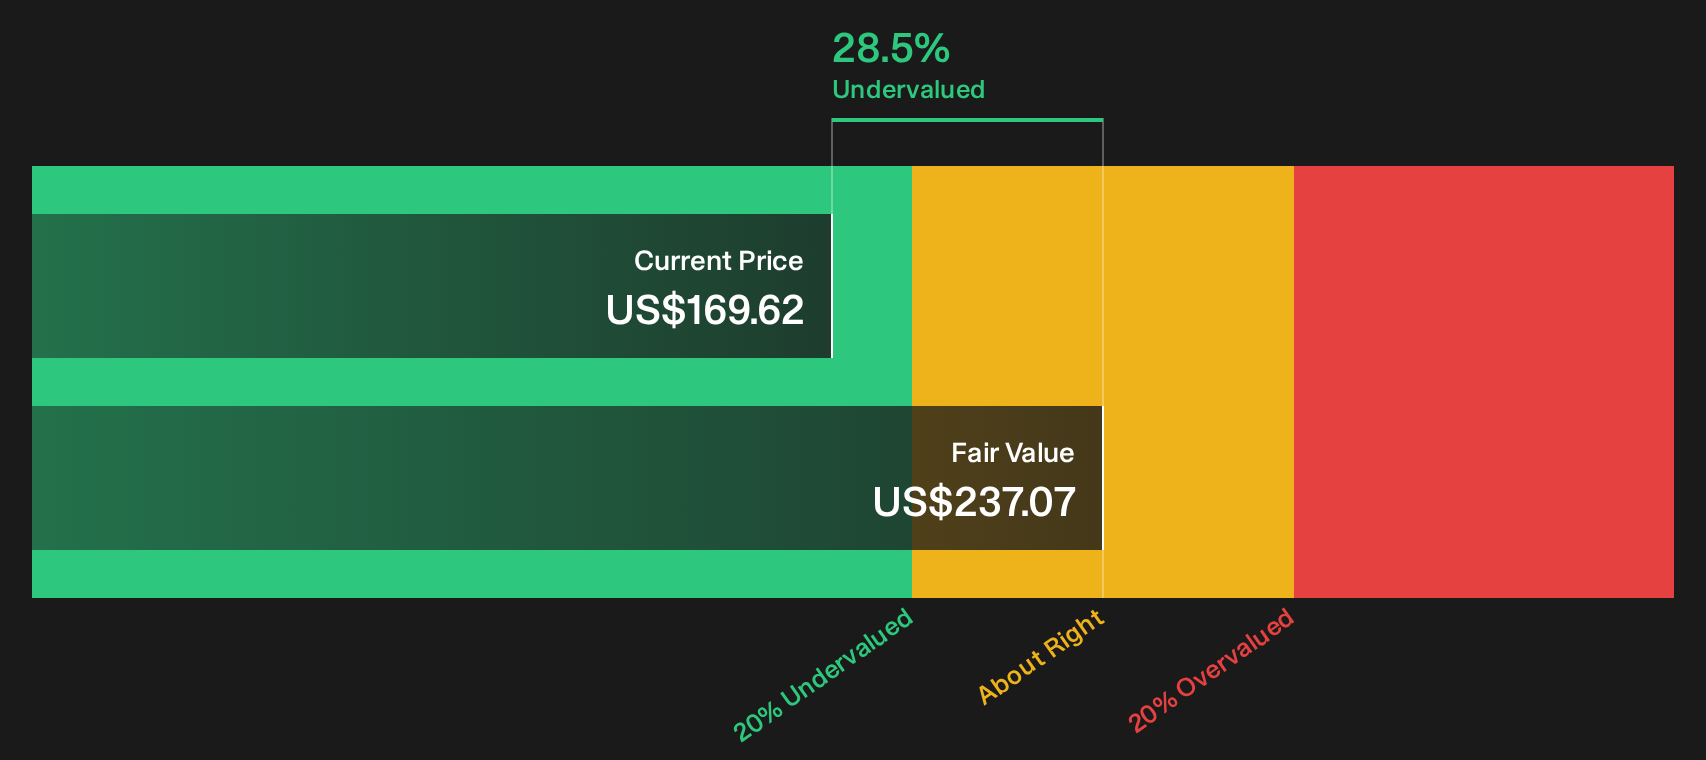
The first narrative focuses on earnings multiples and describes SharkNinja as overvalued at $110.73. Our DCF model presents a different perspective. On that framework, the share price of $169.62 sits around 28.5% below an estimated future cash flow value of $237.07, which indicates potential undervaluation instead. Could the truth lie somewhere between these two yardsticks?
For a closer look at how the cash flow assumptions work and what would need to change for either view to hold, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SharkNinja for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the SharkNinja story so far. If you want to move fast and form your own stance, start with 4 key rewards and 1 important warning sign.
Looking For More SharkNinja Investment Ideas?
If SharkNinja has your attention, do not stop with a single ticker. Use the Simply Wall Street Screener to quickly surface other opportunities that fit your style.
- Target potential mispricing by scanning for resilient businesses trading below their implied worth with the 35 high quality undervalued stocks.
- Prioritize capital protection first and look for steadier candidates using the 11 resilient stocks with low risk scores.
- Focus on underfollowed opportunities and see which quieter stories appear in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com