
Can CAE (TSX:CAE) Re Rate On Its WB Electronics Unmanned Systems Deal?
Why the CAE stock story starts with unmanned systems
CAE (TSX:CAE) just signed a Memorandum of Understanding with WB Electronics to develop training and mission readiness solutions for unmanned and autonomous systems supporting defence customers in Canada, Poland, and allied markets.
The agreement links CAE's simulation and synthetic training expertise with WB Electronics unmanned platforms, creating a framework that could influence how future defence training contracts in this segment are structured and competed.
For investors tracking CAE, the shares trade at around CA$33.80 after a 1-day share price return of 1.78%. However, the 30-day share price return is down 6.76% and the year-to-date share price return has declined 20.38%, which points to fading momentum despite a modestly positive 3-year total shareholder return of 1.38%.
That weaker near term price action sits beside this new unmanned systems partnership with WB Electronics. The market may be weighing it as a potential longer run contract pipeline, while also showing caution around defence spending cycles and execution risks on complex training programs.
Scan how CAE's unmanned systems push compares with other defence-focused contractors by reviewing the hand-picked 38 power grid technology and infrastructure stocks in the sector.
CAE looks like a solid training specialist with a fresh unmanned systems angle, yet the share price has fallen this year. Is that weakness a genuine valuation opportunity, or just a value trap in disguise?
Most Popular Narrative: 24% Undervalued
On the most followed narrative, CAE's fair value sits at about CA$44.25 against a last close of CA$33.80. This frames the stock as materially below that estimate while analysts debate whether the firm's transformation plan and buybacks can close the gap.
Rising defense spending across NATO, the EU, and Canada, combined with global modernization initiatives, is driving strong demand for simulation-based military training. This trend is reflected in CAE's record defense backlog, multi-year contract wins, and opportunity pipeline, suggesting meaningful visibility into growing revenues and margin expansion.
See why 29 investors see CAE as 24% undervalued.
Result: Fair Value of CA$44.25 (UNDERVALUED)
Still, CAE’s high net debt of about CA$3.2b and earnings pressure from softer civil training demand could quickly undermine the upbeat transformation narrative.
Find out about the key risks to this CAE narrative.
Another view on CAE valuation
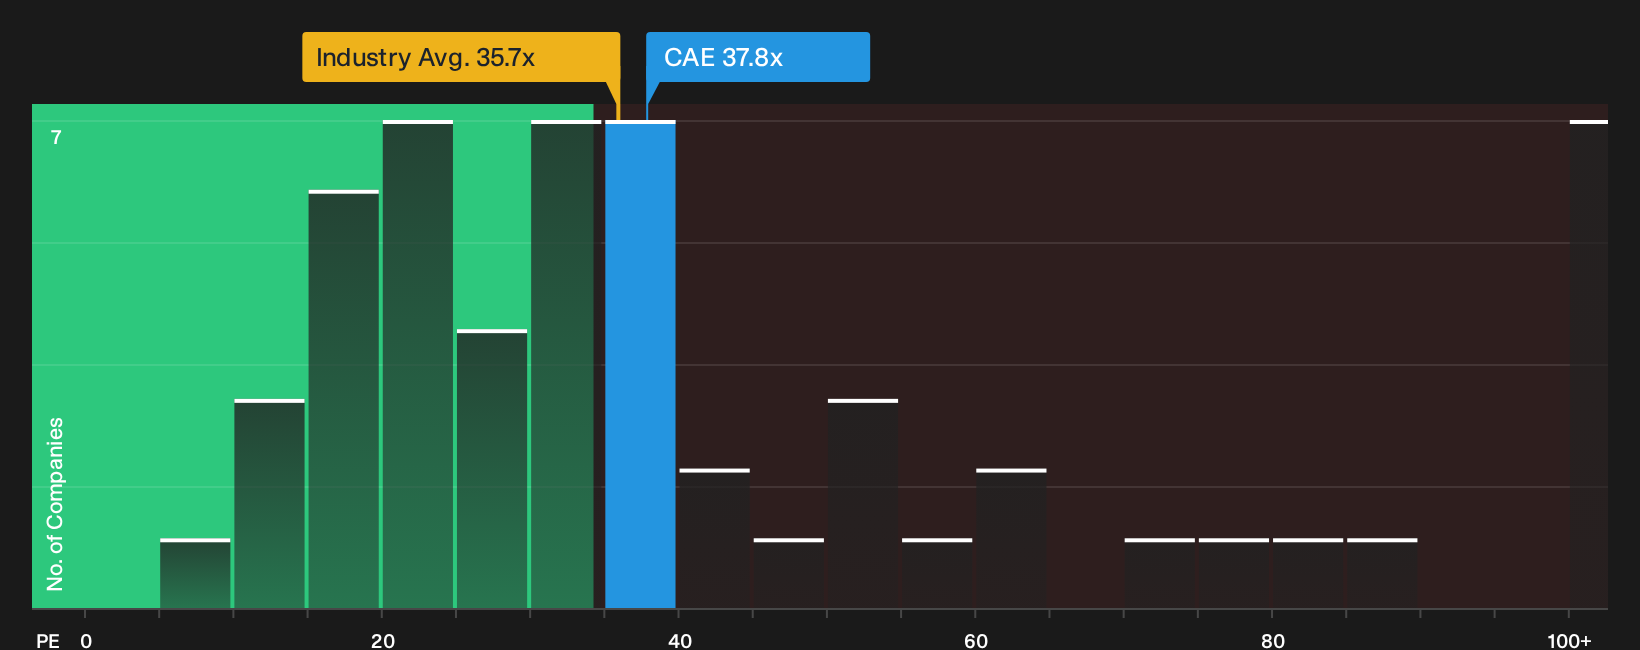
On price alone, CAE looks cheap relative to an estimated fair value of about CA$44.25, with the shares trading at roughly a 23% discount. The earnings multiple tells a different story. The stock trades on a P/E of 37.8x, which is higher than peers at 34.5x and also above a fair ratio of 30.4x that the market could gravitate toward over time.
That gap points to real valuation risk if sentiment shifts. Investors are effectively paying more per dollar of earnings than both the sector and the fair ratio suggest, even as the share price screens as undervalued on other models. Which signal do you think deserves more weight right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a simple mismatch between CAE's price and its story? Act while the data is fresh and weigh both the concerns and the potential upside by reviewing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond CAE?
If CAE has sharpened your focus on pricing and risk, do not stop here. Broader idea hunting can reveal opportunities that fit your exact style.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (7 results).
- Hunt for quality at a discount by working through the 3 high quality undervalued stocks before the crowd catches on.
- Spot future standouts early by reviewing the 9 high quality undiscovered gems while they are still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com