
Learn Why The Bull Case For Sumitomo Forestry (TSE:1911) Could Change Following Subordinated Bond Issuance
- Sumitomo Forestry completed three subordinated, unsecured fixed to floating rate note offerings in September 2026, raising ¥243.5 billion across variable rate issues maturing in 2061, 2063 and 2066, each priced at 100% and structured as callable corporate bonds.
- The long dated, subordinated structure signals a deliberate reshaping of Sumitomo Forestry’s capital stack, with higher risk funding used to support balance sheet flexibility without immediately tapping common equity.
- Next, the focus shifts to how Sumitomo Forestry’s large subordinated note issuance might reshape its investment narrative and risk reward profile.
What Is Sumitomo Forestry's Investment Narrative?
To own Sumitomo Forestry, you need to buy into a simple idea. A global wood, housing, and construction platform can turn steady demand for homes and materials into cash generation over time, even if the share price is currently under pressure. The group already earns most of its revenue from the United States and Japan, so the story hinges on execution in housing, construction quality, and disciplined project selection rather than headline growth alone.
The recent ¥243.5b of long dated subordinated notes sits right in the middle of that. This is higher risk funding that can support capital intensive housing and real estate projects while leaving common equity untouched. It could also cushion short term earnings volatility if projects get choppy, although net profit margins have already come down and debt is not well covered by operating cash flow, so investors still need to watch how management allocates every yen from here.
Even so, there is one aspect of Sumitomo Forestry's funding mix that becomes harder to ignore once you look at ...
There's only one way to know the right time to buy, sell or hold Sumitomo Forestry. Head to Simply Wall St's company report for the latest analysis of Sumitomo Forestry's Fair Value.
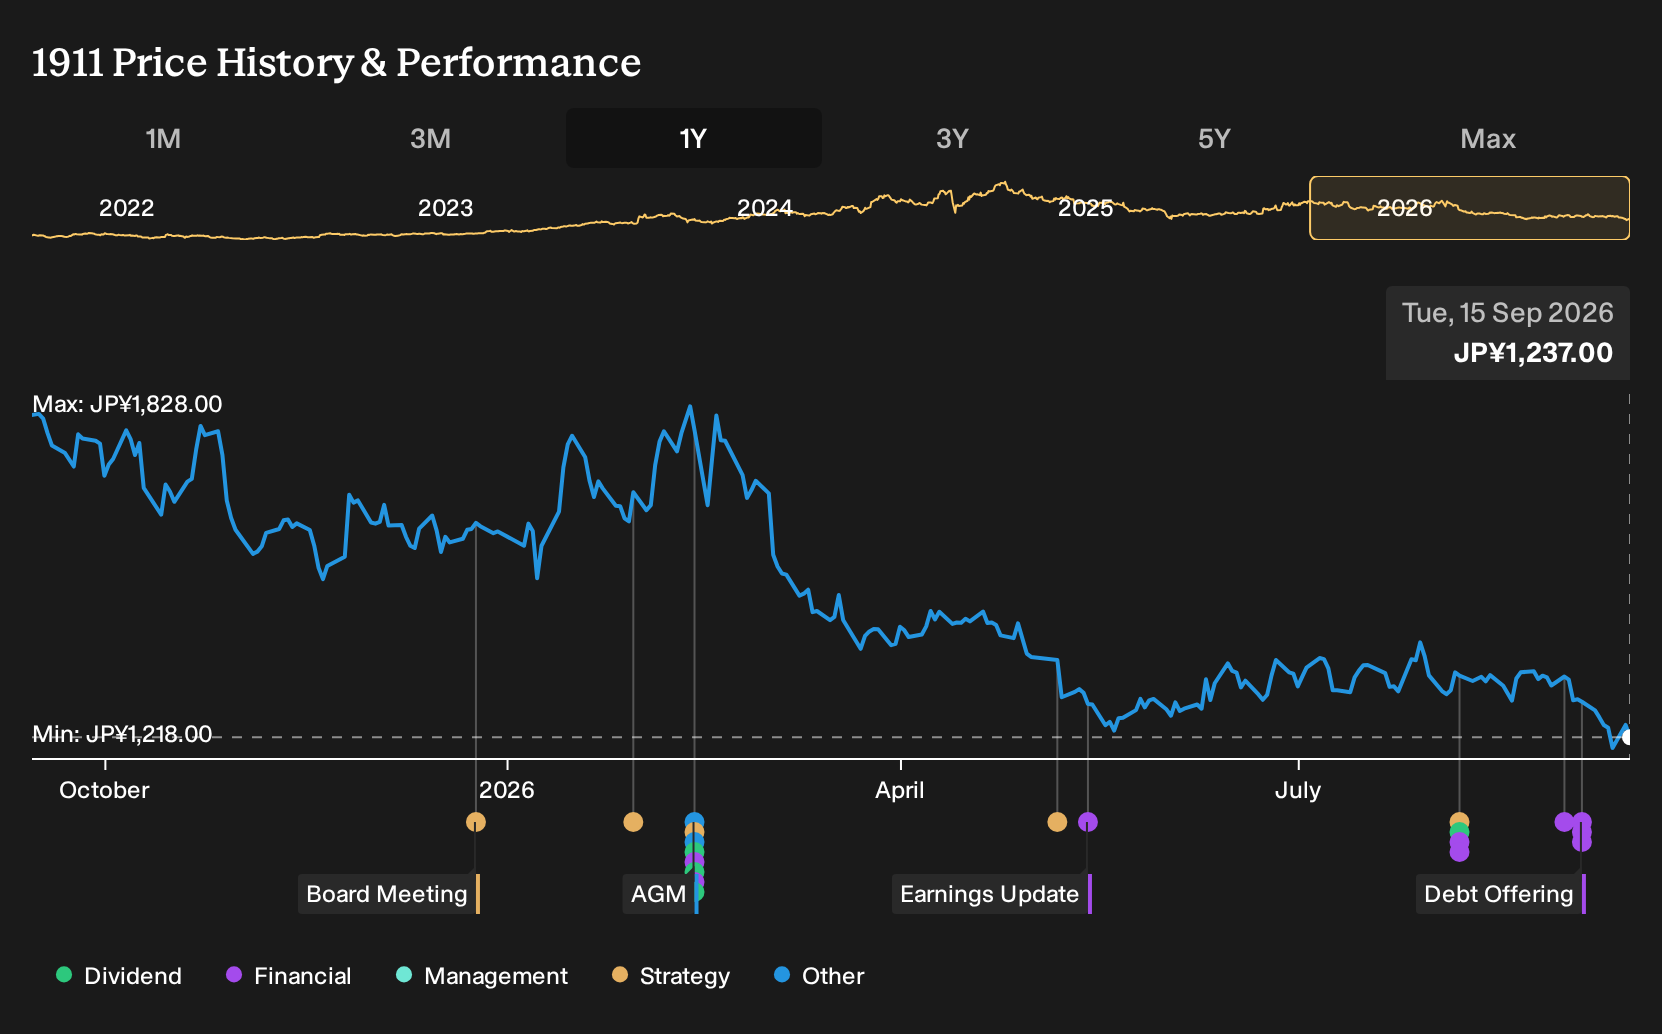
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range, from ¥178.53 per share to ¥1,634. That spread shows how far apart retail views on Sumitomo Forestry can be. These opinions predate the ¥243.5b subordinated note issues, so you should weigh them against fresh balance sheet information and alternative viewpoints.
Explore another Sumitomo Forestry fair value estimate, including one that suggests up to 32% potential upside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sumitomo Forestry research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sumitomo Forestry. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sumitomo Forestry's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sumitomo Forestry?
If this Sumitomo Forestry review has sharpened your thinking, you can use that same lens across a broader watchlist. The Simply Wall St Screener can help you quickly filter for businesses that match your preferences on value, income, balance sheet strength, or risk profile.
- If you care most about price paid versus quality received, start with 18 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- For investors who prefer to get paid while they wait, focus on income opportunities through 17 dividend fortresses that aim to pair higher yields with balance sheet support.
- If capital protection is front of mind, narrow your search to 12 resilient stocks with low risk scores that score well on financial resilience and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com