
How Leadership Changes At Crown Castle (CCI) Have Changed Its Investment Story
- Crown Castle announced that long-serving finance chief Sunit Patel will retire as EVP and CFO in March 2027. Current EVP and Chief Commercial Officer Kris Hinson will step into the CFO role, while COO Cathy Piche will depart after a transition period ending in February 2027.
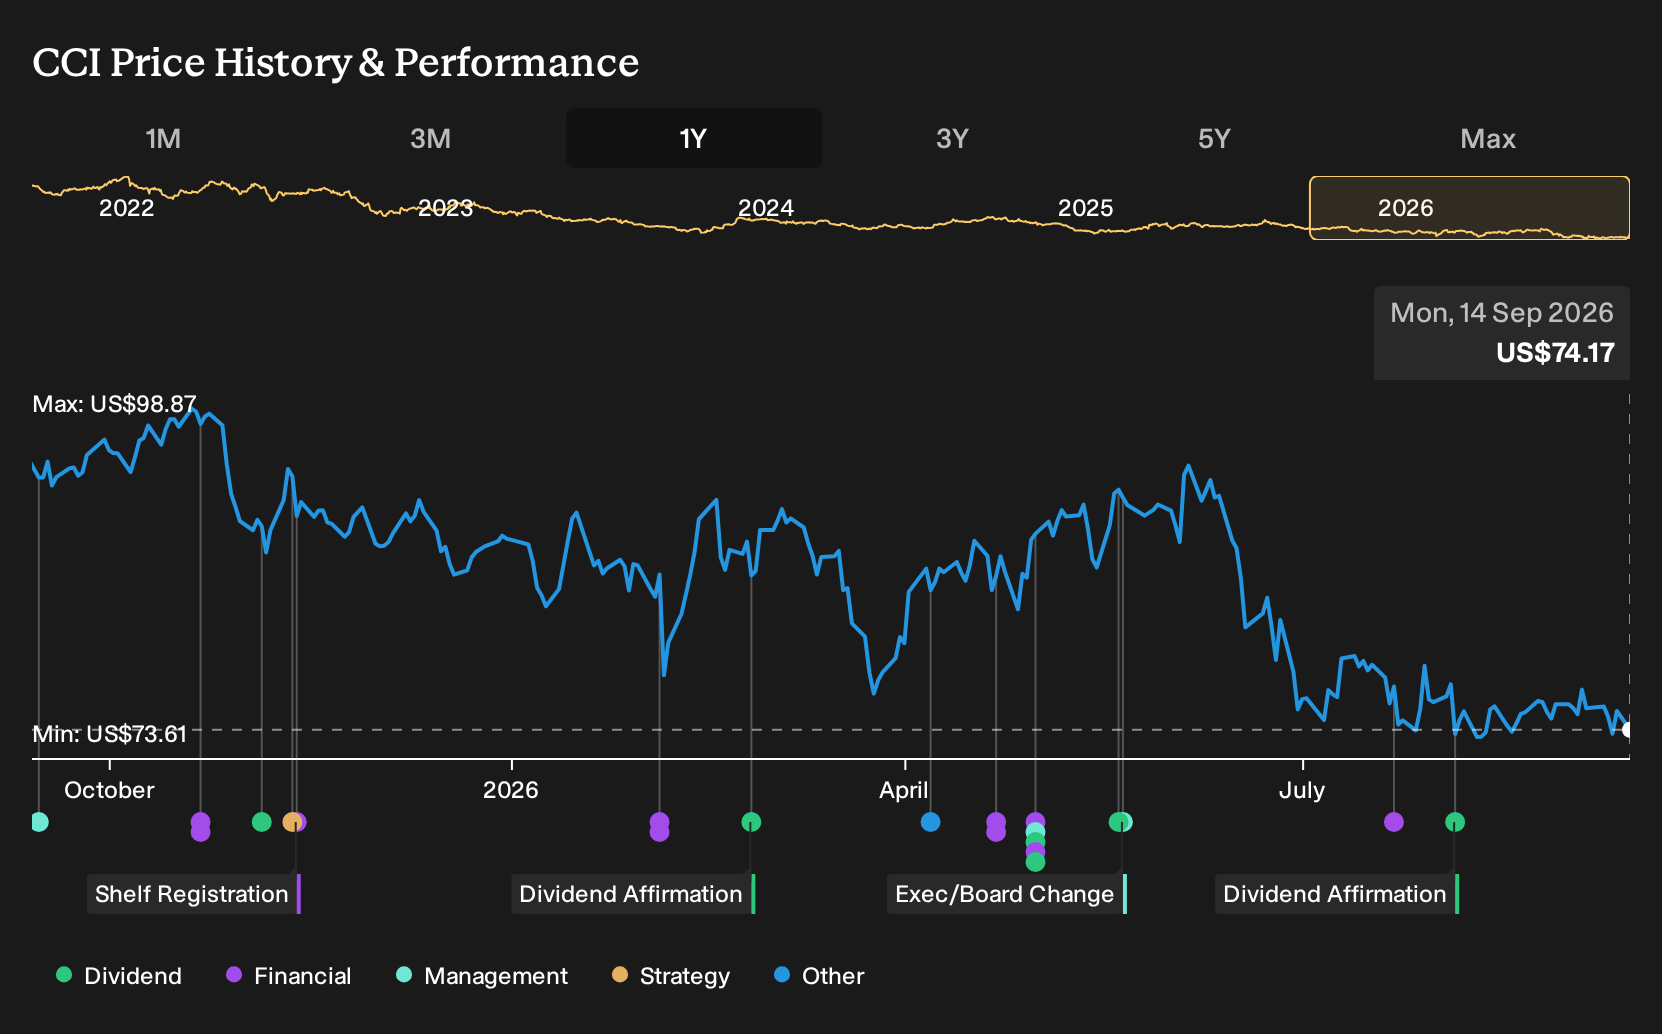
- The leadership reshuffle comes as Crown Castle prepares to sell its fiber segment and faces questions about a high dividend payout ratio alongside pressure on revenue, EPS and EBITDA.
- Next, the focus turns to how Crown Castle's investment narrative holds up as leadership turnover coincides with a fiber exit and dividend strain.
Crown Castle Investment Narrative Recap
Crown Castle is now a pure tower story that still has to earn its keep. To be comfortable as a shareholder, you need to believe the tower portfolio can support steady lease demand, while the move away from fiber and a high dividend payout are managed without stressing the balance sheet. The biggest near term swing factor remains the fiber divestiture and what it does to cash flow and capital allocation.
The leadership changes do not fundamentally alter that equation, although they add execution risk around timing, debt management and dividend coverage. The key business risk still sits around funding a 5% plus yield when interest costs are tight and revenue, EPS and EBITDA trends are under pressure.
The most relevant update for this story is the recent dividend announcement of US$1.06 per share, alongside the plan to exit the fiber segment in the first half of 2026. That decision crystallises the shift to a stand alone U.S. tower operator while keeping a sizable cash distribution in place despite a high payout ratio.
For you as an investor, this combination puts execution under the microscope. Crown Castle has to close the fiber sale, manage regulatory steps, address negative trends in revenue, EPS and EBITDA, and still keep interest and dividend obligations covered. The incoming CFO, Kris Hinson, will be judged quickly on how cleanly those moving parts are handled.
Crown Castle's current analyst narrative points to US$4.3b in revenue and US$1.4b in earnings by 2029. This is based on 1.3% yearly revenue growth and an earnings increase of about US$300m from US$1.1b today.
Uncover how Crown Castle's fair value indicates a 30% potential upside to its current price before the market closes.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between US$96.12 and US$114.20, so you are seeing a tight but still meaningful spread in opinion on Crown Castle. Those views do not reflect the CFO transition, fiber sale plan, dividend reset, or execution risk. Treat them as one input among many and explore how other investors frame these moving parts.
Explore 2 other Crown Castle fair value estimates, including one that suggests it could be worth just $96.12!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Crown Castle research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Crown Castle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crown Castle's overall financial health at a glance.
Looking For More Ideas Beyond Crown Castle?
Once you have a handle on Crown Castle, it often helps to compare it with other opportunities that better match your risk tolerance, income needs, and balance sheet preferences. The Simply Wall St Screener can surface a range of alternatives in a few minutes so you can see where Crown Castle sits in the broader market.
- If you prefer stocks where price volatility and risk scores are more contained and want a quick way to filter for that profile, start with a curated 11 resilient stocks with low risk scores that aims to keep surprises to a minimum.
- If long term value and quality matter most to you and you want businesses with stronger fundamentals than their current prices imply, scan through a targeted 35 high quality undervalued stocks that focuses on both cash flows and balance sheet strength.
- For investors who care most about dependable income and want yields that clear the 5% mark while still keeping an eye on stability, review a focused 6 dividend fortresses that screens for higher payout opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com