
Is eBay Stock Outperforming the Dow?
eBay Inc. (EBAY), headquartered in San Jose, California, operates marketplace platforms that connect buyers and sellers. With a market cap of $48.5 billion, the company’s marketplace platform includes its online marketplace at ebay.com, off-platform businesses, and the eBay suite of mobile apps, focused on buying and selling electronics, cars, clothes, and collectibles.
Companies worth $10 billion or more are generally described as “large-cap stocks,” and EBAY perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the internet retail industry. EBAY maintains a strong competitive advantage through its global two-sided network effect and asset-light marketplace model, which generates robust cash flow without inventory risk. It dominates specialized, non-standardized categories where tailored trust tools create high entry barriers for competitors.
Despite its notable strength, EBAY slipped 8.6% from its 52-week high of $119.31, achieved on May 20. Over the past three months, EBAY stock has declined marginally, underperforming the Dow Jones Industrials Average’s ($DOWI) 2.4% gains during the same time frame.
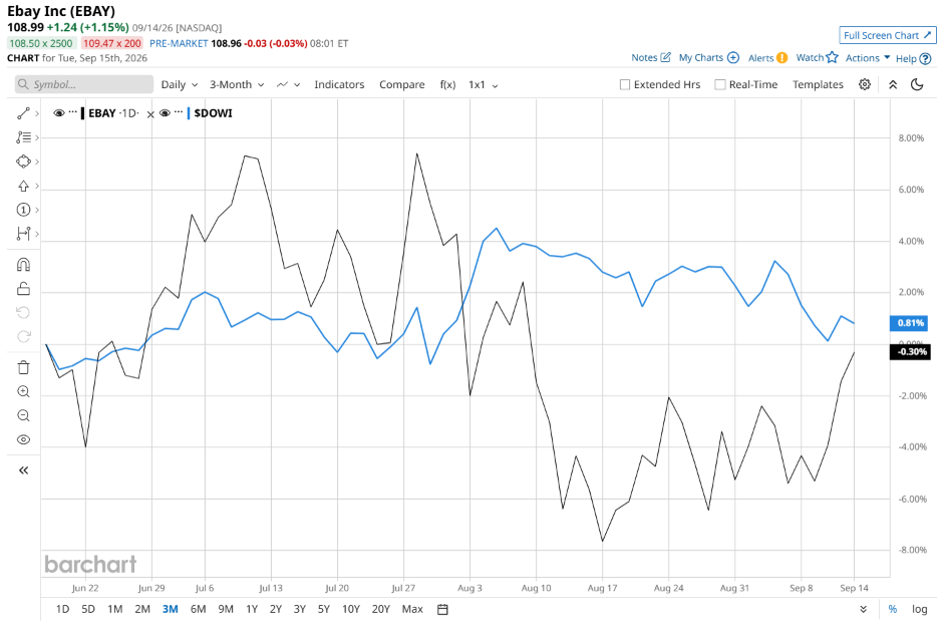
Shares of EBAY have rose 25.1% on a YTD basis and climbed 20.6% over the past 52 weeks, outperforming DOWI’s YTD gains of 9.1% and 14.4% returns over the same time frame.
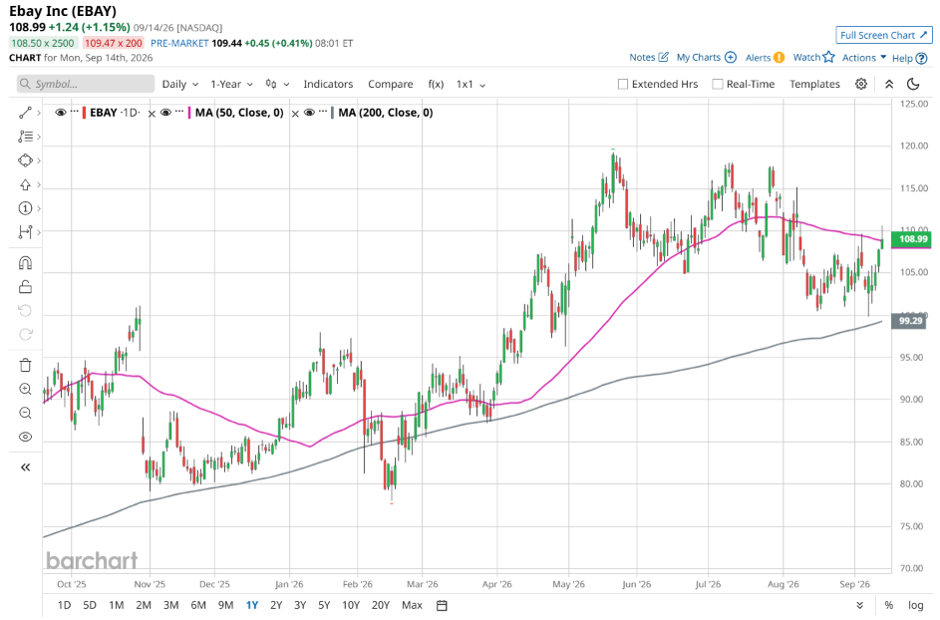
To confirm the bullish trend, EBAY has been trading above its 200-day moving average over the past year, with slight fluctuations. However, the stock has been trading below its 50-day moving average since early August, with minor fluctuations.
EBAY has outperformed due to accelerating GMV growth, strong demand for secondhand goods, high-margin ad expansion, and aggressive share buybacks. Supported by AI listing tools and key growth categories like collectibles and fashion, steady earnings beats and capital returns have continued to boost investor confidence.
On Aug. 5, EBAY shares closed up by 1.4% after reporting its Q2 results. Its adjusted EPS of $1.60 surpassed Wall Street expectations of $1.51. The company’s revenue was $3.1 billion, exceeding Wall Street forecasts of $3 billion. For Q3, EBAY expects its adjusted EPS to range from $1.36 to $1.42, and revenue in the range of $3.07 billion to $3.12 billion.
In the competitive arena of internet retail, Etsy, Inc. (ETSY) has taken the lead over the stock, with a 38.6% uptick on a YTD basis and 32.9% gains over the past 52 weeks.
Wall Street analysts are reasonably bullish on EBAY’s prospects. The stock has a consensus “Moderate Buy” rating from the 32 analysts covering it, and the mean price target of $117.37 suggests a potential upside of 7.7% from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.