
Enpro (NPO) Pulls Back Despite Earnings Strength, Is It Priced For Perfection?
Enpro (NPO) has drawn fresh attention after a stretch of share price weakness, with the stock down over the past week, month, and past 3 months despite positive recent earnings metrics.
Short term momentum has clearly faded, with the share price down 5.51% over the past day and 20.73% over 3 months. Even so, Enpro still shows a 29.53% year to date share price return and a 5 year total shareholder return of 264.65%.
Scan how Enpro compares with other industrials under pressure by reviewing the hand picked 11 resilient stocks with low risk scores that have held up better through recent swings.
Bulls will point to Enpro’s recent earnings strength and large multi year shareholder gains, while bears will focus on the sharp pullback. The key question is which side the current valuation markers appear to support next.
Most Popular Narrative: 27% Undervalued
Compared with Enpro’s last close at $283.94, the most followed valuation narrative points to a fair value of $389.50, which implies a sizeable gap that hinges on execution in its higher tech operations.
Increased investments in capacity expansion, technology differentiation, and market reach, especially in areas like aerospace, sustainable power generation, and compositional analysis, are positioning Enpro to capitalize on the rising demand for automation, digitalization, and advanced engineered solutions, supporting sustained revenue growth.
See why 2 investors see Enpro as 27% undervalued.
Result: Fair Value of $389.50 (UNDERVALUED)
Still, the Enpro story can break if cyclical demand in commercial vehicles and semiconductor equipment stays weak, or if expansion projects run over budget and schedule.
Find out about the key risks to this Enpro narrative.
Another View on Enpro’s Valuation
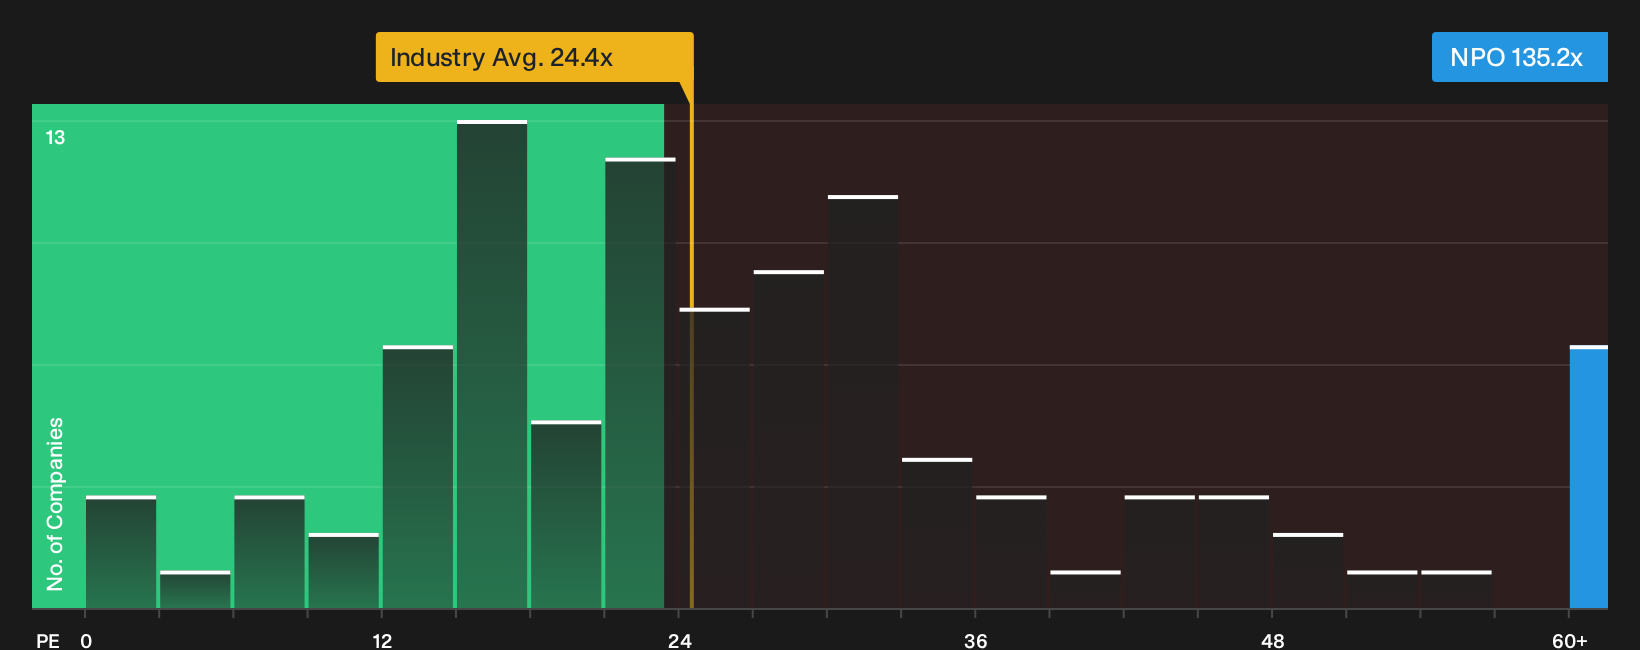
The first narrative leans heavily on future earnings power, yet today Enpro trades on a P/E of 135.2x. That is far above the Machinery industry on 24.7x and its own fair ratio of 52.2x, which implies meaningful valuation risk if sentiment or forecasts cool.
This leaves a simple question for investors weighing Enpro now: Is this a case of quality being priced for perfection, or just a temporary premium before fundamentals catch up, as suggested in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Enpro’s recent surge and pullback make this a judgment call, so move quickly, review the numbers, and weigh both the concerns and the upside by checking the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Enpro?
Consider widening your watchlist and comparing your thesis on Enpro with other opportunities using Simply Wall Street’s screener.
- Target resilience by reviewing a curated 11 resilient stocks with low risk scores that may better withstand sharp swings when markets turn choppy.
- Chase quality at a sensible entry point by checking a focused 35 high quality undervalued stocks that filters for strong fundamentals at restrained prices.
- Build a cash flow focused watchlist by scanning a hand picked 6 dividend fortresses that prioritises higher yields alongside business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com