
ATI (ATI) Shares Dropped, So What Is Driving Attention Now?
ATI (ATI) comes back into focus as CEO Kim Fields heads to the Morgan Stanley 14th Annual Laguna Conference on September 17, 2026, for a webcast fireside chat on aerospace opportunities.
Recent trading tells a mixed story for ATI. The share price has retreated sharply in the short term, with a 1 day move down 5.34% and a 30 day share price return down 17.65%. However, the year to date share price return is up 57.84% and the 5 year total shareholder return is more than 10x, which points to strong long term momentum despite the current pullback.
Compare ATI's sharp pullback with other aerospace exposed metals and specialty materials players by scanning our hand picked list of 35 high quality undervalued stocks.
ATI looks like a powerful aerospace supplier on the business side, yet the stock has just given back a chunk of its recent gains. Is that long run success now fairly reflected in the current price?
Most Popular Narrative: 6% Undervalued
ATI closed at $188.15, while the most followed narrative pegs fair value at $200.33, so the recent sell off meets a view of modest undervaluation built on long term contract and margin assumptions.
Recent long-term contract expansions with both Boeing and Airbus, including new titanium alloy sheet supply and broader product offerings, lock in higher volumes and minimums, expand ATI's share, and feature inflation pass-through and attractive pricing. These factors directly support reliable, higher-margin revenue growth and a structurally improved earnings base through the decade.
See why 18 investors see ATI as 6% undervalued.
Result: Fair Value of $200.33 (UNDERVALUED)
Still, ATI's reliance on a small group of aerospace customers, along with its ongoing heavy capital spending, could quickly challenge that undervalued story if either stumbles.
Find out about the key risks to this ATI narrative.
Another View on ATI's Valuation
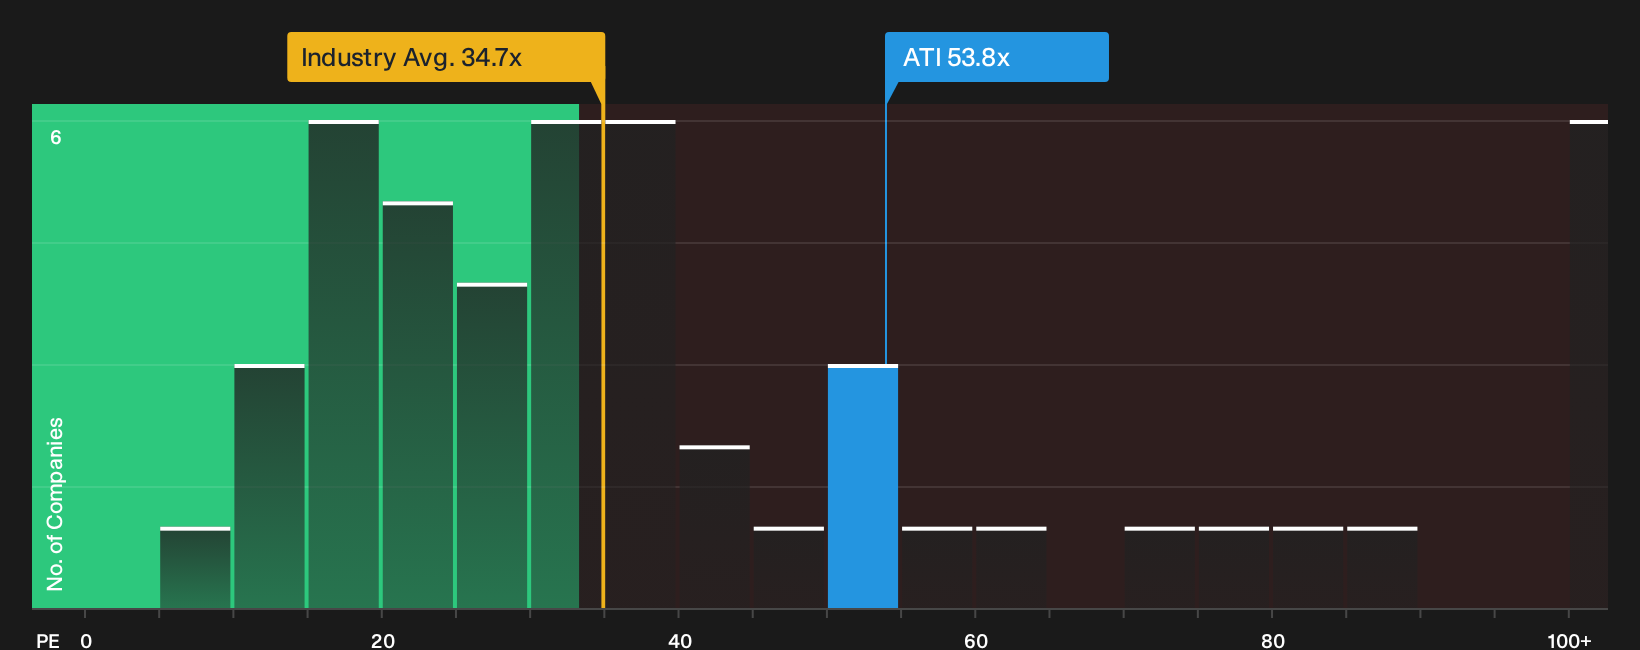
ATI screens very differently when you look at simple pricing metrics. The stock trades on a P/E of 53.8x, which is well above the US Aerospace & Defense sector on 34.7x and also far ahead of its own fair ratio of 32.2x. Against its peer set on 69.3x, ATI looks cheaper, yet the gap to that fair ratio suggests meaningful valuation risk if sentiment cools and the market pushes its multiple closer to that lower level instead. Which reference point do you trust most when you think about your own margin of safety?
For a closer read on what this richer multiple could mean for upside and downside risk, take a look at our valuation breakdown, including the fair ratio context, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by ATI's strong long term share price record and the valuation questions raised here, you can move quickly and weigh the trade off for yourself by reviewing the 3 key rewards and 1 important warning sign.
Looking for more ATI investment ideas?
If ATI has your attention, do not stop here. Broaden your watchlist using focused screens that surface different types of opportunities across the market.
- Target stronger balance sheets by scanning companies that pass rigorous debt and liquidity filters in the list of solid balance sheet and fundamentals (23 results).
- Spot potential mispricing by reviewing companies that combine quality fundamentals with appealing valuations through the 15 high quality undiscovered gems.
- Prioritise resilience by checking businesses that score well on stability and downside protection in the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com