
Is Innovent Biologics (SEHK:1801) Fairly Valued On LP 003 China BLA Progress?
The National Medical Products Administration has accepted LongBio Pharma’s Biologics License Application for LP-003, supported by Innovent Biologics (SEHK:1801) subsidiary Altruist Biologics, marking China’s first anti-IgE BLA for seasonal allergic rhinitis.
For investors tracking Innovent Biologics, the latest regulatory milestone lands after a mixed stretch in the market, with the share price slipping 1.9% over the last session and 5.2% across the week, yet recording a 26.9% 90 day share price return and a 140.2% three year total shareholder return that point to stronger momentum over the longer haul.
Scan 619 high quality undiscovered gems with similar biologics exposure to Innovent Biologics so you can see which other developers are quietly building momentum behind the headlines.
For Innovent Biologics, the recent pullback clashes with stronger multi year returns and fresh regulatory progress. Is pricing now tracking the underlying business, or is it simply reflecting a shift in sentiment as investors reassess value?
Preferred P/E of 114.8x for Innovent Biologics: Is it justified?
On price, Innovent Biologics is not cheap by simple earnings metrics. The stock closed at HK$95, while the latest checks show a P/E of 114.8x that sits well above several key reference points.
P/E compares what investors are paying today for each unit of current earnings. For a research led biopharma group like Innovent Biologics, a high P/E often reflects expectations that profits will expand meaningfully as its drug portfolio matures and new therapies reach scale.
Analysts are currently in agreement that the share price could rise from here, with the target price sitting 35.8% above the last close and the stock also trading 36.7% below an internal fair value estimate based on future cash flows. That points to a market willing to pay a steep multiple today, while still pricing the shares below other valuation anchors that are focused on earnings and revenue forecasts.
The comparison with peers is stark. Management is running a P/E of 114.8x against a Hong Kong Biotechs industry average of 17.7x and a peer group average of 25.4x. The fair P/E ratio implied by regression based analysis sits at 35.1x, which is far lower than where the shares trade now and suggests the earnings multiple could move closer to that level if expectations cool.
Explore the SWS fair ratio for Innovent Biologics.
Result: Price-to-Earnings of 114.8x (OVERVALUED)
Still, any stumble in LP-003’s approval process or slower adoption of Innovent Biologics’ commercial portfolio could quickly challenge the rich 114.8x P/E narrative.
Find out about the key risks to this Innovent Biologics narrative.
Another View on Innovent Biologics' Valuation
The high P/E for Innovent Biologics paints one picture. The SWS DCF model tells a different story. On that framework, the shares at HK$95 are trading below an estimated future cash flow value of HK$150, which points to a sizeable discount rather than excess.
That gap means P/E multiples are flagging valuation risk while the cash flow work suggests potential upside. You are effectively choosing which set of assumptions to trust more: the near term earnings snapshot or the longer term cash generation. Which lens feels more realistic for a drug developer still building out its portfolio?
Look into how the SWS DCF model arrives at its fair value.
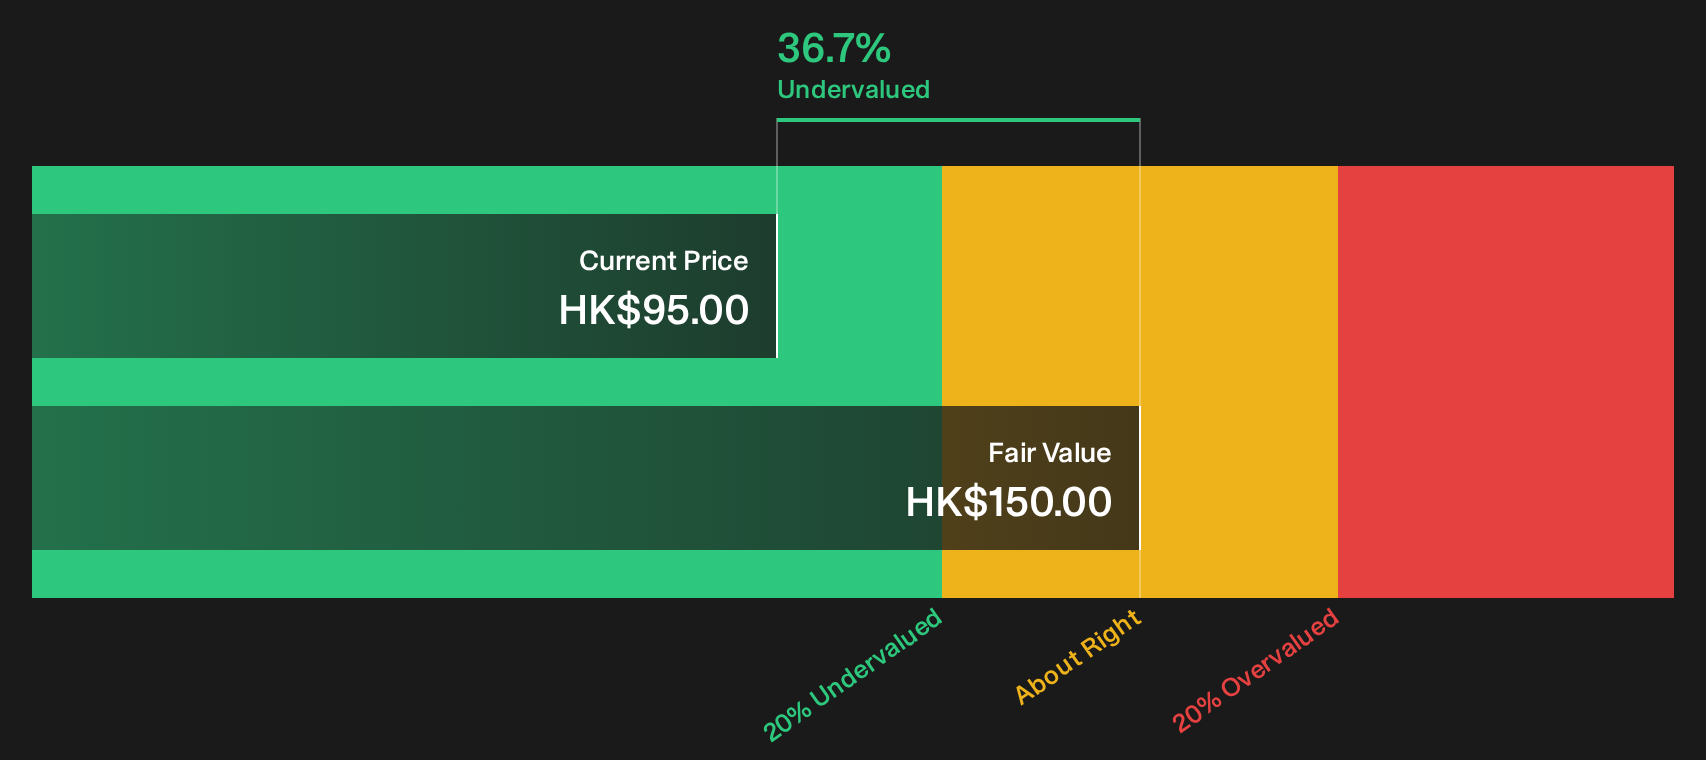
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Innovent Biologics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong opinions run both ways in this Innovent Biologics story. Check the numbers yourself, move quickly, and weigh the upside that others are already watching in the 4 key rewards
Looking for more Innovent Biologics investment ideas?
If you like the setup around Innovent Biologics but do not want to rely on a single story, cast the net wider using focused stock lists.
- Target potential mispricing by scanning a curated pool of quality opportunities through the 196 high quality undervalued stocks.
- Build resilience into your portfolio by focusing on companies screened for strong finances in the list of solid balance sheet and fundamentals (195 results).
- Dial down volatility and concentrate on stability by filtering opportunities inside the 103 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com