
Jensen Huang Says Nvidia Can Grow 70% Next Year. Here’s Why He May Be Right.
Nvidia (NVDA) CEO Jensen Huang just dropped an interesting update on the company's growth. He said he believes the chip giant can grow revenue by 70% next year, a forecast that would take annual sales from roughly $400 billion to about $680 billion.
At first look, that sounds almost too ambitious, but Huang argues that Nvidia is still at the center of the artificial intelligence buildout, and demand for its computing systems remains far from saturated.
The key question for investors is not whether Nvidia can sell more chips. It is whether spending on AI infrastructure can stay high enough to support another massive jump in revenue.
Nvidia Stock Has Plenty of Momentum
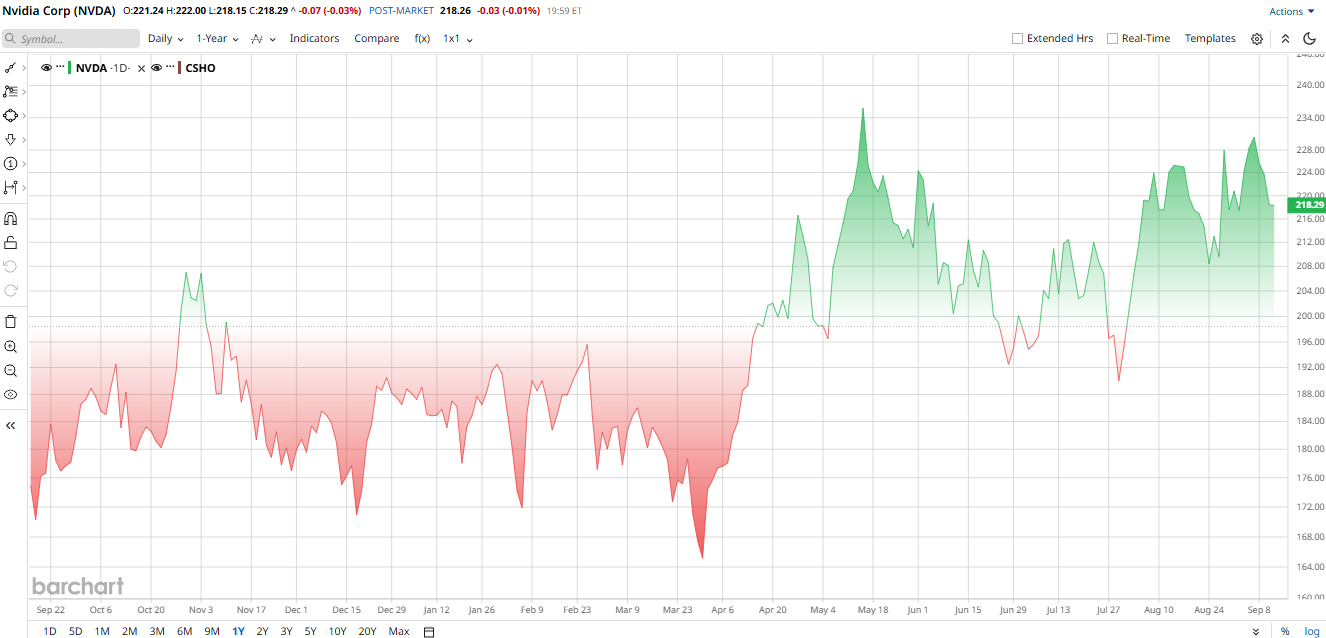
Nvidia shares have gained roughly 14% year-to-date (YTD) in 2026 and about 19% over the past 12 months. The stock has pushed the company's market capitalization above $5.26 trillion as investors continue to bet on strong AI spending.
The road has not been completely smooth. Concerns about competition from hyperscalers developing their own accelerators, along with a Department of Justice probe, have periodically pressured the shares. Still, Nvidia's earnings growth has helped the stock outperform the broader market.
That performance matters because a 70% revenue increase next year would require investors to believe that the current AI spending boom has plenty of room left to run.
Moreover, Nvidia trades at roughly 27.6 times trailing earnings and about 24 times forward earnings. That compares favorably with a technology-sector median trailing P/E above 30. It looks like NVDA stock is hardly a bargain in absolute terms. But if Huang gets anywhere close to his growth forecast, today's valuation could look much more reasonable in hindsight.
AI Demand Could Make 70% Growth Possible
Huang's argument comes down to scale. Nvidia is no longer selling individual GPUs into a single market. It is supplying complete computing platforms to AI labs, cloud providers, and enterprises building massive data centers.
One system combining 36 Grace CPUs with 72 Blackwell GPUs is already seeing monthly sales growth of about 27%. Nvidia says an advanced GPU system can cost roughly $8.5 million, creating enormous revenue opportunities as customers expand capacity.
Huang also said Nvidia's growth could exceed 100% if supply constraints disappeared. That suggests the current revenue trajectory is being limited more by production and deployment capacity than by a lack of demand.
The latest quarter reinforces that argument. For Q2, Nvidia generated $96.22 billion in revenue, up 106% year-over-year (YoY). Data Center sales reached $89 billion, up 117%, while net income jumped 126% to $59.69 billion. Adjusted EPS rose to $2.22 from $1.01, and free cash flow reached nearly $70 billion.
Nvidia expects third-quarter revenue of $108 billion, plus or minus 2%, with gross margin around 74%.
Nvidia Is Building More Than Chips
Another reason the 70% target may be achievable is Nvidia's expanding ecosystem. The company has partnered with Palantir Technologies (PLTR) to bring sovereign AI capabilities to critical supply chains, initially using Nvidia's own operations as a starting point.
The companies are using Nvidia's Nemotron models with Palantir Foundry and AIP to help businesses manage complex data and improve the path from manufacturing wafers to deploying AI workloads.
Nvidia has also worked with AI chip startup d-Matrix, giving the company access to Nvidia's systems and supply chain. These efforts help Nvidia extend its reach beyond traditional GPU sales and make its broader technology stack more valuable to customers.
Wall Street Still Sees Massive Upside on NVDA Stock
Analysts remain focused on Nvidia's earnings power rather than simply its AI narrative. UBS analyst Timothy Arcuri expects earnings per share to reach at least $15 in 2027 and approach $20 in 2028, highlighting just how much operating leverage could remain.
Morgan Stanley, Goldman Sachs, Raymond James, Evercore, and JPMorgan have also raised their expectations, reflecting confidence that AI infrastructure spending can remain elevated.
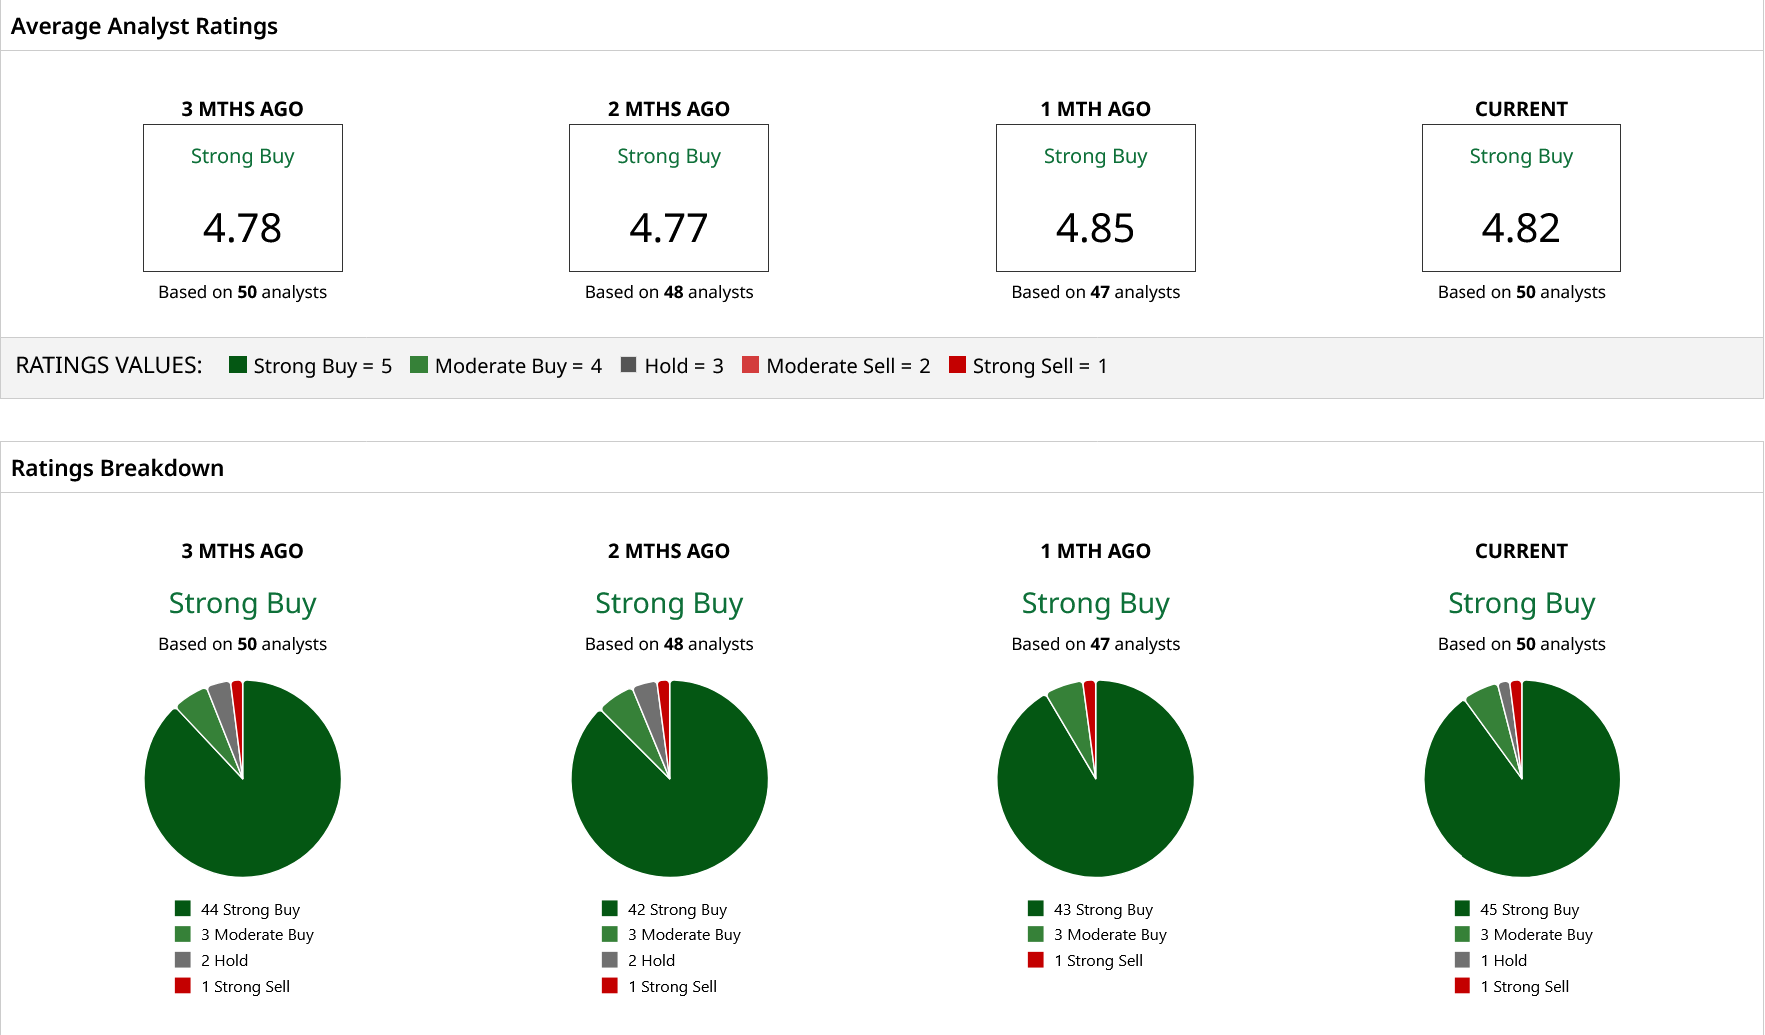
According to Barchart data, Nvidia carries a consensus rating of “Strong Buy,” with an average price target of $326.09, implying roughly 50% upside from current levels.
For Nvidia, Huang's 70% forecast ultimately depends on one thing: whether AI customers continue spending at extraordinary levels. Currently, the company's revenue growth, cash generation, and expanding ecosystem suggest that demand is still doing much of the heavy lifting.
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.