
SAP Stock And Its AI Retail Push After New Partner Deals
- Trifork Group AG and N4XT recently detailed new collaborations with SAP that extend SAP Customer Experience reach and showcase SAP powered retail and AI capabilities at New York Fashion Week through the Retail Innovation Lab with RE/DONE.
- The combination of reseller expansion, real world retail pilots and SAP’s €100 million Business AI Partner led Adoption Incentive highlights how SAP is pushing deeper into AI centric cloud services used in front line customer engagement.
- The focus now turns to how SAP's broader investment narrative could be shaped by these AI driven customer experience partnerships and pilots.
SAP Investment Narrative Recap
To own SAP, you need to believe its push into Business AI, cloud subscriptions and tightly integrated customer experience software can keep earnings growing in the low double digits while margins hold up against heavier compliance and restructuring costs. The short term swing factor is how quickly customers move real workloads onto SAP’s AI infused cloud platforms and actually use the credits they pay for.
The biggest risk is that long, complex enterprise sales cycles, data sovereignty rules and best of breed rivals slow that adoption, leaving unused credits and softer bookings. The Trifork and N4XT announcements help the story and the messaging, but on their own they do not materially change that risk reward balance yet.
Among the recent updates, SAP’s €100 million Business AI Partner led Adoption Incentive sits closest to the core catalyst. It is aimed at turning proofs of concept into deployed AI projects across SAP Business AI products, which directly links to contract value, cloud usage and how deeply SAP is embedded in day to day operations.
For you as an investor, the key execution question is whether this programme and partner activity, such as Trifork’s reseller focus on SAP Sales Cloud v2, translate into steady, real consumption rather than just prepaid credits. If uptake disappoints, the firm could still report solid headline growth while facing pressure on the perceived quality of recurring revenue and on competitive positioning in AI heavy customer experience workloads.
What SAP’s AI Story Implies About The Numbers
SAP's narrative projects €53.0b revenue and €11.2b earnings by 2029. That aligns with analyst expectations for 11.5% yearly revenue growth and implies an earnings increase of about €3.4b from €7.8b today.
Uncover why SAP's fair value indicates an 11% potential upside to its current price that could narrow quickly.
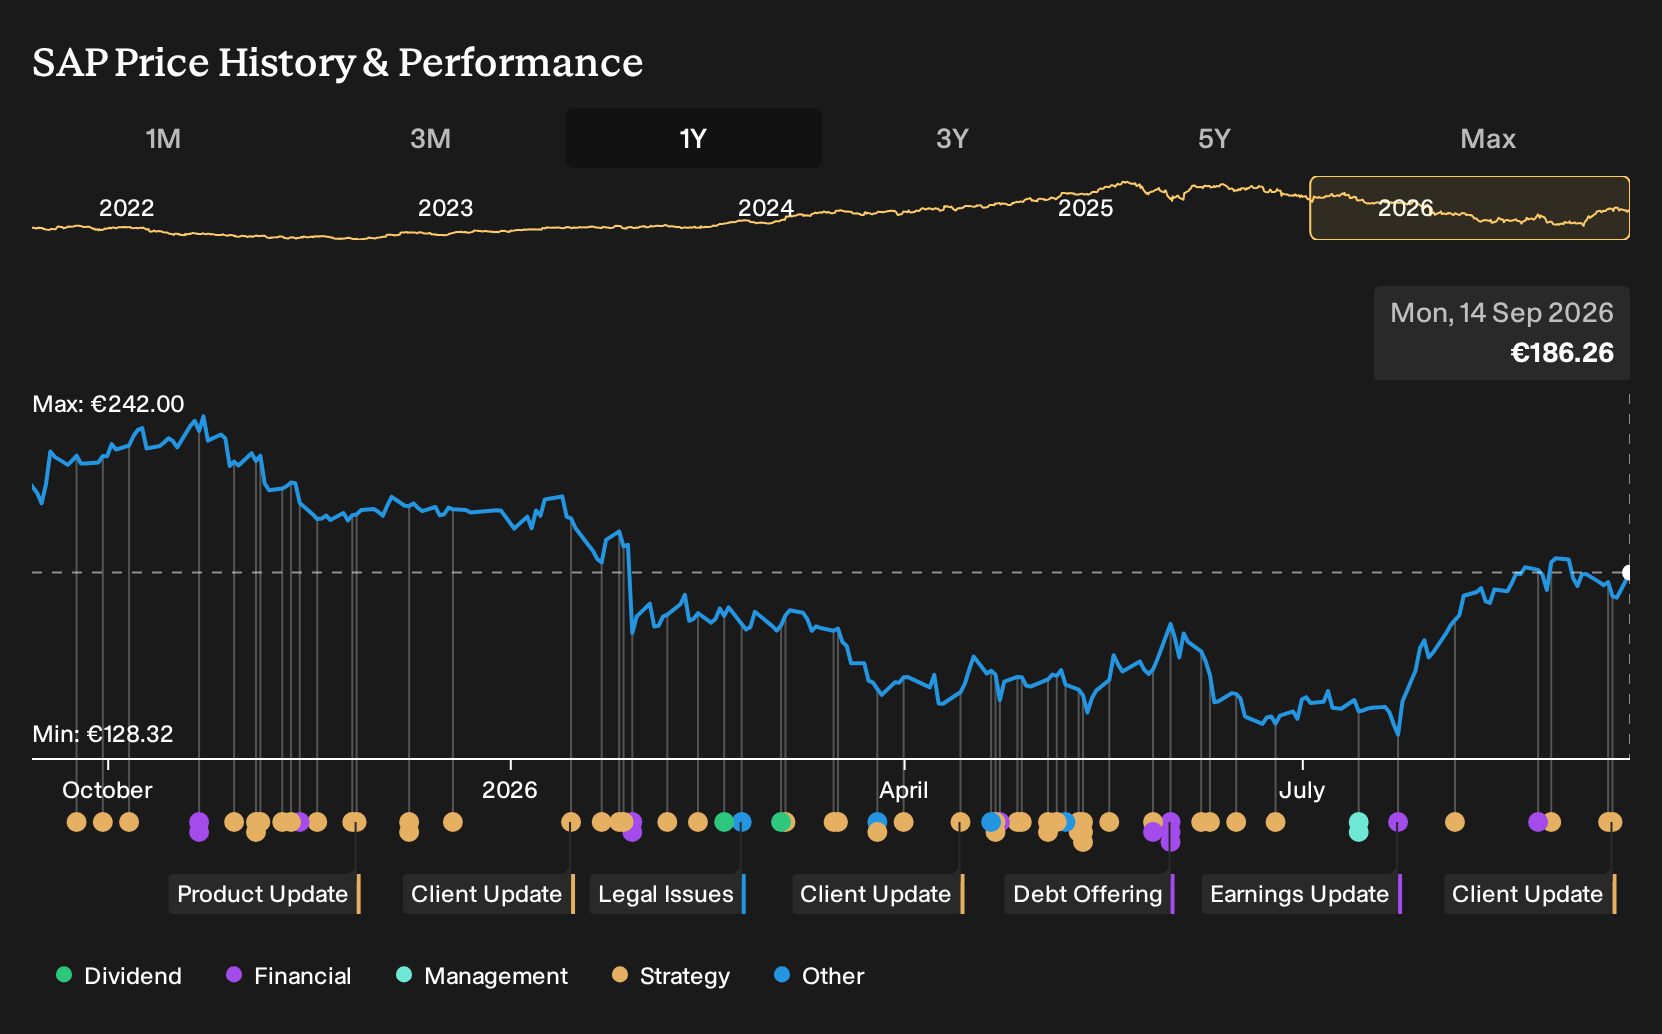
Exploring Other Perspectives
Some of the most optimistic analysts treat SAP’s AI and cloud partnerships as a revenue accelerator, not just a support act. Before this Trifork and N4XT news, the bullish camp already sketched out €56.2b of revenue and €12.5b of earnings by 2029. You can treat those as one possible storyline and compare them with your own expectations.
Explore 15 other SAP fair value estimates, including one that suggests as much as 63% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SAP research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for SAP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SAP's overall financial health at a glance.
Looking For More Ideas Beyond SAP?
If SAP's AI and cloud story has sharpened your appetite for research, it can help to compare it with other companies that match different risk, quality and income profiles. The Simply Wall St Screener gives you a structured way to broaden your watchlist and pressure test your thesis on SAP against what else is out there.
- For investors hunting for potential mispricing, scan through 196 high quality undervalued stocks that pair stronger fundamentals with what may be more modest expectations baked into their share prices.
- If capital preservation comes first for you, filter for 103 resilient stocks with low risk scores that combine sturdier balance sheets with gentler risk scores.
- When you want to back quality businesses before they are widely followed, use the screener to surface 619 high quality undiscovered gems that align with your own return and risk targets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com