
Learn Why The Bull Case For Boyd Group Services (TSX:BYD) Could Change Following Share Buyback Plan
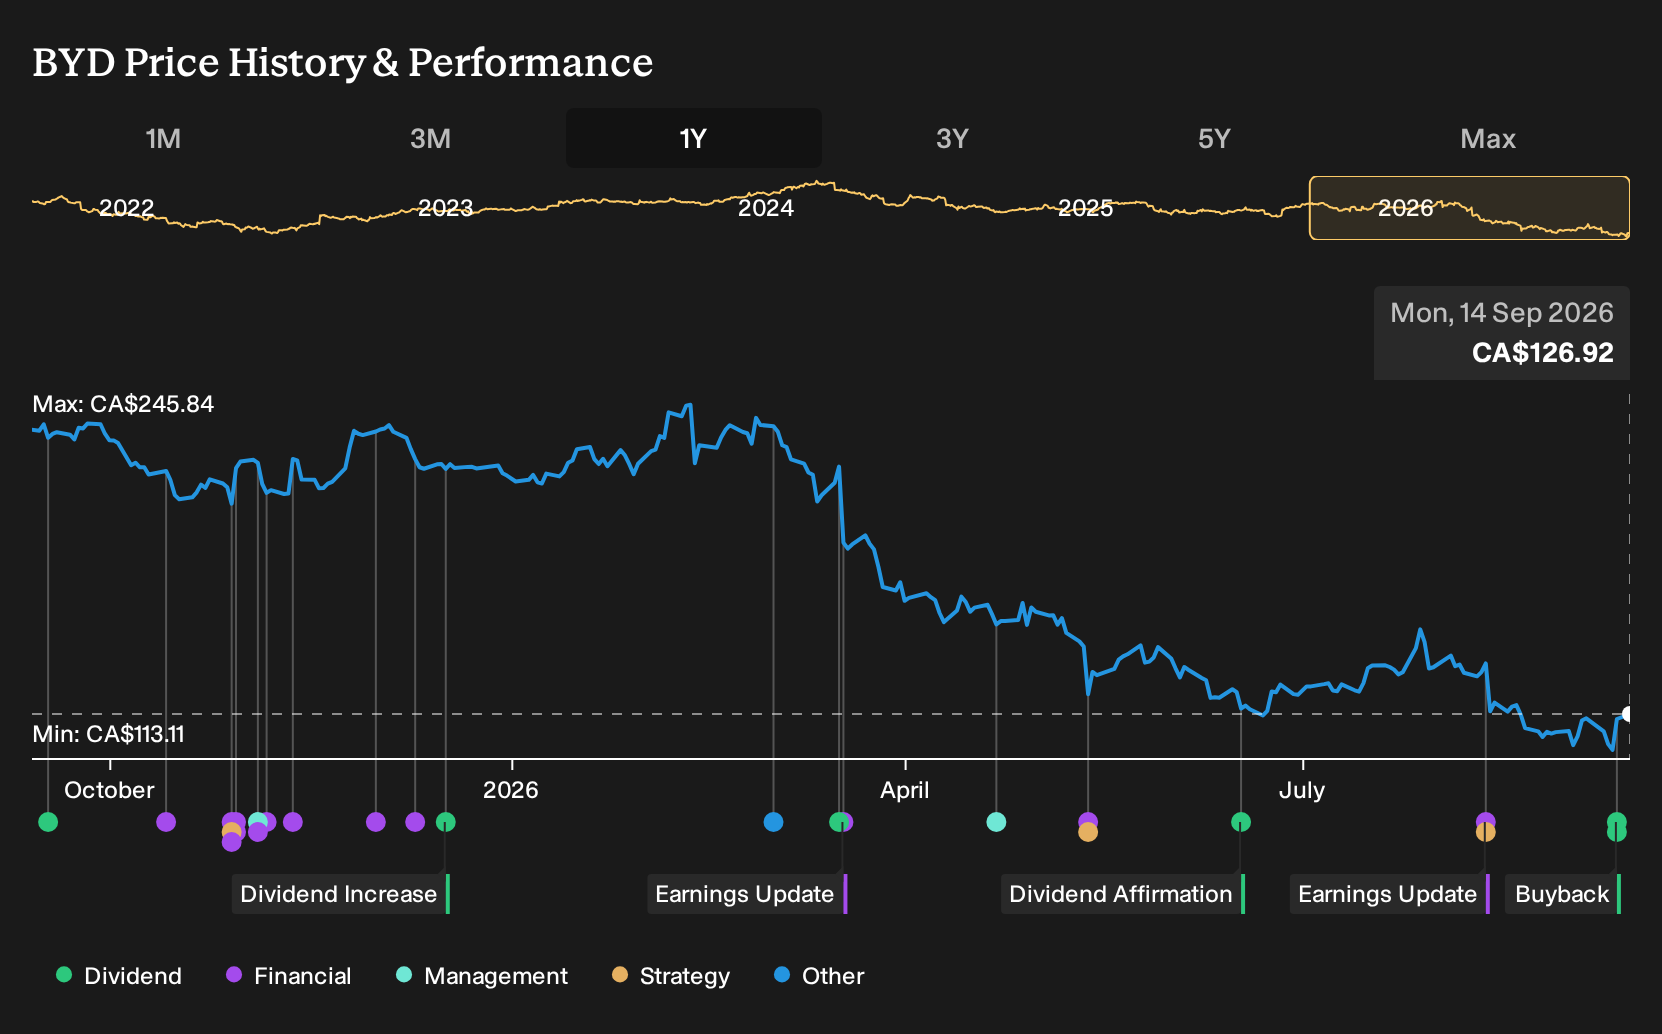
- Boyd Group Services announced a normal course issuer bid in September 2026 to repurchase up to 2,779,352 shares, or 9.98% of its issued share capital, with all acquired shares to be cancelled by no later than the bid expiry on September 15, 2027.
- The decision by Boyd Group Services' board to authorize a sizeable share repurchase creates additional flexibility in capital allocation, which may influence how the business balances buybacks against funding collision center expansion, technology investment, and cost efficiency initiatives.
- This development sets the stage for further analysis of how Boyd Group Services' sizable share buyback authorization could reshape the investment narrative built around expansion and efficiency.
Boyd Group Services Investment Narrative Recap
To own Boyd Group Services, you need to be comfortable with a collision repair business that leans on expansion, insurer relationships and cost programs like Project 360 to support earnings, while working through thin net margins and uneven claims volumes. The buyback itself does not change the near term operational story. That story still turns on execution in new locations and process efficiency.
The key short term swing factor remains how well Boyd manages repair complexity, wage pressure and technician availability without letting costs run ahead of pricing and productivity gains. The biggest risk is that higher borrowing costs and interest coverage constraints limit flexibility if volumes soften or integration returns disappoint.
The new normal course issuer bid to repurchase up to 2,779,352 shares, roughly 9.98% of the float, matters mainly because it interacts with a business that recently relied on external funding and had shareholders diluted over the past year. You now have a listed group that is still investing in growth while also committing capital to shrink the share count over time.
For you as an investor, the useful question is how this planned reduction in outstanding stock sits alongside the main catalysts analysts focus on, such as earnings growth expectations and scale benefits from Project 360. If the operational plan delivers, fewer shares could magnify per share outcomes, but if interest costs or claim volumes move against Boyd, the buyback will not resolve those underlying pressures.
Boyd Group Services' narrative projects $4.9b revenue and $258.2 million earnings by 2029. That profile assumes 10.7% yearly revenue growth and an earnings increase of about $249.2 million from $9.0 million today.
Uncover why Boyd Group Services' fair value indicates a 75% potential upside to its current price. This opportunity could narrow quickly if sentiment becomes more optimistic.
Exploring Other Perspectives
Some of the most optimistic analysts framed repair complexity as a powerful upside catalyst for Boyd Group Services, not just a cost risk. Before this buyback announcement, that group was projecting about 16.0% annual revenue growth and roughly $349.5 million in 2029 earnings. Those forecasts did not factor in a 9.98% share repurchase, so views on both upside and risk could shift.
Explore another Boyd Group Services fair value estimate, including one that suggests as much as 414% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Boyd Group Services research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Boyd Group Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boyd Group Services' overall financial health at a glance.
Looking For More Ideas Beyond Boyd Group Services?
If you want to put Boyd Group Services in context, it helps to line it up against other opportunities with different risk and income profiles. The Simply Wall St screener lets you scan broader markets quickly so you can build a shortlist that fits your own return expectations and risk tolerance.
- For investors hunting for underappreciated opportunities backed by strong fundamentals, start with a 3 high quality undervalued stocks that combine resilient cash flows with balance sheets that can handle tougher conditions.
- If capital preservation ranks high on your checklist, filter for companies with sturdier finances using our list of solid balance sheet and fundamentals (7 results) so you can see which businesses might better withstand financial stress.
- Income focused readers can tilt toward cash returns by reviewing a 2 dividend fortresses that aim to pair higher yields with more robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com