
How Investors May Respond To DTS (TSE:9682) Core System Lawsuit
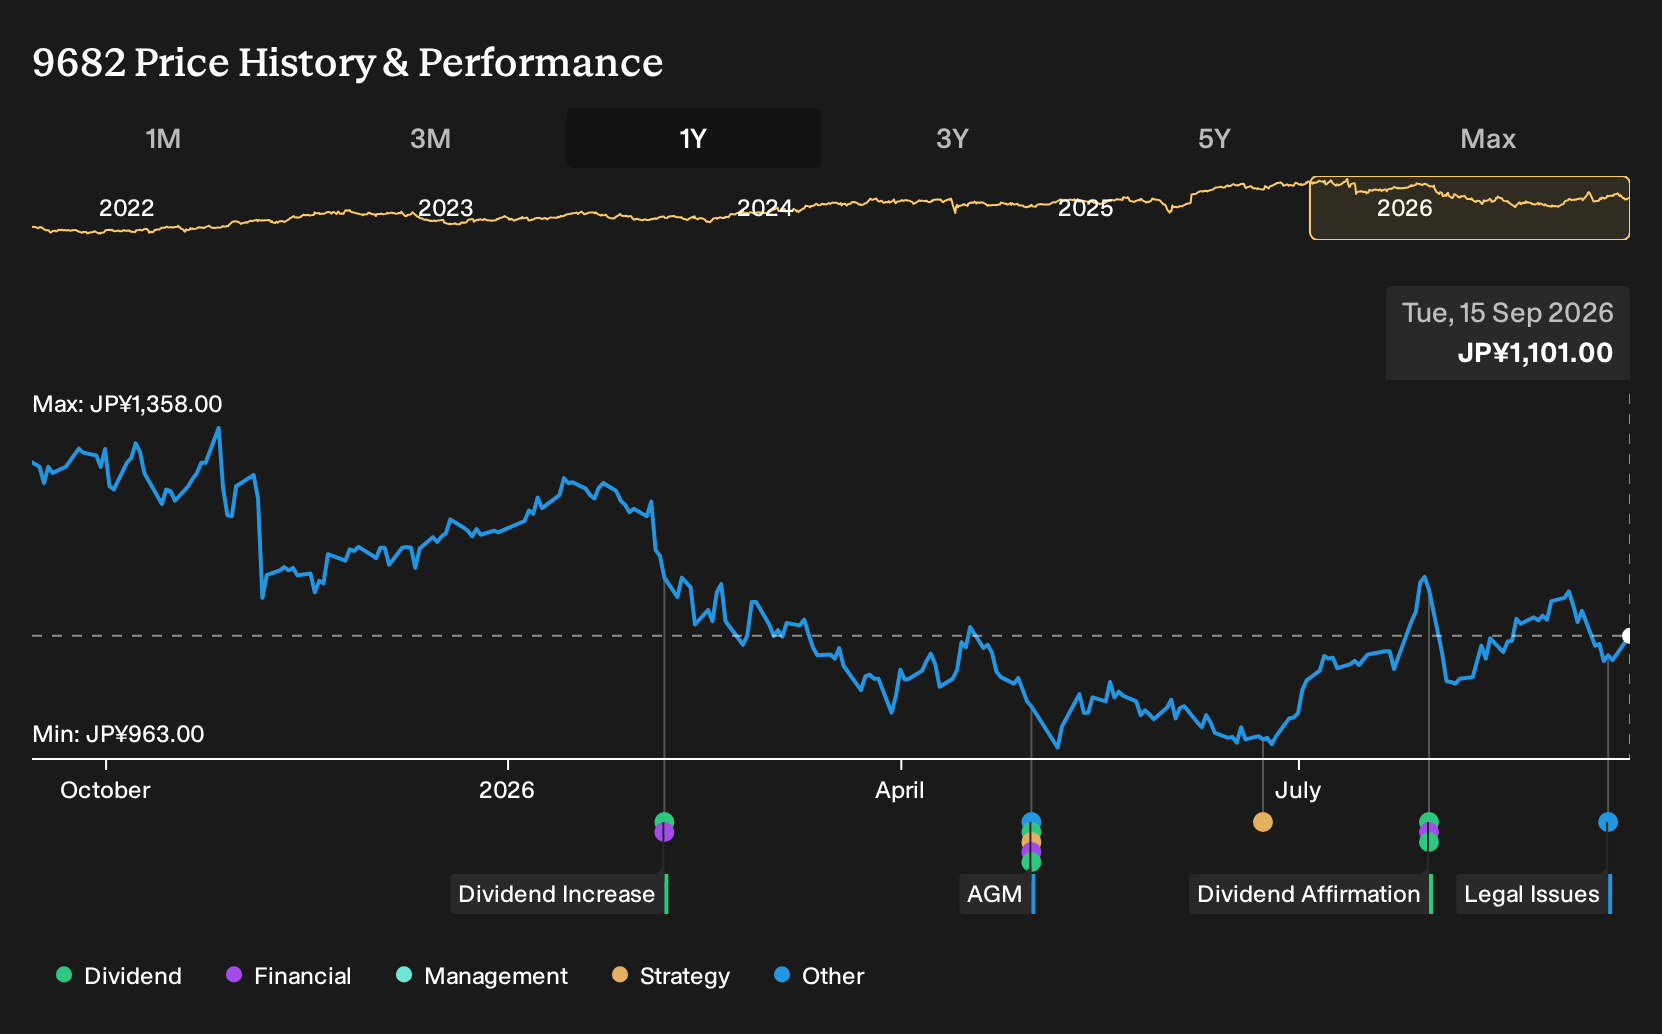
- Premium Co., Ltd., a consolidated subsidiary of Premium Group, has filed a counterclaim in Tokyo District Court against DTS CORPORATION, seeking JPY 5,015 million in damages over an allegedly non functioning core IT system that forced a return to its legacy platform.
- The dispute highlights material execution risk for DTS in complex system development projects, because the alleged failures affected a client’s primary finance business operations and prompted claims over both disruption and sunk development costs.
- We will now consider how DTS CORPORATION's investment narrative could be influenced by this large client counterclaim over system performance.
Balance potential lawsuit risk at DTS by considering alternatives with sturdier profiles through a curated list of 12 resilient stocks with low risk scores.
What Is DTS' Investment Narrative?
DTS is basically a bet on steady systems integration work in Japan, where demand for finance, government and enterprise IT projects stays disciplined and clients lean on external partners. The big picture you need to buy into is that this project pipeline, plus a broad software and services lineup, can support moderate revenue and earnings growth without extreme capital needs. Forecasts in the article point to earnings growth of 7.6% a year and revenue growth of 5.6% a year, with a P/E of 15.2x that sits below both IT peers and the firm’s own indicated fair P/E of 19.3x.
The Premium Group counterclaim goes straight to the execution side of that story. A core system that allegedly did not function properly for a primary finance client is not just about one contract. It touches on delivery risk, reputational impact in financial services and the chance of further legal or settlement costs. In the short term, that sits alongside existing issues like an unstable dividend track record, recent share price underperformance versus the broader JP market and slightly softer profit margins year on year as the key things to watch.
Yet there is one operational wrinkle around DTS that tends to get less attention until you look closely at ...
There's only one way to know the right time to buy, sell or hold DTS. Head to Simply Wall St's company report for the latest analysis of DTS's Fair Value.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your DTS research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DTS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DTS' overall financial health at a glance.
Looking For More Ideas Beyond DTS?
If this DTS situation has you rethinking concentration risk, it can help to scan a wider field of potential holdings using structured filters rather than relying on gut feel alone.
- For investors who care most about valuation support, use the screener to hunt for companies trading on attractive fundamentals through 18 high quality undervalued stocks.
- If stability and resilience matter more to you than excitement, tilt your search toward businesses with stronger financial footing using the list of solid balance sheet and fundamentals (20 results).
- Income focused investors can narrow the field to cash return opportunities by screening for higher yielding candidates with 17 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com