
HP (HPQ) Could Be 45% Overvalued Following Its New AI Workstation Launch
HP (HPQ) is drawing fresh attention after launching the HP ZBook Ultra G3a, a mobile workstation pitched as a personal AI factory that runs large language models locally for professional users.
HP shares have been volatile around AI hardware headlines, with the launch of the ZBook Ultra G3a coming shortly after new OmniBook Ultra and OmniBook X systems were unveiled and an upgraded annual outlook tied to demand for premium AI PCs and workstations. Despite a 1-day share price decline of 4.12%, the stock has a 30-day share price return of 12.99% and a year-to-date share price return of 53.80%, while total shareholder return sits at 28.84% over 1 year and 50.79% over 5 years. These figures point to momentum that has been building rather than fading over time.
Scan how other AI hardware players are lining up by reviewing our curated list of 60 AI infrastructure stocks that could echo HP's push into local AI workstations and premium PCs.
HP has already logged a strong run on AI excitement and premium PCs. The valuation question now is simple: Is most of that move already reflected in the price, or is there still clear upside ahead?
Most Popular Narrative: 45% Overvalued
HP closed at $34.02, while the most followed narrative anchors fair value at $23.41. The current price sits well above that estimate and puts the burden of proof on future execution.
Recent Street research on HP shows a wide range of views on how the company will balance earnings execution, margin pressure from memory costs, and a softer PC backdrop through 2026. Price targets now span from the high teens to the low 30s, which reflects differing expectations for HP's ability to sustain profitability after a stronger first half and through its current leadership transition.
See why 56 investors see HP as 45% overvalued.
Result: Fair Value of $23.41 (OVERVALUED)
Still, HP faces pressure if rising memory costs squeeze PC margins or if ongoing declines in traditional print demand erode the cash engine that funds its AI initiatives.
Find out about the key risks to this HP narrative.
Another Take On What HP Is Worth
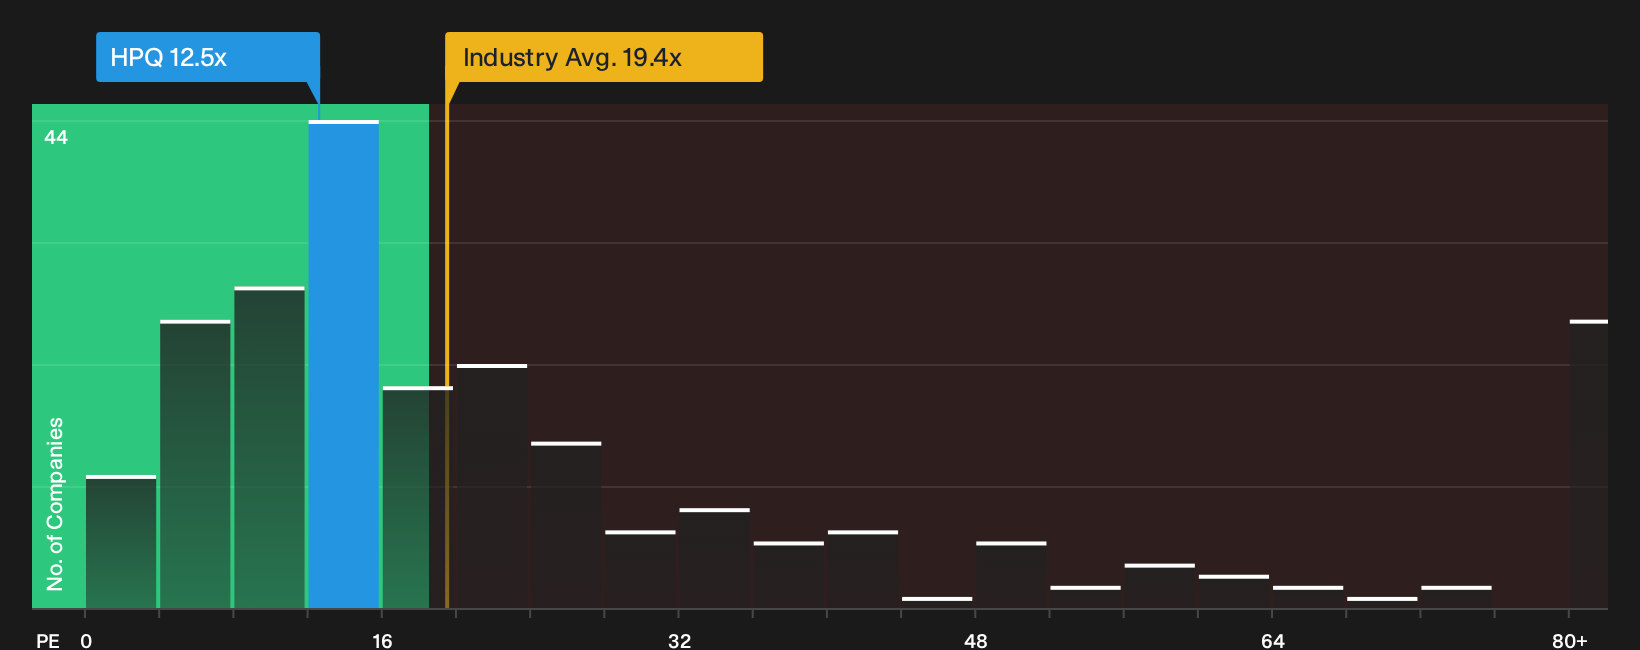
The first narrative presents HP as about 45% overvalued at $34.02 versus a fair value of $23.41, based on future earnings and analyst targets. A different lens using the current P/E of 12.5x tells a very different story.
That multiple is well below the Global Tech industry average of 19.4x and far under the peer average of 47x. It also sits against a fair ratio of 26.8x that our regression work suggests the market could move toward over time. This points to a lot of valuation risk sitting with those who expect a sharp de-rating rather than with investors worried about overpaying today.
When one model argues HP is priced too high while simple P/E comparisons indicate it trades cheaply against both peers and a fair ratio, which view do you think better reflects how the market will treat steady but modest growth, high quality earnings, and a 3.53% dividend yield?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on HP's valuation are clear, so move fast, review the full data for yourself, and weigh the 4 key rewards and 2 important warning signs.
Looking for more HP sized opportunities?
Do not stop with HP. Tap into fresh ideas now and let data driven screeners point you toward setups you would otherwise miss.
- Target potential mispricings early by scanning the 35 high quality undervalued stocks before other investors catch on.
- Build dependable income by focusing on the 6 dividend fortresses that aim to pair yield with resilience.
- Shield your portfolio from shocks by concentrating on the 11 resilient stocks with low risk scores that aim for steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com