
Micron (MU) Stock Looks Reasonable On Its Very Large 3 Year Run
Micron Technology has become one of the most closely watched AI memory plays, and after a multi year surge in the share price, the real question for investors is whether today's valuation can be grounded in its earnings power.
- Over the past 3 years, Micron stock has delivered a very large gain of about 1,225%, which puts a lot of pressure on its earnings to support the current price.
- Recent profit strength tied to AI driven memory demand, along with labor disputes in Taiwan that could affect costs and capacity, may influence how sustainable Micron's earnings and margins look from here.
- Your read on Micron Technology is one view; the desks covering it have another. See what analysts think Micron Technology's shares could be worth.
The stock's next move may depend on whether Micron's current earnings, and what they imply for future profitability, can justify where the shares trade today.
If you are weighing Micron Technology against other AI hardware plays, it can help to see how it compares with 60 AI infrastructure stocks.
Is Micron Technology Still Cheap on Earnings?
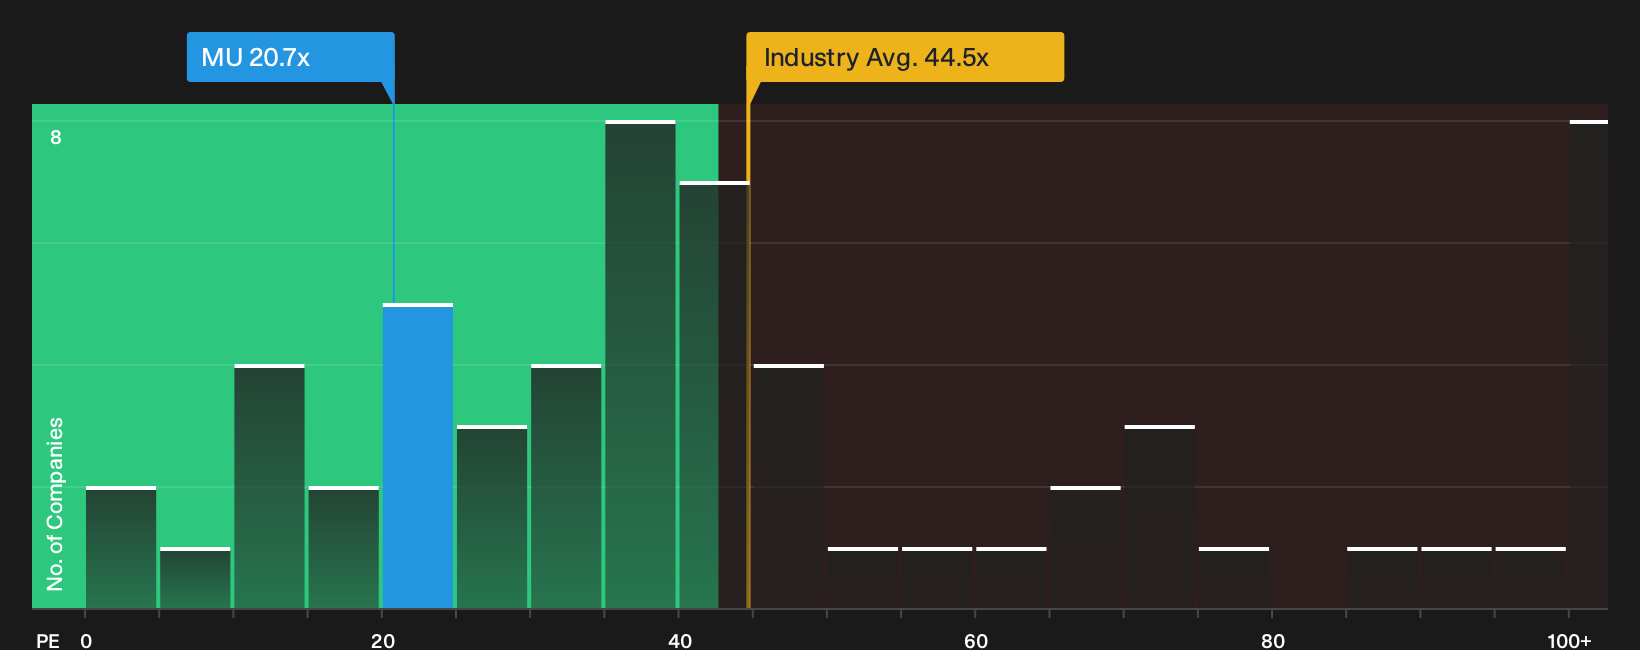
The P/E ratio is a useful starting point for Micron Technology because earnings are central to how investors frame memory chip cycles. On this metric, the stock trades at about 20.7x earnings, which is below both the broader semiconductor industry average of roughly 44.5x and a peer group that clusters much higher at around 66.7x. That gap suggests the market is asking for a discount on Micron compared with other chip makers that are also exposed to AI hardware demand.
The fair multiple implied by a fuller model that weighs Micron Technology's growth outlook, profitability profile, size and risk sits above where the shares trade today. This points to the P/E as screening undervalued on this framework. Because recent profit strength tied to AI driven memory demand is now colliding with the threat of a large strike at Micron's key Taiwan facilities, the current discount on earnings may reflect investor concern that supply disruptions or higher labor costs could affect the earnings base that supports this ratio. Explore the numbers behind Micron Technology's P/E valuation.
The Micron Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Micron Technology valuation puzzle leaves off by spelling out which earnings, growth and margin paths would need to play out for the stock to be worth far more or meaningfully less than today’s level, and they sit on the platform’s Community page. Rather than relying on a single P/E or model output, each scenario lays out the key assumptions behind its view of fair value so you can compare those against Micron Technology's reported results over time.
Community views on Micron Technology split between those who think the AI memory boom has reshaped the cycle and those who see familiar late cycle risks.
Bull case: 26% undervalued
"The bull case is simple: AI has pulled memory from the commodity bucket into the strategic infrastructure bucket..."
Discover why this Narrative puts Micron Technology at 26% undervalued.
Bear case: 68% overvalued
"The real question is how long pricing power lasts. They are sold out for 2026, but i do not know about '27's status..."
Explore why this Narrative puts Micron Technology at 68% overvalued.
The valuation of Micron Technology still leaves one crucial angle unexplored
Numbers only tell part of the story for Micron Technology, because the people directing capital allocation, setting risk appetite and deciding when to reinvest or return cash really shape how those earnings get used. See who runs Micron Technology and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com