
Skyworks Solutions (SWKS) Rebound Puts Its Pricey Valuation Back In Focus
Skyworks Solutions (SWKS) is back in focus after the stock was reported as the best performing S&P 500 component on Tuesday, rebounding quickly following a brief pullback on Monday.
That sharp rebound sits on top of a 23.08% year to date share price return and a 13.85% 1 month gain, even though the 1 year total shareholder return is 12.30% and the 5 year total shareholder return is down 46.45%. This suggests momentum in Skyworks Solutions is building in the short term, while the longer track record remains mixed and keeps investors focused on how recent index removal and ongoing Qorvo related debt exchange activity might be reshaping sentiment on growth potential and risk.
Capitalize on the surge in Skyworks Solutions and scan a curated 60 AI infrastructure stocks that could be catching similar momentum across the semiconductor supply chain.After this sharp move, Skyworks Solutions now trades above the average analyst target and well away from some intrinsic value estimates. Is the market simply catching up, or has enthusiasm run ahead of fair value?
Most Popular Narrative: 16% Overvalued
At a last close of $79.26 against a narrative fair value of $68.25, the most followed view on Skyworks Solutions frames the recent surge as pricing in more optimism than that fair value implies, especially with so much tied to smartphones and the Qorvo merger story.
Accelerated adoption of advanced wireless standards and AI-capable smartphones is increasing the RF content required per device, which is positioning Skyworks to benefit from higher average selling prices and potential unit volume growth. This in turn is described as a driver of revenue and gross margin expansion.
Rapid growth in edge IoT, automotive, and industrial applications, in part due to the proliferation of WiFi 7 and high-connectivity requirements, is cited as enabling Skyworks to diversify beyond mobile and build a more resilient, higher-margin Broad Markets business. This is presented as a support for topline growth and margin improvement.
See why 54 investors see Skyworks Solutions as 16% overvalued.
Result: Fair Value of $68.25 (OVERVALUED)
Still, concentration in one major smartphone customer and heavy exposure to a handset market under pressure could quickly flip the prevailing Skyworks Solutions optimism on its head.
Find out about the key risks to this Skyworks Solutions narrative.
Another View On Skyworks Solutions Valuation
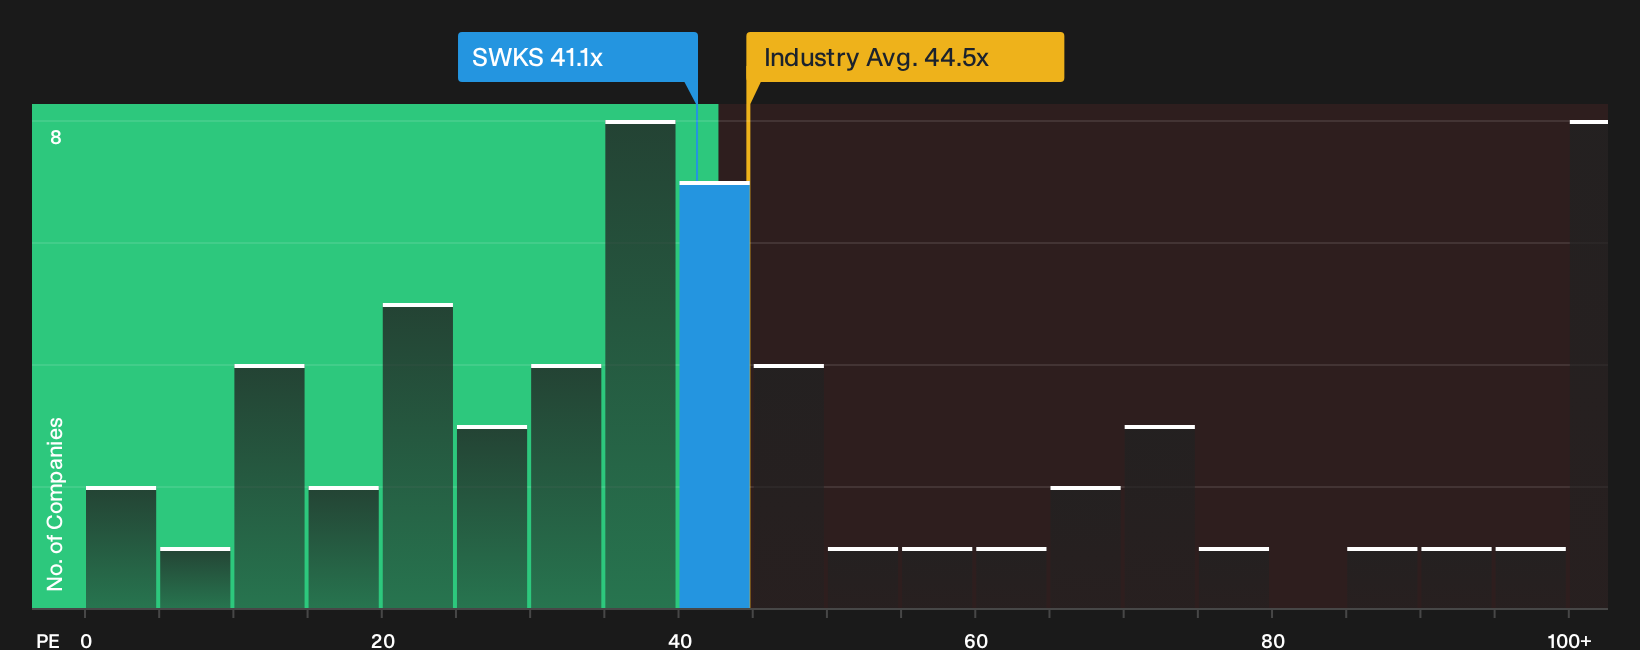
While the narrative fair value of $68.25 frames Skyworks Solutions as 16% overvalued, the earnings multiple tells a different story. The current P/E of 41.1x sits below the US Semiconductor industry at 44.5x and well below peers at 55.2x, yet above a fair ratio of 25.3x that the market could gravitate toward. That mix of relative discount and fair ratio premium leaves a simple question for investors: is this price compensating you enough for execution and concentration risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Skyworks Solutions is clearly split. This is exactly why it pays to look under the hood yourself right now and weigh both sides of the story. To frame that decision with clear evidence, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Skyworks Solutions?
Do not stop with Skyworks Solutions. Broaden your watchlist now, because some opportunities may appear where fewer investors are already looking.
- Target quality at a discount by scanning companies that combine strong fundamentals with attractive pricing through the 35 high quality undervalued stocks.
- Focus on resilience and prioritize stability by checking a 11 resilient stocks with low risk scores that filters for businesses with more stable risk profiles.
- Explore potential candidates by reviewing a 15 high quality undiscovered gems that highlights underfollowed stocks with solid underlying foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com