
Why Jefferies Is Bullish on Formula One Stock Now
Liberty Media Formula One (FWONK) is increasingly looking like more than a fast-growing sports franchise — it is becoming a premium global media and entertainment asset. That view is gaining traction on Wall Street, with Jefferies initiating coverage of FWONK stock with a “Buy” rating and a $115 price target, implying about 22% potential upside from current levels. Jefferies views Formula One as a high-quality media and consumer-experiences business, supported by its premium sports assets, asset-light model, and margin-expansion opportunity.
Jefferies believes that the company streamlining Formula One and MotoGP after the Liberty Live separation and MotoGP acquisition could improve how its allocates capital and executes. Moreover, analysts highlighted Apple's (AAPL) new U.S. F1 media-rights deal for Apple TV, estimating it could add revenue of about $55 million annually through 2030. Overall, the firm expects revenue to grow to $5.84 billion in 2028, and adjusted OIBDA margins to expand to 27.2%.
The fresh price target from Jefferies suggests that FWONK stock could have meaningful upside if the company continues to monetize its global popularity while expanding the value of its portfolio. Let's take a closer look.
About Liberty Media Formula One Stock
Sporting a market capitalization of $21.4 billion, Liberty Media Formula One is a global motorsports and entertainment business focused on the commercial rights and promotion of the FIA Formula One World Championship. The company’s portfolio also includes MotoGP, following Liberty Media’s acquisition of the motorcycle racing series. The business generates revenue through media rights, race promotion, sponsorship, and other commercial opportunities tied to its sports properties.
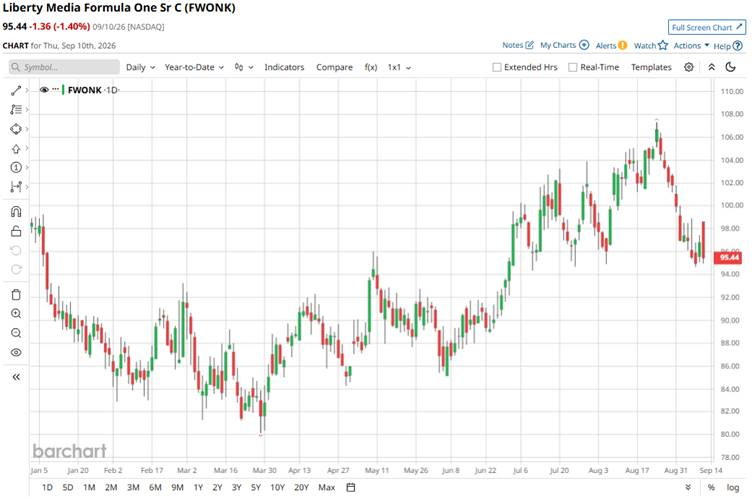
FWONK stock has remained under pressure despite a strong long-term growth story. The stock’s recent weakness comes as it faces questions over audience growth and the sustainability of its rapid expansion. Recent reports point to softer U.S. viewership for several major races, while this year's cancellation of the Bahrain and Saudi Arabian Grands Prix amid conflict in the Middle East has also weighed on financial comparisons. Formula One’s second-quarter revenue was reportedly down sharply.
FWONK stock has climbed about 18% from its 52-week low of $80.15 reached in March, but its broader performance has been relatively muted. Shares are down 4% year-to-date (YTD) as well as down 4% over the past 52 weeks.
The stock has also seen a string of intraday declines since late August, although shares rose almost 2% on Sept. 9, suggesting investors responded favorably to Jefferies' latest coverage. However, shares plunged 1.4% in the following session, driven by persistent worries over higher valuation multiples and broader growth concerns.
Liberty Media Formula One stock currently trades at a premium valuation compared to the sector median, changing hands at 47.7 times forward earnings and 4.7 times sales.
An Operating Performance Snapshot
The company reported its Q2 2026 results on Aug. 6, with the headline numbers showing a sharp year-over-year (YOY) decline, largely because the 2026 F1 calendar had significantly fewer races in the quarter compared to last year. Liberty Media said only five F1 races were held in Q2 2026 compared with nine in Q2 2025, making the YOY comparison unusually difficult.
Liberty Media revenue, which includes Formula One and MotoGP, fell 30% YOY to $934 million from $1.34 billion. Formula One revenue declined 38% to $764 million. Within F1, primary revenue fell 40% YOY to $622 million, while other F1 revenue declined 27% YOY to $142 million. The company said the declines were mainly attributable to the four fewer races, which reduced the proportion of season-based revenue recognized during the quarter.
Profitability also weakened substantially. F1 adjusted OIBDA fell 61% to $139 million from $361 million, while F1 operating income dropped 75% YOY to $73 million from $293 million. At the consolidated level, adjusted OIBDA declined 44% to $206 million from $369 million, while operating income fell to $88 million from $280 million.
Net earnings attributable to Liberty Media stockholders dropped to $5 million from $204 million. Meanwhile, EPS came in at $0.02 versus $1.52 a year earlier, missing the consensus estimate.
On a pro forma basis, assuming Liberty owned the business during the comparable 2025 period, MotoGP revenue declined just 2% to $170 million, while adjusted OIBDA increased 3% to $76 million. Operating income was flat at $37 million. Through the first six months, however, MotoGP performed better, with revenue up 6% YOY to $264 million and adjusted OIBDA up 10% YOY to $92 million on a pro forma basis.
The first-half figures provide a better indication of the underlying trend. F1 revenue declined 15% YOY to $1.38 billion, while adjusted OIBDA fell 30% to $311 million and operating income decreased 32% to $180 million. Importantly, Liberty emphasized that these declines were largely calendar-driven, as F1 held eight races through June 2026 versus 11 races in the comparable 2025 period.
Management now expects a 23-race F1 calendar for 2026, after rescheduling the Bahrain Grand Prix to Malaysia in October, compared with 24 races in 2025. The company expects the remaining calendar changes and season-based revenue recognition to improve the second-half comparisons, and also indicated that the business should return to a 24-race calendar in 2027.
Beyond the headline financial decline, management pointed to several positive operating indicators. F1 said that total hours watched climbed 13%, while U.S. viewership on Apple TV was higher YOY, and followers on social media increased 19% YOY. The company also extended the Las Vegas Grand Prix for another 10 years through 2037.
On the other hand, analysts anticipate EPS to fall 8% YOY to $2 in fiscal 2026 before rising 16% to $2.32 in fiscal 2027.
What Do Analysts Expect for FWONK Stock?
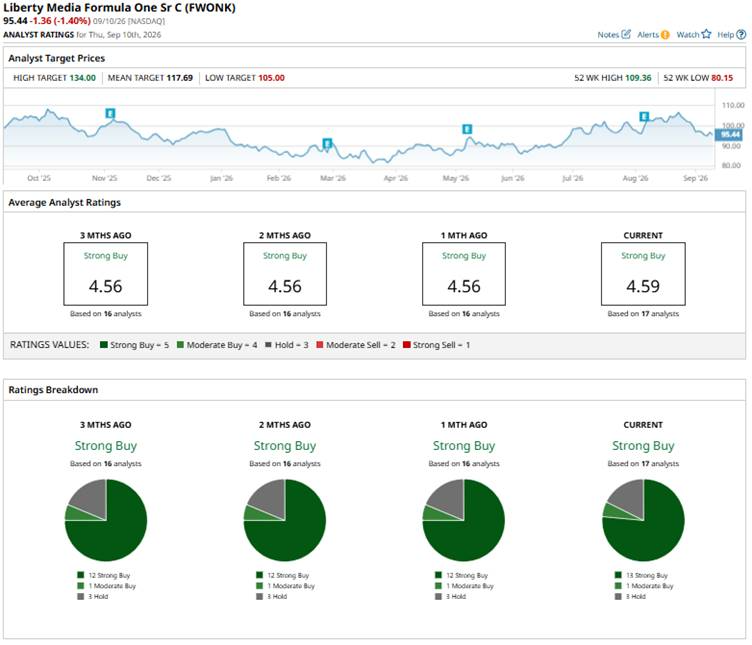
Jefferies wasn't the only firm to turn bullish on Liberty Media Formula One. In August, Guggenheim maintained a “Buy” rating on FWONK stock and raised its price target to a Street-high of $134 from $125, citing continued sponsorship momentum, growing profitability at the Las Vegas Grand Prix, and opportunities from international media-rights renewals.
Overall, FWONK stock has a consensus “Strong Buy” rating on Wall Street. Out of 17 analysts covering the stock, 13 recommend a “Strong Buy,” one suggests a “Moderate Buy,” and three analysts stay cautious with a “Hold” rating. The average price target of $117.69 indicates potential upside of 24% from current levels, while the Street-high target price of $134 suggests potential upside of roughly 42% ahead.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.