
Does Sweepstakes Giveaway Change The Bull Case For Polaris Stock (PII)?
- Monster Energy Company launched a Call of Duty: Modern Warfare 4 promotion in 2026 that offered in game rewards and four retailer specific sweepstakes featuring Polaris off road vehicles and a snowmobile as grand prizes across 7 Eleven, QuikTrip, Hy Vee and RTG.
- This promotion gives Polaris broad exposure across gaming and energy drink customers, tying its vehicles to highly trafficked retailers and a major entertainment franchise at no direct purchase price point for participants.
- We will look at how the investment narrative for Polaris is affected by this large scale Monster Energy vehicle giveaway campaign.
Scan for other entertainment linked plays moving on consumer promotions by checking out the hand picked 15 high quality undiscovered gems. Like Polaris, they sit at the crossroads of brands and fan engagement.
Polaris Investment Narrative Recap
To own Polaris, you need to believe the powersports cycle eventually rewards a manufacturer that keeps its brands visible, its products compelling and its cost base under control. The Monster Energy Call of Duty promotion helps brand awareness with younger and gaming focused riders, but it does not change the core near term story around tariffs, demand and profitability.
The key nearer term swing factor is whether Polaris can offset forecast tariff costs of about $320 million to $370 million while keeping dealers healthy and retail pricing intact. The biggest risk remains pressure on volumes from softer powersports and marine demand, especially with high interest rates and aggressive competitor promotions still in the mix.
The Monster Energy x Call of Duty sweepstakes ties directly into Polaris off road and snow products. This speaks to how management is trying to keep its RZR, Sportsman and snowmobile lines front of mind with recreational riders without discounting. This type of exposure can support the premium positioning of vehicles like Polaris XPEDITION and RANGER if shoppers later show up at dealerships already familiar with the brand.
For catalysts, the more important test is still execution on tariff mitigation, product launches and dealer inventory, not the outcome of a consumer giveaway. Investors watching Polaris may treat this campaign as a complement to the heavier lifting on margins, earnings recovery and international performance, especially after the reported 16% sales drop outside North America and the ongoing uncertainty created by withdrawn full year guidance.
Polaris' narrative projects US$8.0b revenue and US$447.6m earnings by 2029. This implies 2.1% yearly revenue growth and an earnings increase of about US$708m from current earnings, which are a US$260.4m loss.
Uncover how Polaris' fair value indicates a 26% potential upside to its current price that could narrow quickly.
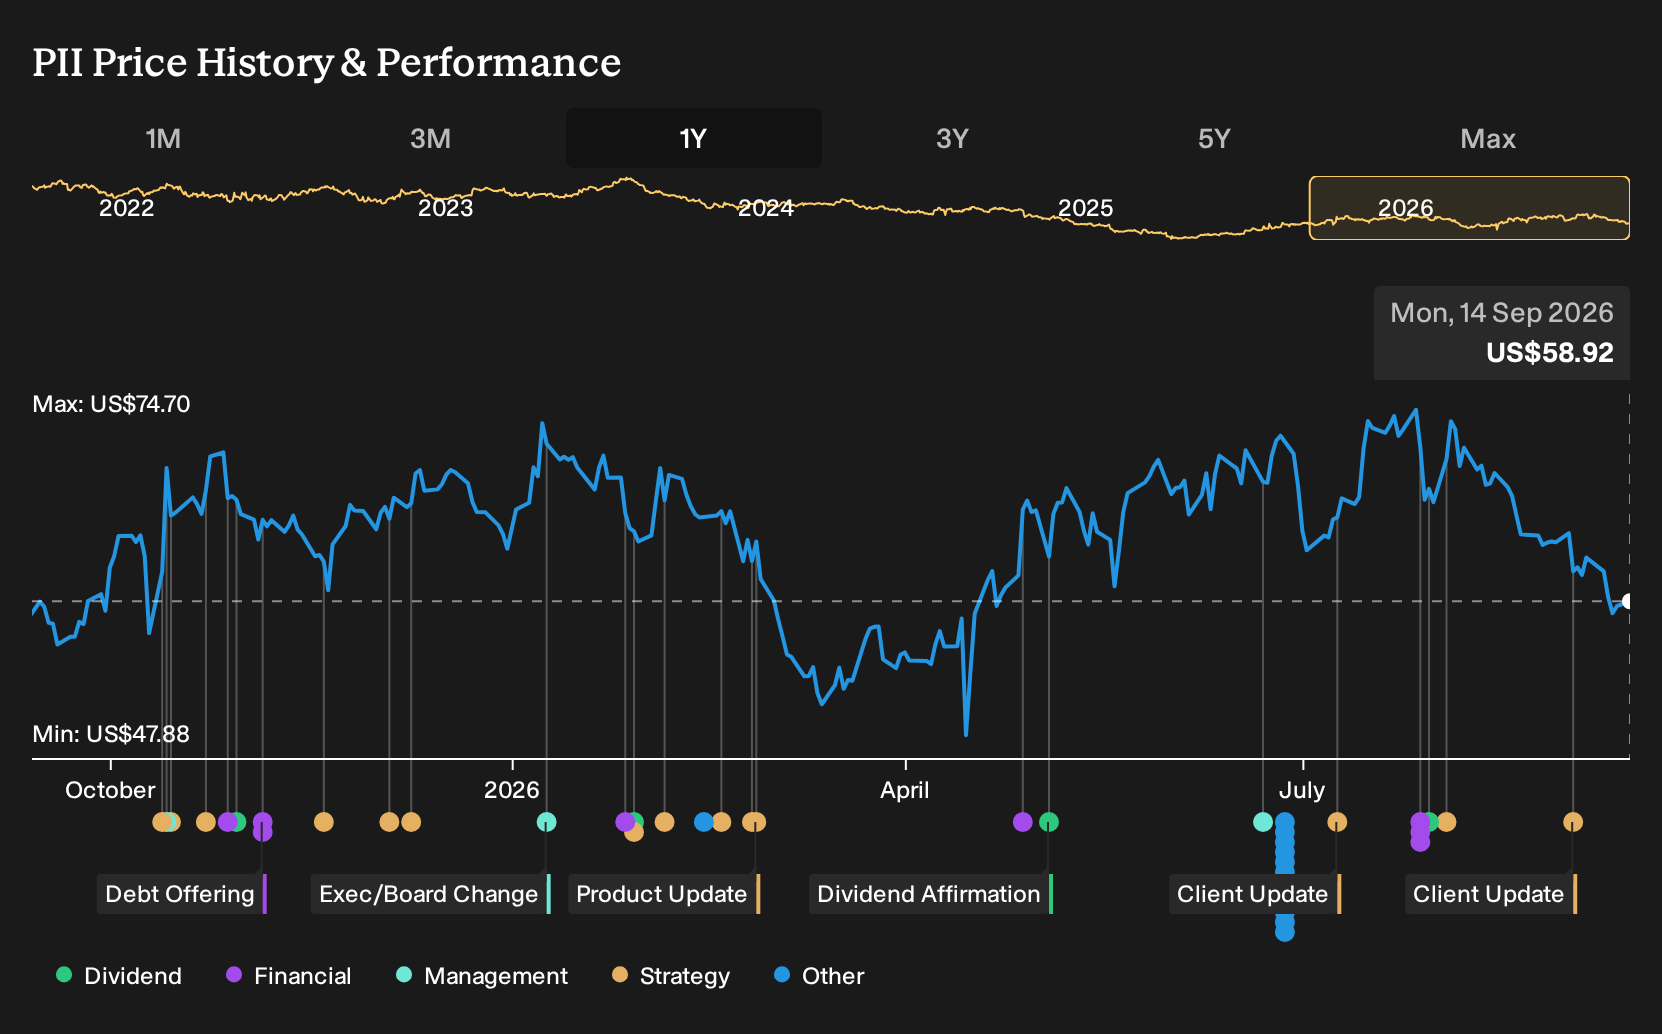
Exploring Other Perspectives
One alternate angle on Polaris focuses on tariff and electrification risk rather than marketing upside. The most cautious analysts were penciling in just 1.5% yearly revenue growth and about US$352.7m in earnings by 2029. That is meaningfully below the consensus path and leaves plenty of room for views to shift once this Monster Energy promotion is fully digested.
Explore 2 other Polaris fair value estimates, including one that suggests it could be worth just $70.19!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Polaris research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Polaris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Polaris' overall financial health at a glance.
Looking for more Polaris investment ideas?
If the Monster Energy promotion has put Polaris on your radar, it can be useful to widen the lens and compare it with other listed businesses that share similar qualities or offer a different risk and income profile. The Simply Wall St Screener helps you filter for companies that fit the kind of portfolio you want to build, rather than chasing the loudest headline.
- For investors who want stronger quality at a discount, start with a focused group of 35 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them yet.
- If capital preservation is a priority, narrow your watchlist to a curated pool of 11 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- For income seekers, target a stream of cash returns from 6 dividend fortresses that combine higher yields with businesses screened for resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com