
Nippn (TSE:2001) Earnings Beat Keeps Its Valuation Debate Alive
Nippn (TSE:2001) has drawn attention after its latest share price move, with the stock most recently closing at ¥2,994. Investors are weighing this price against the group’s earnings profile and its balance between flour milling and processed foods.
Recent trading has been mildly choppy, with a small 1-day share price decline offset by a 7-day gain of 1.42%. A 30-day share price return of 4.36% and a 90-day move of 13.58% point to building momentum that aligns with a year-to-date share price return of 24.23% and a 1-year total shareholder return of 29.78%.
Scan beyond Nippn and line up other potential momentum stories using our curated list of 18 high quality undervalued stocks, which pair earnings strength with balance sheet support.
Nippn now trades at a sizeable discount to one implied fair value estimate, despite its solid long term shareholder returns. Is that discount a margin of safety, or a warning the market is taking seriously?
Most Popular Narrative: 13% Overvalued
Nippn last closed at ¥2,994 against a narrative fair value of ¥2,648, so the story many investors are watching frames the current level as richer than that implied benchmark.
FY3/26 results were ahead of guidance, driven by efficiency gains at the Flour Milling segment. The Food segment saw growth, but profitability was impacted by cost pressures. We continue to think the segment could deliver meaningful earnings growth if costs stabilize. Importantly, further production efficiency gains are ahead, as NIPPN’s new Chita Mill commenced operations in February 2026. As NIPPN’s record pipeline of strategic capex projects comes online over the next few years, we think the trend of incremental efficiency gains is likely to continue, although tempered by higher depreciation charges. Furthermore, NIPPN’s commitment to optimizing its capital structure, as evidenced by FY3/26, and to reducing cross-shareholdings should drive incremental earnings growth.
See why 1 investors see Nippn as 13% overvalued.
Result: Fair Value of ¥2,648 (OVERVALUED)
Still, this story can turn quickly if Food segment cost pressures persist or if heavier depreciation from recent capex weighs more than expected on earnings.
Find out about the key risks to this Nippn narrative.
Another View On Nippn’s Valuation
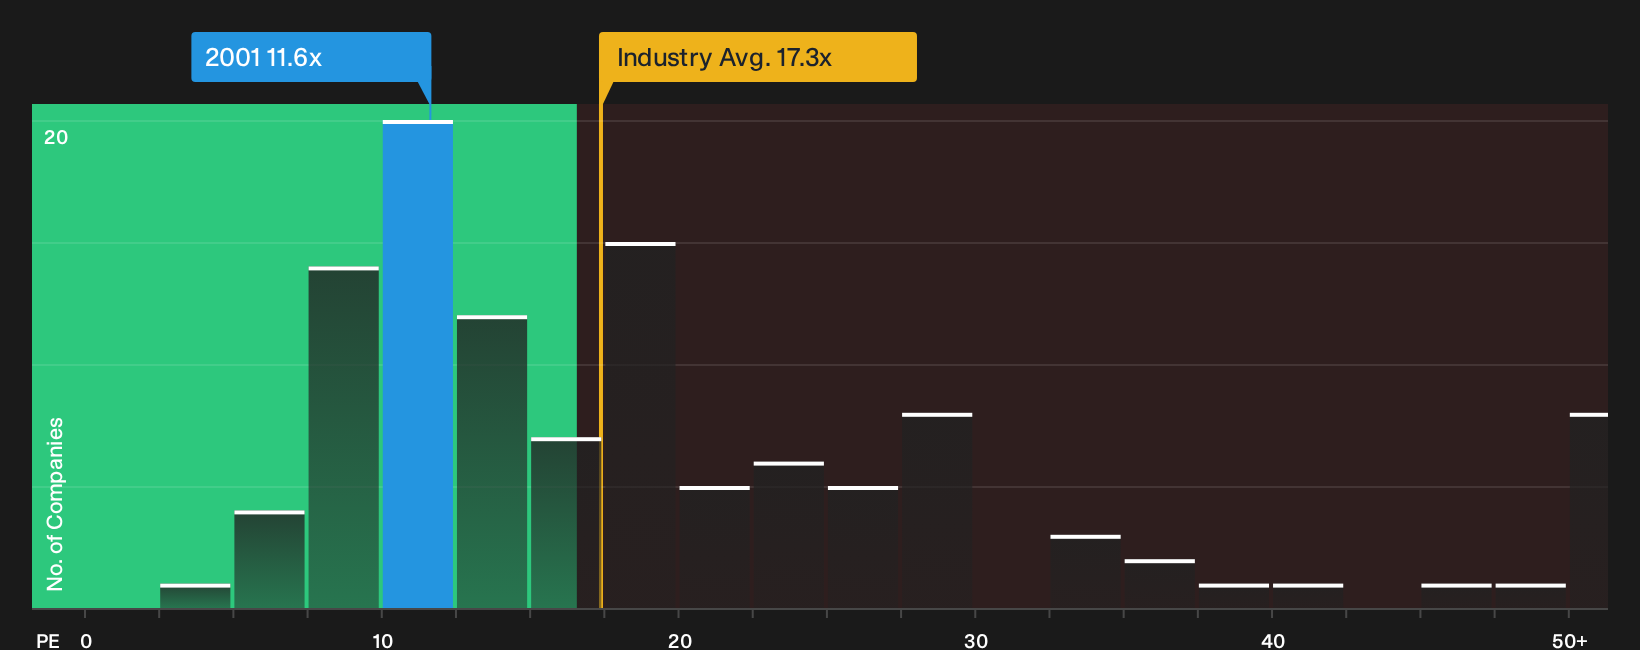
That fair value story based on narrative inputs and future assumptions presents a very different picture when looking at plain earnings multiples. On a P/E of 11.6x, Nippn trades below the JP Food industry on 17.3x, below a peer average of 12.7x, and below an estimated fair ratio of 13.2x.
Those gaps indicate that, on simple earnings terms, the share price reflects more caution than the sector and even the fair ratio suggest. Yet the earlier narrative still frames the stock as 13% overvalued. Which lens do you think better reflects the risk you are actually taking?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution around Nippn feels finely balanced, move quickly. Review the key data for yourself and weigh both sides of the story. To see the full breakdown of risks flagged by investors alongside the potential upsides they are watching, start with 3 key rewards and 3 important warning signs.
Looking for more Nippn investment ideas?
If Nippn has sharpened your focus on valuation and risk, do not stop here. Fresh ideas often come from comparing very different types of opportunities.
Use the Simply Wall St screener to widen your opportunity set and avoid missing stocks that quietly fit your checklist.
- Target dependable income streams by reviewing companies that qualify as 17 dividend fortresses and see which payouts line up with your goals.
- Hunt for mispriced quality by scanning the 74 high quality undiscovered gems that pair fundamentals with quieter market attention.
- Prioritise resilience by focusing on businesses in the 12 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com