
Bandwidth (BAND) Could Be 26% Undervalued After Salesforce AI Contact Center Expansion
Bandwidth (BAND) is back in focus after expanding its collaboration with Salesforce, becoming the first certified carrier for the CRM giant’s AI-powered Contact Center as it rolls out across more than 25 international markets.
Recent trading has been choppy for Bandwidth, with the share price up 2.27% on the day and 14.81% over the past week, yet still down 7.21% across 30 days and 1.49% over 90 days. The year-to-date share price return of 252.18% and 3-year total shareholder return of 306.49% indicate strong longer term momentum that this Salesforce expansion appears to have re-energised.
Scan for other AI infrastructure plays moving on real enterprise deals by checking out the hand picked 60 AI infrastructure stocks alongside Bandwidth.
Bulls see Bandwidth’s Salesforce role and rapid earnings growth as proof the rerating has room to run. Bears point to a 5 year share price decline and rich expectations. Which side does the current valuation support?
Most Popular Narrative: 26% Undervalued
Against a last close of $50.08, the most followed narrative pegs Bandwidth’s fair value at $67.25, which frames the current debate around whether the Salesforce-driven excitement already sits in the price or not.
Accelerating enterprise adoption of AI-powered voice applications, driven by Bandwidth's Maestro platform and integrations, is already delivering a 3x-4x uplift in revenue per call for AI-enabled use cases, and is expected to further increase platform usage, ARPU, and gross margin as more enterprises embed AI into customer workflows.
See why 10 investors see Bandwidth as 26% undervalued.
Result: Fair Value of $67.25 (UNDERVALUED)
Still, Bandwidth’s heavy reliance on Maestro and a concentrated enterprise customer base could quickly pressure revenue and margins if AI adoption slows or if contract renewals slow.
Find out about the key risks to this Bandwidth narrative.
Another View on Bandwidth’s Valuation
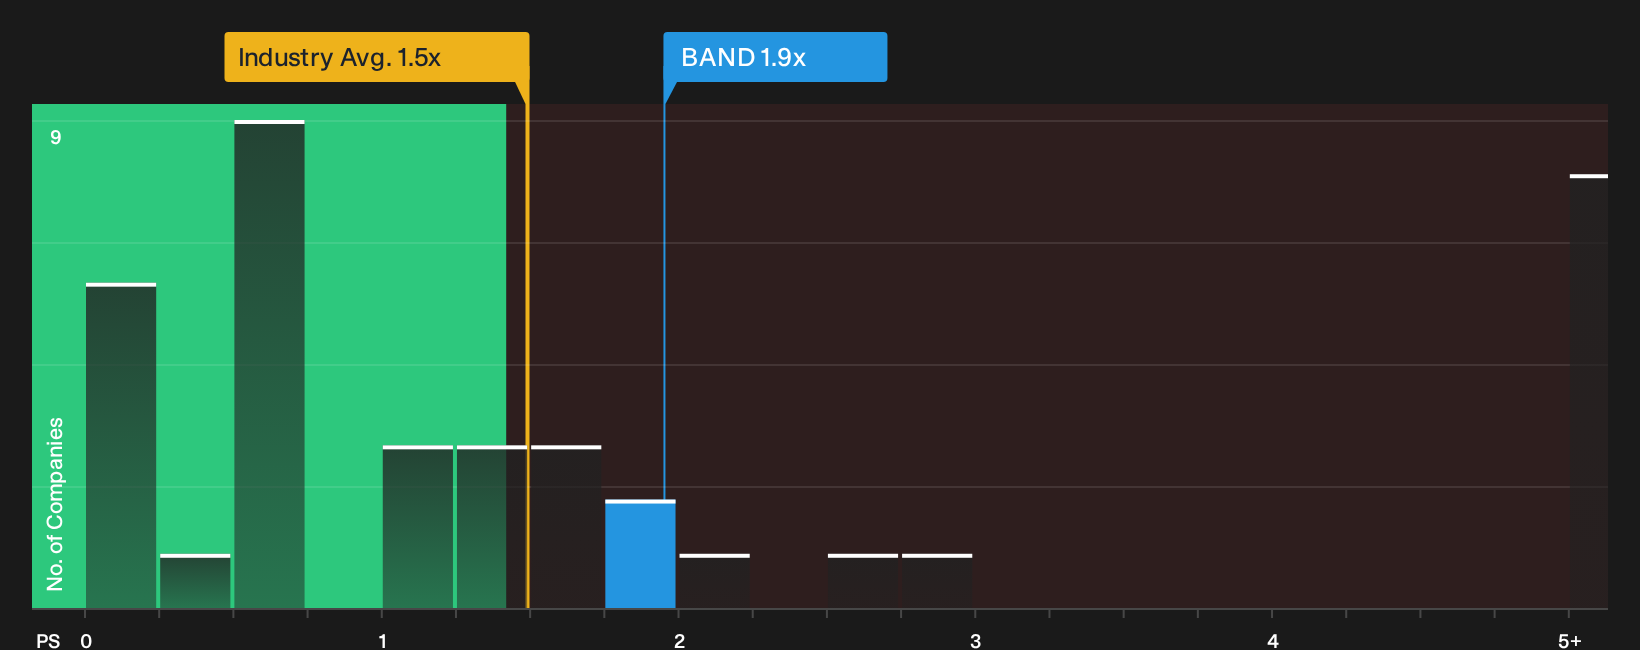
The first take argues Bandwidth looks attractive based on its future cash flows, with the stock trading 73.3% below an internal estimate of future cash flow value at $187.60. A very different signal comes from the P/S lens, where the current 1.9x ratio sits above the 1.2x fair ratio and the 1.5x US Telecom industry average, which suggests less room for error if growth or margins disappoint. Which yardstick do you trust more when real money is on the line?
To see how that 1.9x P/S could converge toward the 1.2x fair ratio or move closer to peers, check the valuation breakdown next See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Bandwidth’s story so far. Act while sentiment is split, and weigh the potential upside against the concerns by reviewing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Bandwidth?
If you stop with Bandwidth, you cap your opportunity set. Use the Simply Wall Street Screener to line up fresh ideas before the crowd gets there.
- Target potential mispricings by scanning a curated 35 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Strengthen portfolio resilience by reviewing a 11 resilient stocks with low risk scores focused on companies with steadier fundamentals and lower risk profiles.
- Hunt for early opportunities in a 15 high quality undiscovered gems that highlights lesser known stocks with strong underlying numbers before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com