
Did Contract Extension Just Shift Vossloh Stock's Investment Narrative?
- Vossloh Aktiengesellschaft reported that DB InfraGO has extended its framework agreement for preventive rail maintenance by one year, covering around 40,000 kilometers of Deutsche Bahn track using High Speed Grinding technology and linked digital measurement services.
- The renewal highlights how Vossloh’s rail machining and in-house digital tools, from crack detection to automated planning, are directly aligned with customers’ priorities, including capacity, noise reduction and asset life.
- This article now examines how Vossloh’s extended DB InfraGO maintenance contract shapes the broader investment narrative around its rail infrastructure services.
Scan how Vossloh’s rail maintenance contract fits into a wider push for resilient infrastructure stocks by comparing it with 38 power grid technology and infrastructure stocks shaping the future of high-capacity transport networks.
What Is Vossloh's Investment Narrative?
For Vossloh, the big-picture belief is simple. You have to think that rail infrastructure spending stays resilient and that rail operators keep paying for preventative maintenance and digital tools that reduce downtime. The extended DB InfraGO deal points in that direction. It validates demand for Vossloh’s Lifecycle Solutions segment, where High Speed Grinding and measurement services turn heavy capital assets into recurring work rather than one-off projects.
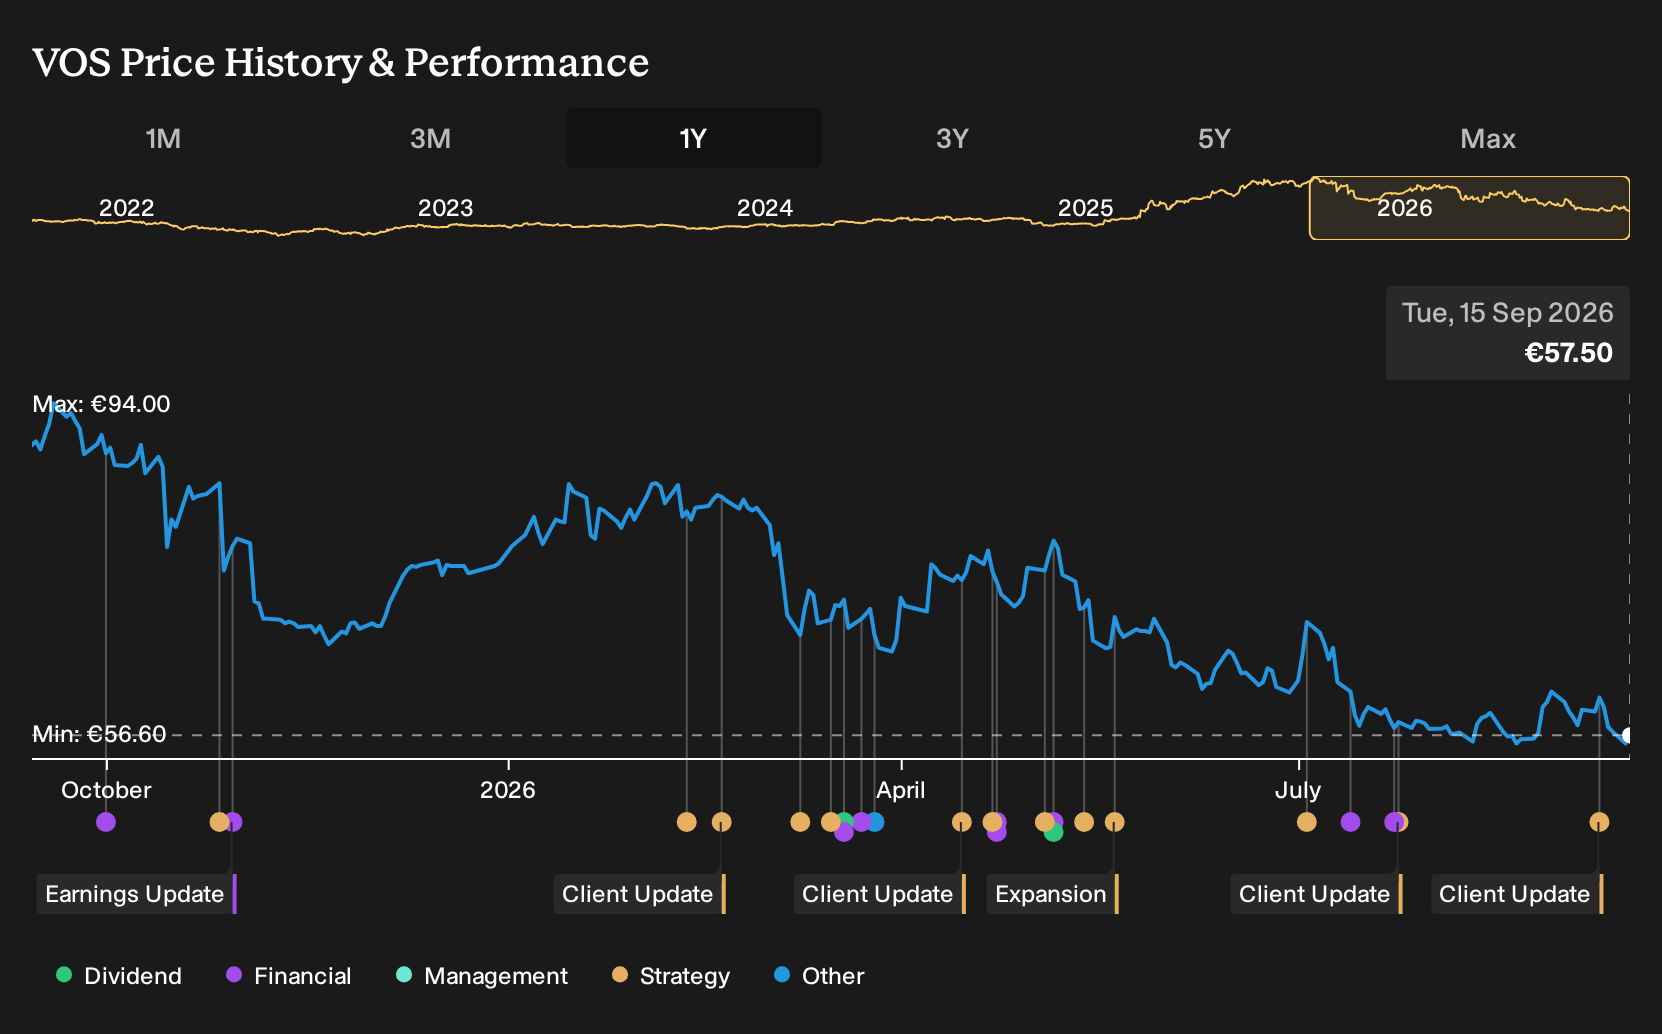
In the short term, this contract extension supports visibility on utilization and pricing for those services. That matters when the stock has fallen 34% over the past year and trades on a P/E of 31.1x. The flip side is that profit margins have recently compressed to 2.4%, interest costs are not comfortably covered by earnings, and returns on equity remain low. The DB InfraGO win helps the story on operations and demand, but it does not fully solve the toughest financial pressure points.
Yet there is a less obvious pressure point that could become far more important if ...
There's only one way to know the right time to buy, sell or hold Vossloh. Head to Simply Wall St's company report for the latest analysis of Vossloh's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between €78.14 and €110.35, so private investors are already assigning a wide possible range for Vossloh. Those views were formed before the DB InfraGO extension, which could shift expectations on contract quality and prompt you to compare several alternative viewpoints.
Explore another Vossloh fair value estimate, including one that suggests there may be up to 92% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vossloh research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vossloh. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Vossloh's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vossloh?
Once you have a view on Vossloh, it can help to widen the lens and see how other businesses stack up on income potential, value, and balance sheet strength using the Simply Wall St Screener.
- If income is your focus, scan for companies that pair higher yields with resilient payouts through our 163 dividend fortresses.
- If value and quality matter most, compare Vossloh with a broader set of financially robust opportunities using the 193 high quality undervalued stocks.
- If capital preservation comes first for you, narrow the field to companies with sturdier finances by checking the 102 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com