
Is Akeso (SEHK:9926) Undervalued On New Ivonescimab Survival Data?
Akeso (SEHK:9926) is back in focus after presenting new overall survival data from its Phase III HARMONi-2 trial of ivonescimab versus pembrolizumab in first-line PD-L1-positive non-small cell lung cancer at WCLC 2026.
Akeso’s HK$95.25 share price has drifted lower over the year to date with a decline of 15.93%, yet a 13.53% 3 month share price return and a 3 year total shareholder return of 151.98% suggest long term holders have still seen strong gains as sentiment oscillates around each new ivonescimab milestone and shifting perceptions of risk and opportunity.
Scan how Akeso’s latest ivonescimab data compares with other oncology-focused opportunities by reviewing a curated set of 624 high quality undiscovered gems in the same wider theme.
Akeso’s shares have pulled back over the past year even as ivonescimab’s survival data strengthened, which puts you at a fork in the road. Is this the moment to commit, or does patience on price still make more sense as the numbers stack up next?
Most Popular Narrative: 40% Undervalued
Akeso’s most followed valuation storyline points to a fair value of HK$158.28 against the recent close of HK$95.25. This view places a lot of weight on how its pipeline and partnerships translate into future cash generation.
The collaboration with SUMMIT Therapeutics and the partnership with Pfizer to combine ivonescimab with Pfizer's ADCs suggests expansion into new therapeutic areas and geographic markets, promising to impact earnings positively.
The company's strong R&D pipeline, including advanced bispecific antibodies and ADC candidates, provides a foundation for long-term growth, setting the stage for potential increases in net margins as products move from development to commercialization.
See why 3 investors see Akeso as 40% undervalued.
On this view, Akeso is treated as a high growth oncology platform where heavy current losses are considered a trade off for a larger earnings base later. The framework uses a 7.45% discount rate and assumes revenue expansion of 50.62% per year with profit margins eventually reaching 31.18%, which together support a future return on equity forecast of 23.8% in three years.
Those inputs feed into a projected earnings figure of CN¥3.7b by around 2029 and a future P/E multiple of 42.2x, above the current 19.9x level for the wider Hong Kong biotech group. The gap between Akeso’s current share price and the HK$158.28 fair value estimate therefore hinges on whether you think that growth path and profitability shift are realistic given the HARMONi trial data, NRDL pricing decisions and the reliance on a few key immuno oncology assets.
Result: Fair Value of HK$158.28 (UNDERVALUED)
Still, Akeso’s reliance on a handful of key drugs and its current CN¥967.2m net loss mean that any clinical or pricing setback could quickly challenge this undervaluation story.
Find out about the key risks to this Akeso narrative.
Another View: What Akeso’s Sales Multiple Is Telling You
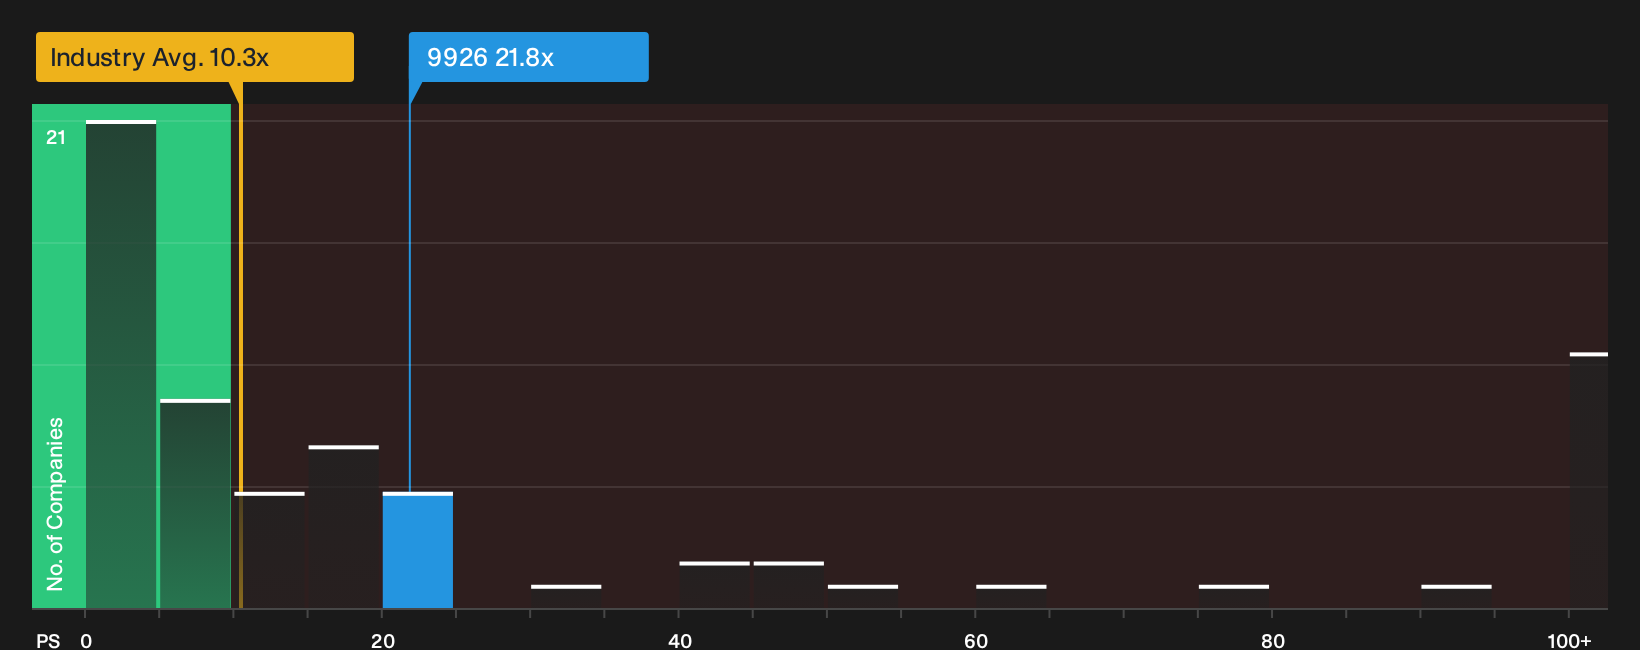
The SWS fair ratio for Akeso’s P/S is 13.3x, while the stock changes hands at 21.8x. That level is below a 29.2x peer average, yet well above where the fair ratio suggests the market could drift over time. Does that premium feel like upside or valuation risk to you?
To see how this sales based view lines up against detailed earnings assumptions and future cash flow scenarios, take a closer look at the valuation breakdown in our full model, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Akeso is split, which is exactly when fresh data can help most. Move quickly, review the full picture and weigh the 2 key rewards.
Looking for more Akeso sized investment ideas?
Do not stop with Akeso when there are other opportunities that could fit your style just as well. Use the screeners below to pressure test your next move.
- Target resilient compounding potential by focusing on businesses trading below their indicated value through the 193 high quality undervalued stocks.
- Prioritise staying power and balance sheet strength by scanning the list of solid balance sheet and fundamentals (196 results) before committing fresh capital.
- Reduce downside shocks and keep your portfolio steadier across cycles by filtering companies with the 102 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com