
Lowe's (LOW) Stock Looks Undervalued On Its 27% One Year Fall
Lowe's Companies shares have retreated sharply over the past year, which puts fresh focus on whether the current US$194.61 price matches the cash the business is expected to generate. With the stock coming off a multi year stretch of weaker performance, the valuation discussion now revolves around its cash flows rather than headline momentum.
- The share price has fallen 26.6% over the past year. This raises the question of whether the market has reset expectations for Lowe's cash generation too far or not far enough.
- The retailer relies on converting home improvement demand into steady operating cash flow, so any change in pricing power, store productivity or capital spending can shift what investors are willing to pay today for those future streams.
- What if you looked at Lowe's Companies through its earnings instead? See what Lowe's Companies's 16.5x P/E says about the price.
The issue now is whether Lowe's Companies current share price is adequately supported by its intrinsic value estimate based on projected cash flows.
If you are reassessing Lowe's Companies through the lens of its cash flows, it can help to compare it with a focused list of other businesses screened for 34 high quality undervalued stocks
Is Lowe's Companies a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Lowe's Companies can return to shareholders over time. Latest twelve month free cash flow sits around $7.0b, which gives the analysis a solid cash base rather than a story built on projected earnings alone. In addition, the model assumes growing free cash flow over the coming decade rather than a permanent plateau or decline, reflecting expectations of a business that can still expand its cash generation.
Those projections, when discounted back, produce an intrinsic value estimate that comes out modestly above the current $194.61 share price. For a mature retailer like Lowe's Companies, a DCF outcome that is only modestly ahead of the market quotation suggests expectations for future cash flow are neither extremely conservative nor aggressively optimistic. The full valuation detail, including the implied intrinsic worth per share, sits in the model output you can review here. Find out what Lowe's Companies could be worth using our Discounted Cash Flow (DCF) estimate.
The Lowe's Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation work on Lowe's Companies leaves off and explain which future paths for growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than it is today, using the Community page as the home base. Each narrative links its number to a clear view on how Lowe's Companies' revenues, margins and key risks might evolve, so you can revisit those assumptions as fresh information comes through.
One of the top community narratives on Lowe's Companies: 24% undervalued
"Lowe’s is accelerating its shift toward professional contractors while strengthening its Total Home strategy for DIY and “Do It For Me” customers…”
Discover why this Narrative puts Lowe's Companies at 24% undervalued.
One more factor to weigh before making a call on Lowe's Companies
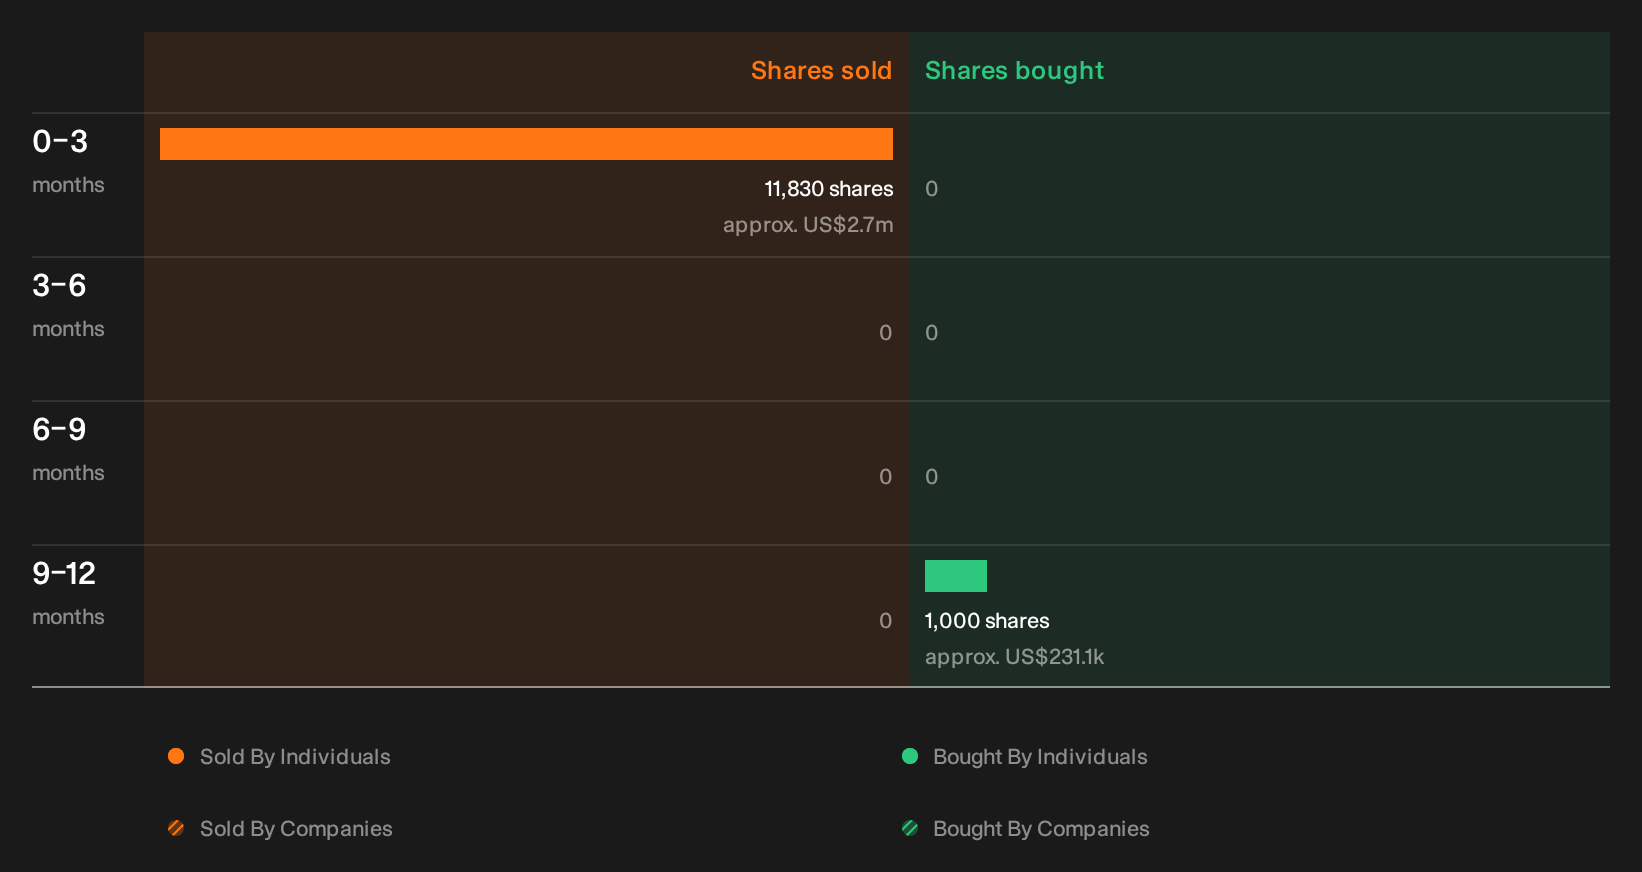
There is one more piece of the Lowe's Companies puzzle that the valuation work does not cover, which is the pattern of recent insider share sales and what those moves might signal for current shareholders. See the recent insider selling flagged for Lowe's Companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com