
Is SELLAS Life Sciences Group (SLS) Reasonable Or Stretched On Book Value?
SELLAS Life Sciences Group has delivered very strong multi year share price gains, yet the recent pullback raises a simple question for investors: Is the current US$11.29 price still in line with what the business is worth based on its book value?
- Over the past 3 years, SELLAS Life Sciences Group has delivered a share price return of about 6.5x, which puts real weight on whether the underlying balance sheet justifies that move.
- Fresh preclinical data on SLS009 in pancreatic ductal adenocarcinoma may support expectations for future research and development spending, which can influence how much value investors place on the company’s current equity base.
- The analysts covering SELLAS Life Sciences Group have run their own numbers. See what analysts think SELLAS Life Sciences Group's shares could be worth.
The issue now is whether SELLAS Life Sciences Group's current share price is adequately supported by its book value compared with the industry average.
If you want a broader starting point for research alongside SELLAS Life Sciences Group, you can apply the same book value lens to a wider set of companies using the 34 high quality undervalued stocks.
Has SELLAS Life Sciences Group Run Too Far on Book Value?
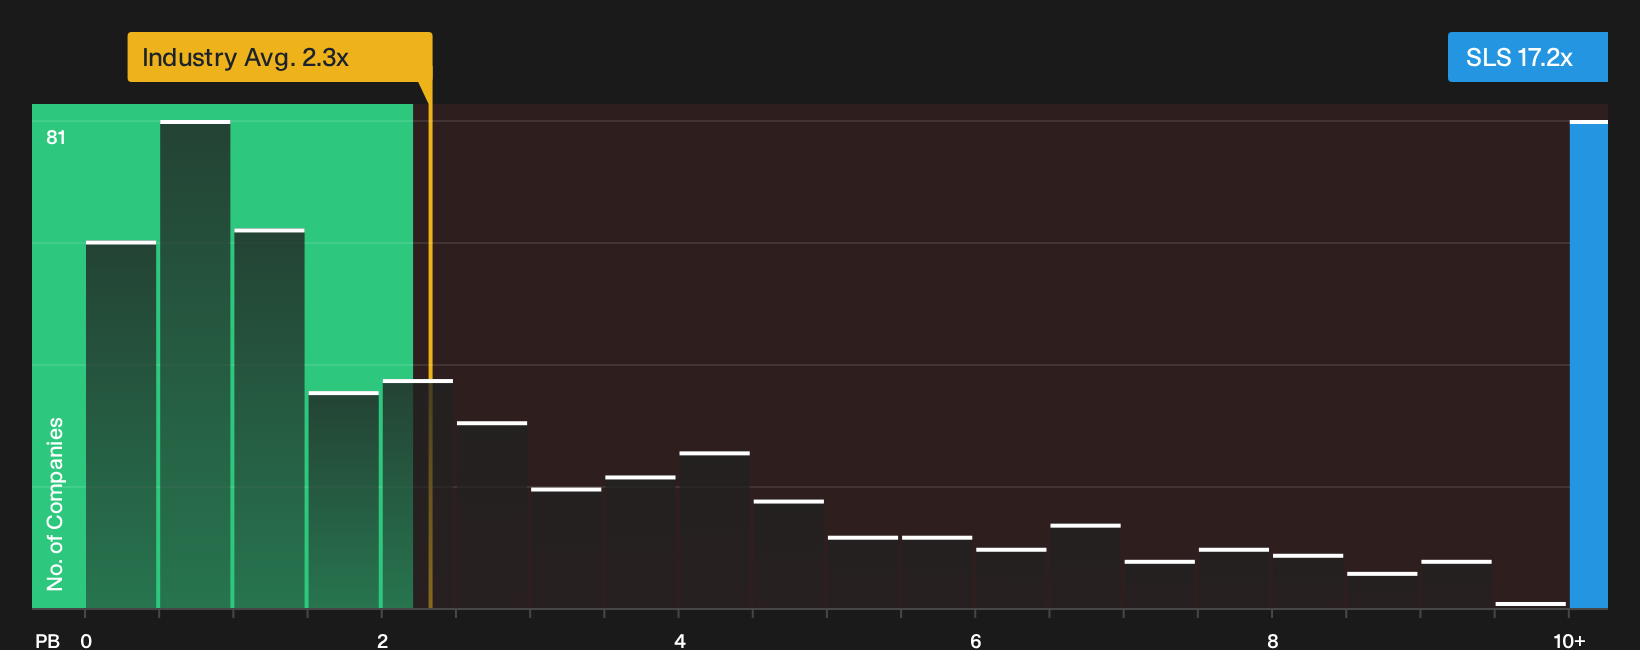
P/B is a useful lens for SELLAS Life Sciences Group because investors are heavily focused on the value of its equity base while the business is still in a research focused phase. At a P/B of about 16.6x, the stock trades at a much higher level than the broader Biotechs industry average of roughly 2.3x and also above the peer group average near 5.0x. That gap means each dollar of SELLAS Life Sciences Group's book value is currently being valued far more highly than the typical biotech peer.
Because the model heavily penalises the company’s losses and risk profile, this wide premium is best read as a warning signal that SELLAS Life Sciences Group appears very expensive on a simple balance sheet multiple, not as a precise fair value target. Despite the upcoming AACR presentations on SLS009, which may support interest in the story, the present P/B level already reflects a rich valuation relative to both the sector and closer peers. Explore the numbers behind SELLAS Life Sciences Group's P/B valuation.
The SELLAS Life Sciences Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for SELLAS Life Sciences Group pick up where the book value puzzle leaves off by explaining which potential future paths for growth, margins, and earnings would need to occur for the stock to appear meaningfully higher or lower than today’s price. Each Narrative treats SELLAS Life Sciences Group's estimated worth as a thesis about the business that can be tracked over time, rather than as a static one-off number found on Simply Wall St’s Community page.
A written, number driven view on SELLAS Life Sciences Group creates a clear baseline that forces every assumption into the open and makes it easier to update as new information arrives. With fresh SLS009 pancreatic ductal adenocarcinoma data heading to the AACR conference, a structured narrative also gives you a reference point for judging whether those results, and any follow up decisions on research spending, line up with the expectations reflected in today’s valuation.
Share your own Narrative for SELLAS Life Sciences Group and set out the assumptions behind your valuation.
One crucial piece of the SELLAS Life Sciences Group puzzle is still missing
Valuation only tells you what the market is paying today, while the real story also depends on who is steering SELLAS Life Sciences Group and how those leaders are rewarded for the results they deliver. See who runs SELLAS Life Sciences Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com