
Electro Optic Systems Holdings (ASX:EOS) Just Gave Investors Something To Think About
Electro Optic Systems Holdings (ASX:EOS) moved into focus after presenting its Apollo laser system at MSPO 2026. The company showcased AI driven counter drone technology within the NiDAR suite to address growing unmanned aerial threat concerns.
For investors watching Electro Optic Systems Holdings over the past year, the MSPO 2026 spotlight lands on a stock that has already seen a very large 3 year total shareholder return of about 7x and a 1 year total shareholder return of 28.73%, even as the year to date share price return has declined 7.24% and shorter term moves remain mixed. The 30 day share price return of 8.97% sits alongside some recent weekly softness that suggests momentum may be consolidating rather than accelerating at the current A$9.23 level.
Scan beyond Electro Optic Systems Holdings and line up other defense and security plays using our hand picked 38 robotics and automation stocks that are also leaning on AI and automation for an edge.
After a 7x three-year run and a 28.73% one-year total return, Electro Optic Systems Holdings now sits at A$9.23. Is the real upside still ahead, or was Apollo the fireworks finale before valuation catches up?
Most Popular Narrative: 34% Undervalued
Analysts following Electro Optic Systems Holdings see a wide gap between their A$14.04 fair value view and the A$9.23 last close, hinging on aggressive revenue and margin assumptions that investors need to judge for themselves.
There is an expectation that rapid adoption of autonomous and unmanned defense solutions will drive ongoing revenue and order book expansion. However, failure to achieve broad commercial adoption or delays in customer procurement cycles could create future top-line volatility and impair long-term earnings predictability.
See why 47 investors see Electro Optic Systems Holdings as 34% undervalued.
Result: Fair Value of A$14.04 (UNDERVALUED)
Still, the bullish case for Electro Optic Systems Holdings could unravel if defence budgets reset or rival contractors crowd the counter drone and laser segment more quickly than expected.
Find out about the key risks to this Electro Optic Systems Holdings narrative.
Another Take On Electro Optic Systems Holdings Valuation
The fair value narrative built around analyst targets points to Electro Optic Systems Holdings trading below an implied A$14.04. A different tool tells a very different story. The SWS DCF model estimates future cash flows support a value closer to A$2.57, which suggests the current A$9.23 price screens as expensive, not cheap.
That kind of gap between a discounted cash flow view and an earnings based target raises a practical question for any holder. Which set of assumptions feels closer to what you think Electro Optic Systems Holdings can actually deliver over time?
Look into how the SWS DCF model arrives at its fair value.
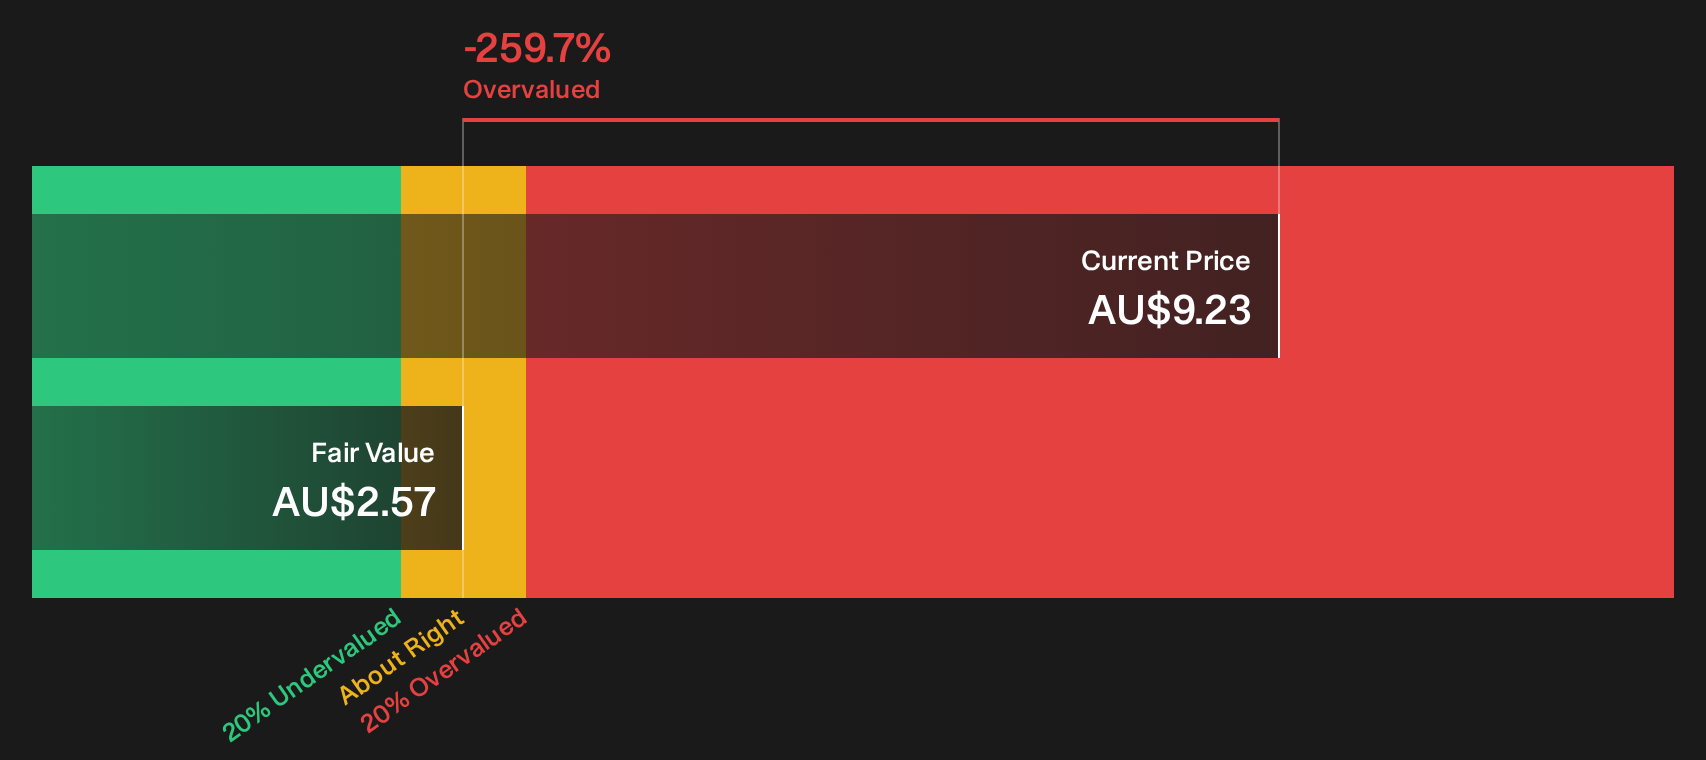
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Electro Optic Systems Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the enthusiasm around Electro Optic Systems Holdings matches your own view of the risk and reward trade off here? Move quickly, stress test the assumptions that matter most to you, then weigh them against the 2 key rewards.
Looking for more investment ideas beyond Electro Optic Systems Holdings?
If Electro Optic Systems Holdings has sharpened your focus on risk, reward and valuation, do not stop here. The right watchlist often starts with a few strong alternatives that fit your own preferences for quality, income or lower volatility.
- Target steadier compounding by reviewing companies with robust finances and clean balance sheets using the list of solid balance sheet and fundamentals (12 results).
- Hunt for mispriced opportunities by scanning the 5 high quality undervalued stocks that combine strong fundamentals with room for sentiment to catch up.
- Build a cash flow anchor for your portfolio through the 4 dividend fortresses that aim to pair higher yields with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com