
Twim (KOSDAQ:290090) Is In A Good Position To Deliver On Growth Plans
We can readily understand why investors are attracted to unprofitable companies. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
So, the natural question for Twim (KOSDAQ:290090) shareholders is whether they should be concerned by its rate of cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. Let's start with an examination of the business' cash, relative to its cash burn.
When Might Twim Run Out Of Money?
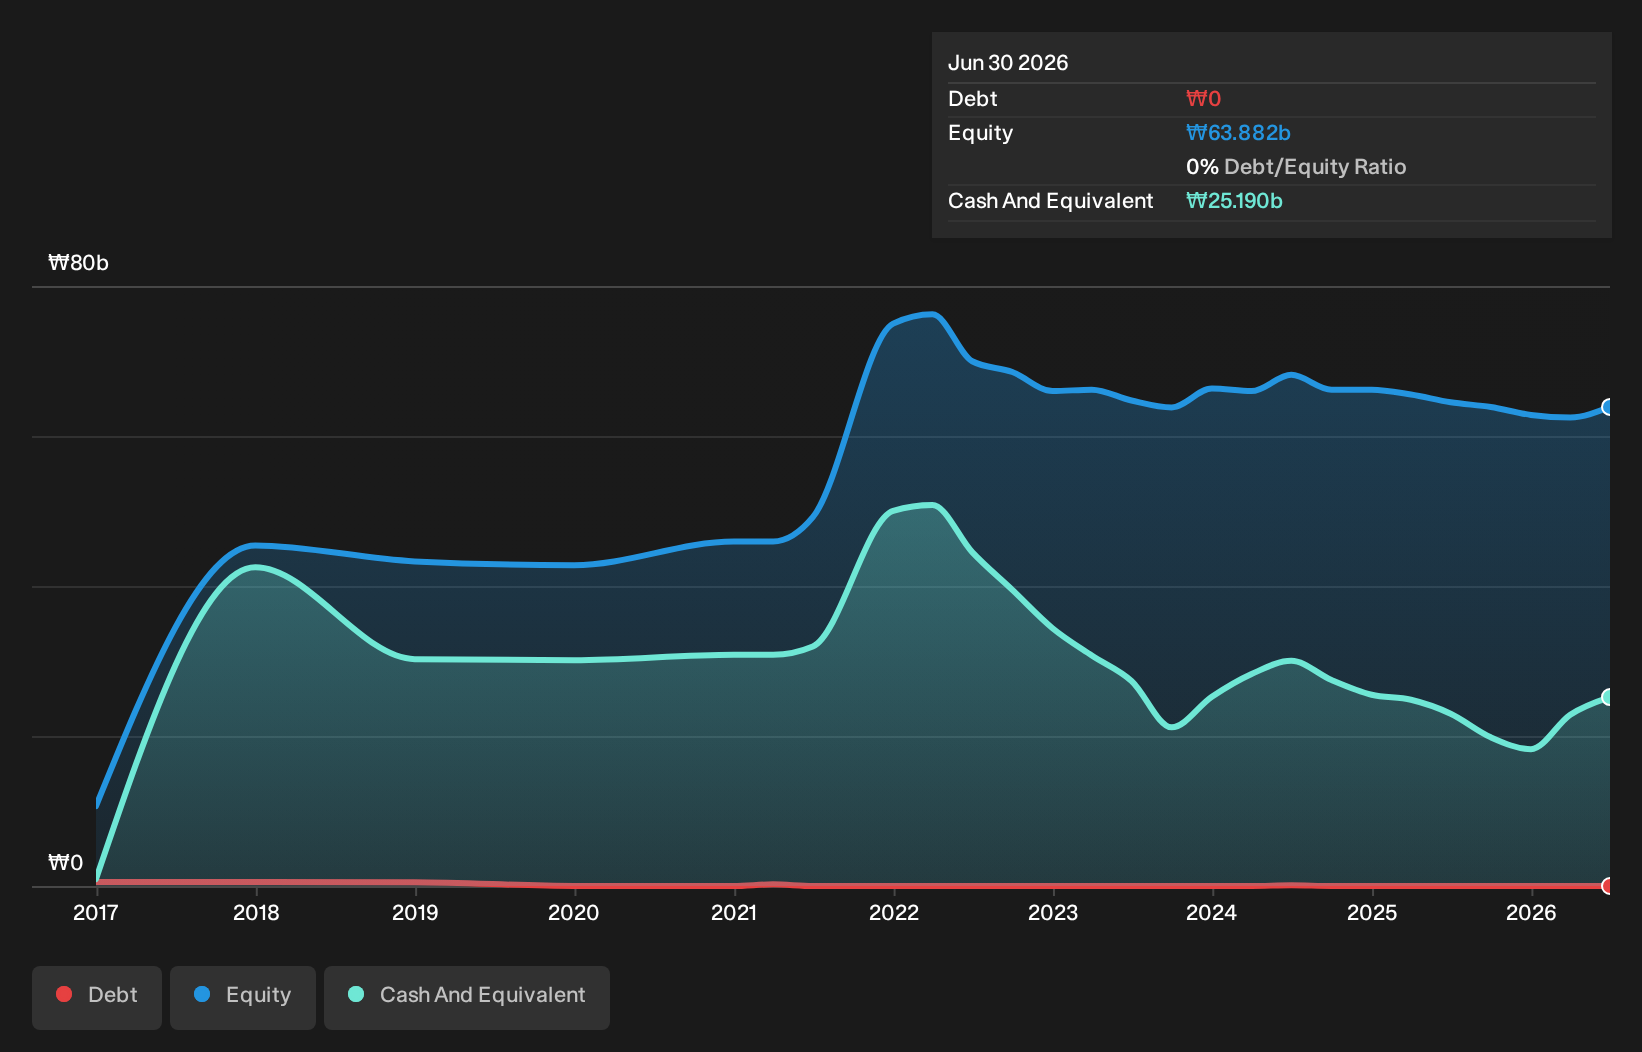
A company's cash runway is calculated by dividing its cash hoard by its cash burn. As at June 2026, Twim had cash of ₩25b and no debt. Looking at the last year, the company burnt through ₩1.7b. That means it had a cash runway of very many years as of June 2026. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. The image below shows how its cash balance has been changing over the last few years.
View our latest analysis for Twim
How Well Is Twim Growing?
We reckon the fact that Twim managed to shrink its cash burn by 51% over the last year is rather encouraging. Unfortunately, however, operating revenue declined by 25% during the period. On balance, we'd say the company is improving over time. In reality, this article only makes a short study of the company's growth data. You can take a look at how Twim has developed its business over time by checking this visualization of its revenue and earnings history.
How Easily Can Twim Raise Cash?
While Twim seems to be in a decent position, we reckon it is still worth thinking about how easily it could raise more cash, if that proved desirable. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Twim has a market capitalisation of ₩33b and burnt through ₩1.7b last year, which is 5.0% of the company's market value. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
Is Twim's Cash Burn A Worry?
As you can probably tell by now, we're not too worried about Twim's cash burn. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. While its falling revenue wasn't great, the other factors mentioned in this article more than make up for weakness on that measure. Looking at all the measures in this article, together, we're not worried about its rate of cash burn; the company seems well on top of its medium-term spending needs. Taking a deeper dive, we've spotted 2 warning signs for Twim you should be aware of, and 1 of them makes us a bit uncomfortable.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.