
Nvidia Pushback Keeps AI Hardware Stocks In Focus
AI infrastructure is being built at full speed, and Jensen Huang’s pushback against fresh US rules signals that this race is not pausing. For investors, that kind of conviction from Nvidia’s leadership can create a fear of missing the next leg of spending on chips, servers, and power hungry data centers. This article explains how that backdrop affects three AI hardware stocks exposed to this news and what that might mean for your watchlist.
The stocks highlighted below are only a small sample. The full screen surfaced 59 more companies with similarly detailed AI hardware narratives that are not covered here. If you want to move quickly from headlines to hard data, head straight into the AI Infrastructure Enablers (AI Chips and Data Center Hardware) screener to identify, compare, and analyze the AI infrastructure enablers that best fit your own thesis.
Tower Semiconductor (TSEM)
Tower Semiconductor is one of the purest ways in this screen to play the nuts and bolts of AI infrastructure, since its foundry lines focus on the mixed signal and photonics chips that help GPUs, servers, and data center hardware actually talk to each other.
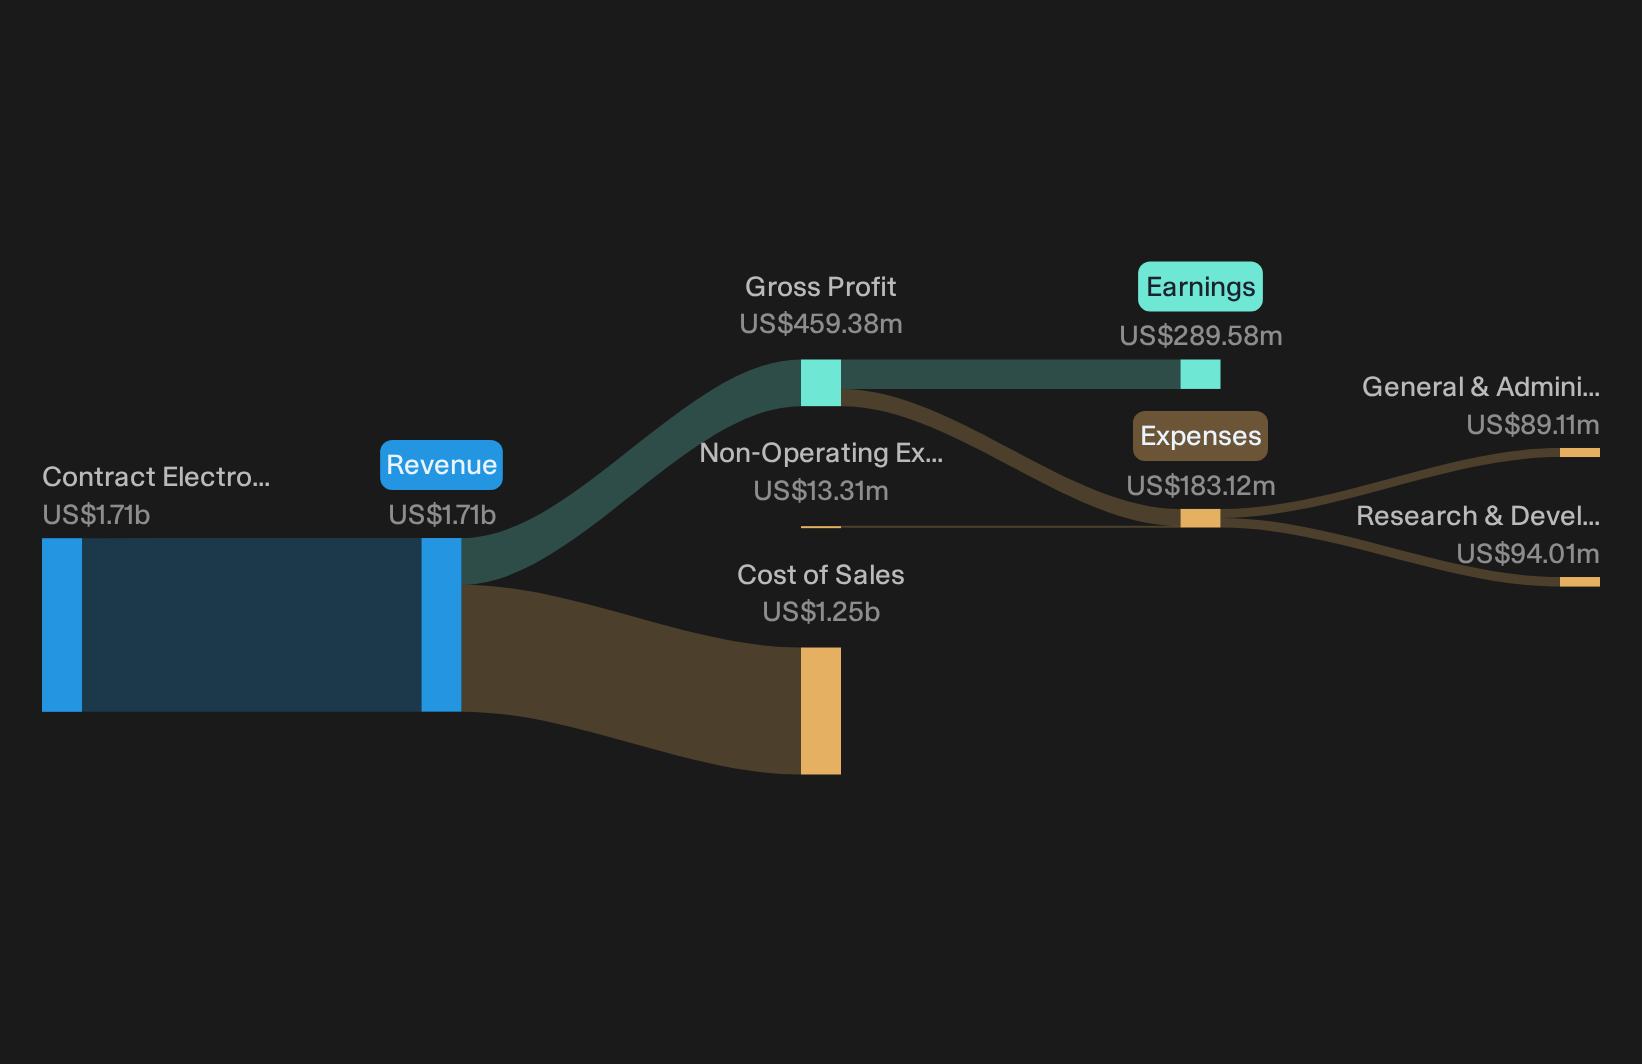
Tower Semiconductor Ltd., an independent foundry, manufactures integrated circuits that underpin AI data centers and networking hardware, with all reported revenue of about US$1.7b coming from contract electronics manufacturing services and the business valued at roughly US$21.6b by market cap.
"Accelerating demand for data center, AI, and 5G infrastructure is driving increased adoption of Tower's Silicon Photonics and Silicon Germanium solutions. Meaningful capacity expansions and customer onboarding are supporting strong revenue growth and a higher margin product mix over the next several years."
What happens to Tower Semiconductor’s margin story if a single key assumption about future AI-driven orders for its specialty processes breaks.
If that AI demand twist is what you worry about next, read the full narrative for Tower Semiconductor and see how Tower Semiconductor’s story shifts when assumptions start to crack.
Asia Vital Components (TWSE:3017)
Asia Vital Components sits right in the heat path of AI infrastructure, supplying the cooling hardware that lets dense GPU and accelerator racks run hard without melting performance or reliability. This is why its thermal gear keeps showing up in this screener.
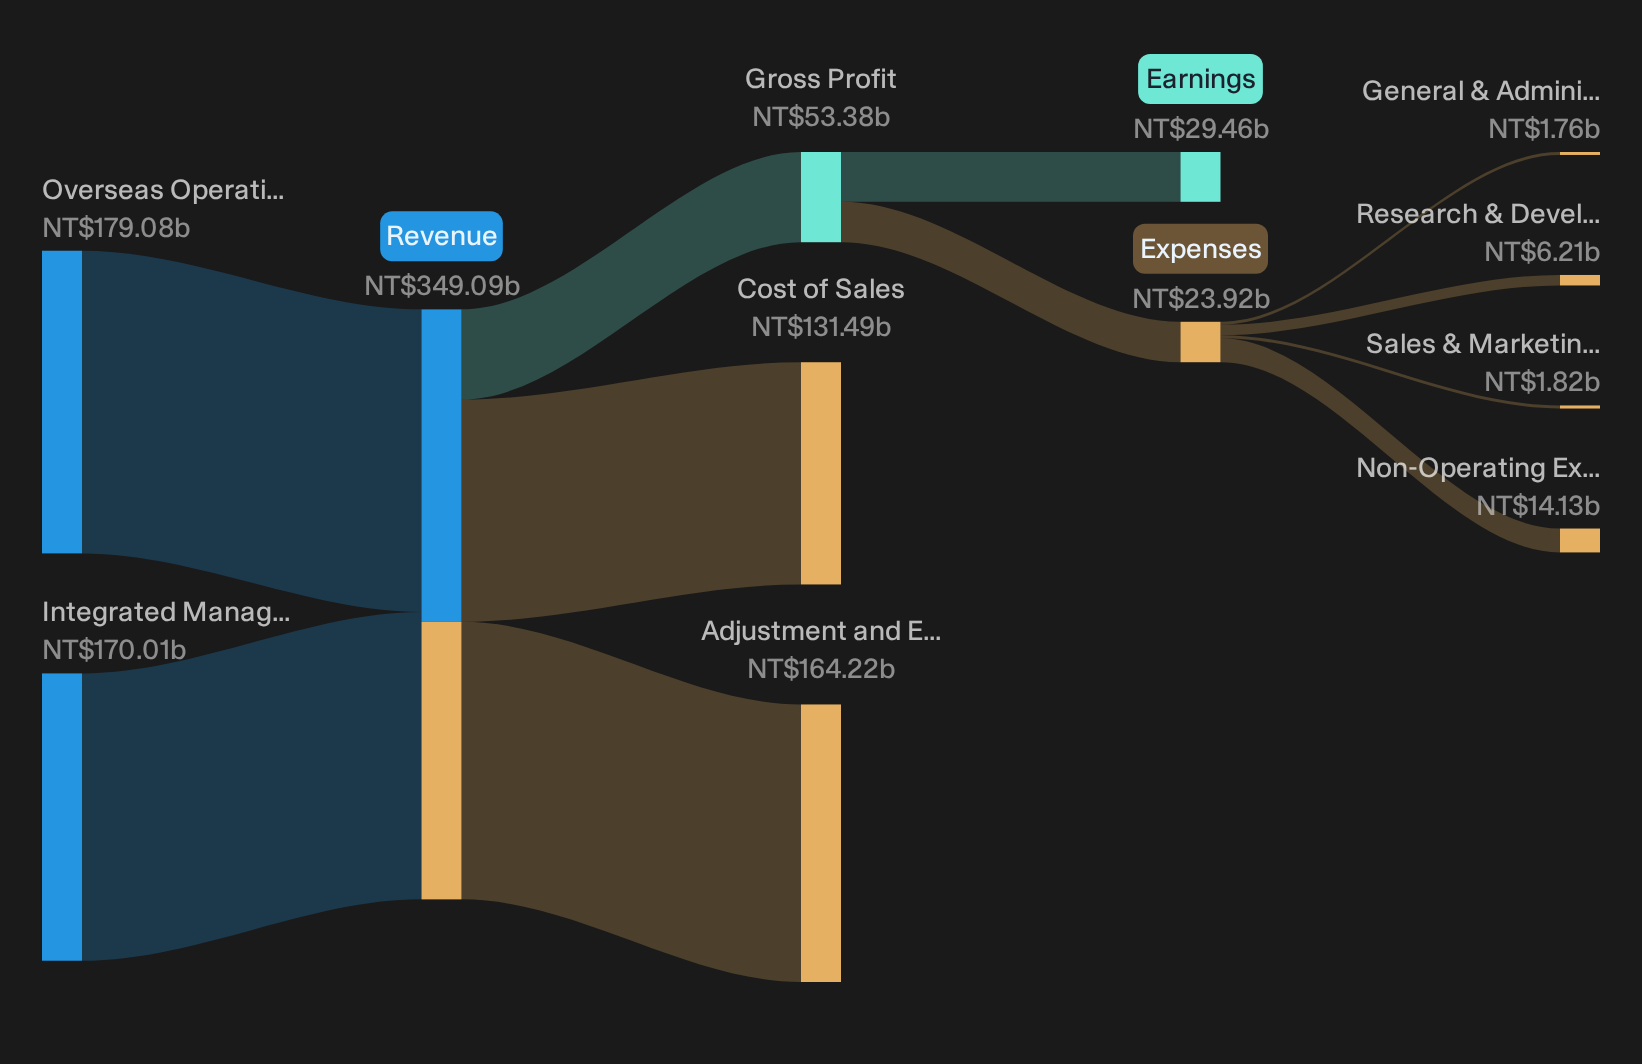
Asia Vital Components generates NT$179.1b from its Overseas Operating Department and NT$170.0b from its Integrated Management Division, after group adjustments of NT$164.2b, and is valued at about NT$1.2t by market cap.
For Asia Vital Components, Jensen Huang’s push for continued AI build out turns thermal management from a background detail into a potential chokepoint that its solutions are designed to address.
"Rising demand for high power computing and wider liquid cooling adoption in data centers is increasing server related product contribution, which could support revenue scale and help sustain higher gross margin."
What happens to Asia Vital Components’ earnings power if one unseen pressure in AI customers’ cooling choices shifts faster than expected?
If that cooling pivot is what you are watching, move straight to the full narrative for Asia Vital Components for how Asia Vital Components’ AI thesis could accelerate or stall.
Alchip Technologies (TWSE:3661)
Alchip Technologies is one of the pure-play AI infrastructure enablers in this list, designing custom accelerator and high performance compute chips that sit inside the servers powering large scale training and inference workloads.
Alchip Technologies generates about NT$23.1b in semiconductor revenue from its ASIC and SoC design services and production support, and the stock is valued at roughly NT$289.2b by market cap.
For investors trying to track where AI chip budgets flow after Nvidia, Alchip’s position as a custom ASIC partner for data center compute puts it close to the center of that capital spending story.
"Rapid expansion in advanced node and AI-related projects, along with strong design capabilities, is driving higher margins and positioning Alchip as a top industry player."
The real swing factor is what happens if one assumption about how quickly hyperscale customers scale their custom AI silicon needs to be rewritten.
If that assumption is what you are testing, go to the full narrative for Alchip Technologies to see how Alchip Technologies’ AI roadmap could reprice expectations.

Seeking Alternatives Before Momentum Flies
Fresh ideas get picked over quickly. The strongest stories can shift from under the radar to fully priced before the crowd catches on, so act now and get in early.
- Hunt for early-stage breakouts among resilient small caps by scanning 2 elite penny stocks with strong financials before momentum gets fully priced in and the easy entry points disappear.
- Secure exposure to AI without chasing headlines by reviewing 75 profitable AI stocks that aren't just burning cash that already generate real cash flow while sentiment is still catching up.
- Anchor your portfolio with durable income by checking 6 dividend fortresses that aim to keep yields flying while prices have not yet fully reacted.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com