
Workday (WDAY) Could Be 65% Below Fair Value On Buyback And Takeover Interest
Workday (WDAY) has been in focus after reports of takeover interest from private equity firm Silver Lake, a new US$4b share repurchase plan, and fresh attention on its upcoming analyst day.
Despite the takeover headlines, Workday’s recent price action has been mixed, with the share price down 4.03% over 30 days but up 56.51% on a 90-day basis, while the 1-year total shareholder return has declined 12.94%. This suggests short-term momentum has picked up even as longer-term holders remain under water.
Scan how Workday’s story compares with other software players under fresh buying interest by checking a curated set of 16 high quality undiscovered gems in the same space.
Workday now trades below both its average analyst target and one intrinsic value estimate, after a sharp rebound. Does that gap signal mispricing or a fair discount on the recent move?
Most Popular Narrative: 65% Undervalued
Against a last close of $190.67, the most widely followed narrative pegs Workday’s fair value far higher, which puts recent takeover talk and buyback plans in a different light.
The core thesis is simple: three independent data sources, contracted backlog, realized free cash flow, and forward guidance, all moved in the same direction this quarter. That kind of triangulated confirmation is harder to dismiss than any single metric on its own.
See why 13 investors see Workday as 65% undervalued.
Result: Fair Value of $550.10 (UNDERVALUED)
Still, the Workday narrative hinges on backlog and AI adoption holding up, so a slowdown in contracted revenue or a plateau in agent usage would cut directly against it.
Find out about the key risks to this Workday narrative.
Another View On Workday’s Valuation
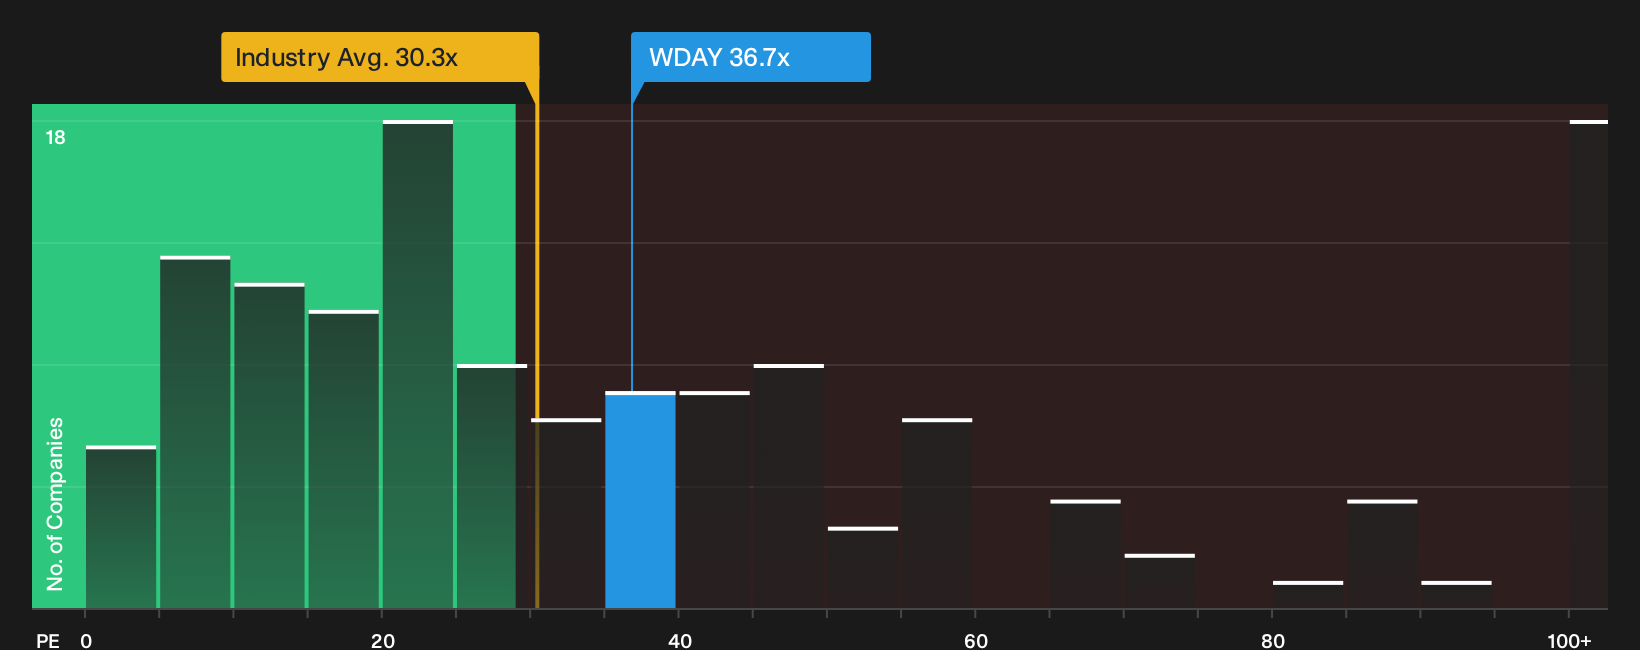
The first fair value story around Workday leans heavily on cash flows and discounted forecasts. A different lens uses the current P/E of 36.7x, which is richer than both the US Software industry on 30.3x and the peer group on 29.5x, yet only slightly below a fair ratio of 38.7x. This raises the question of whether that represents a margin of safety or a thin valuation cushion if sentiment turns.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about the tone of this Workday story, with takeover talk and valuation gaps pulling in different directions. Act quickly, review the underlying drivers yourself, then weigh them against the 3 key rewards.
Looking for more investment ideas beyond Workday?
You have already done the hard part by understanding Workday’s setup. Do not stop there when other potential opportunities are only a few clicks away.
- Target resilience first and scan a curated group of companies with lower risk profiles using the 11 resilient stocks with low risk scores.
- Hunt for value and compare Workday with a focused selection of potentially underpriced businesses through the 34 high quality undervalued stocks.
- Prioritize balance sheet strength and filter for businesses with stronger fundamentals using the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com