
SEALSQ (LAES) Stock Looks Overvalued After Its 46% YTD Fall
SEALSQ Corp has seen its stock fall sharply this year, even as the business pushes hard into post quantum chips and security infrastructure. That gap between share price and commercial progress puts a simple question in front of you, which is whether today's valuation is properly anchored in SEALSQ's sales.
- The share price is down 45.8% year to date, which puts the focus squarely on whether the current level already reflects what the company is generating in revenue.
- Recent updates around post quantum semiconductors, the expanding Quantum Highway network and quantum related partnerships can shape how quickly future sales might scale and how much investment is needed to get there.
- The analysts covering SEALSQ have run their own numbers. See what analysts think SEALSQ's shares could be worth.
The issue now is whether SEALSQ's current share price is justified by its sales when judged against the Fair Ratio benchmark.
To pressure test SEALSQ's post quantum story and valuation against others in the same broad theme, it can help to line it up beside 60 AI infrastructure stocks.
Has SEALSQ Run Too Far on Sales?
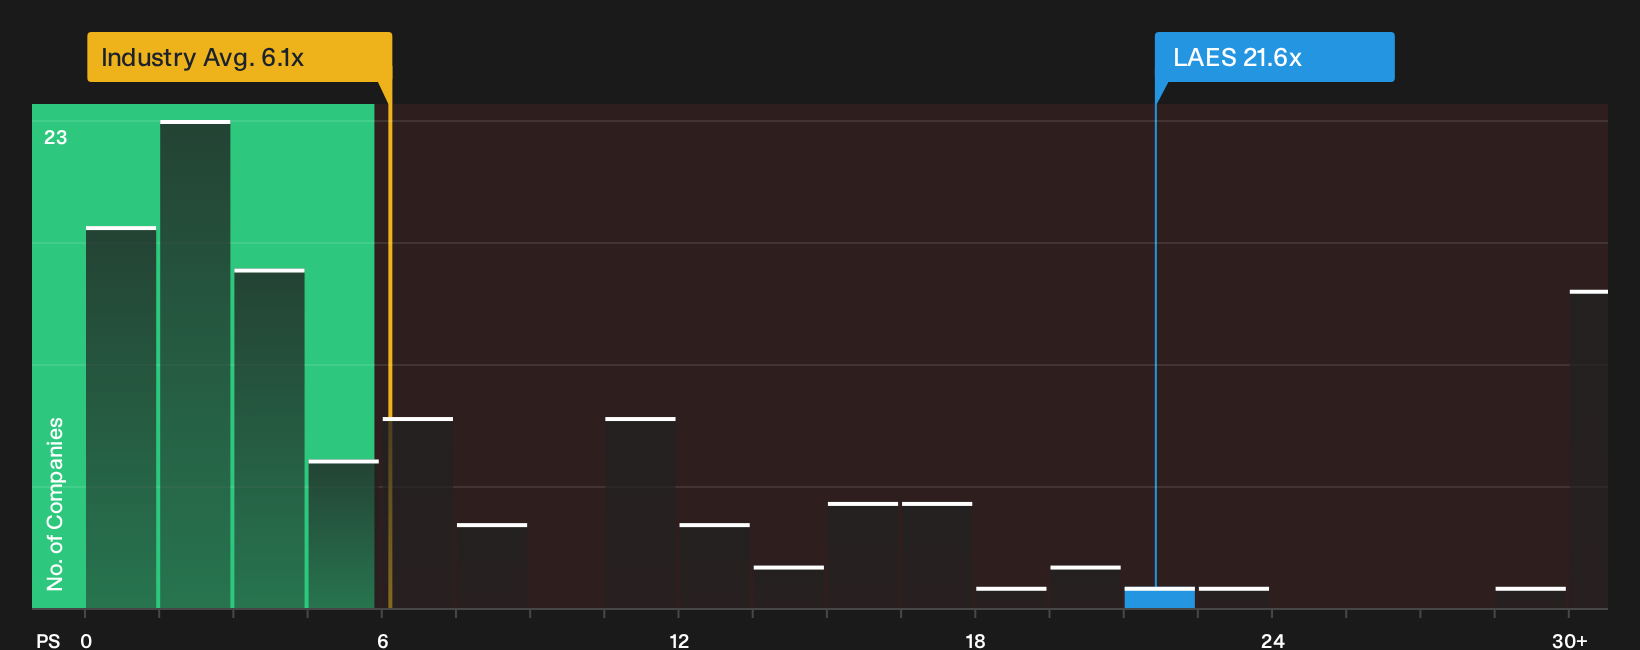
P/S is a useful lens for SEALSQ because the business is still focused on revenue traction while free cash flow and earnings are negative. The stock trades on a P/S ratio of 21.6x, compared with a Semiconductor industry average of 6.1x and a peer group around 5.5x. On a simple sales footing, investors are paying a much higher price for each dollar of SEALSQ revenue than is typical across the sector.
The Fair Ratio framework, which looks at the kind of P/S multiple you might expect given SEALSQ's growth profile, margins, size and risk, places the current valuation above that reference point. Because the model is heavily penalising current losses and the quality of cash generation, the gap is better read as a warning flag on how richly the shares are priced than as a precise indication of what they should trade on. Despite strong headlines around the Quantum Highway expansion and post quantum projects, the P/S multiple still leaves very little room for disappointment on future commercial execution. Explore the numbers behind SEALSQ's P/S valuation.
The SEALSQ Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for SEALSQ pick up where the valuation puzzle leaves off by spelling out the specific assumptions on future growth, margins and earnings that would need to hold for SEALSQ's share price to sit meaningfully above or below today's level. Instead of a single output from a ratio or model, Narratives lay out the path that number relies on, so you can watch how the real world either confirms or challenges it on the Community page.
One of the top community narratives on SEALSQ: 259% overvalued
"SEALSQ is positioning itself at the intersection of several powerful technology trends, cybersecurity, semiconductors and post-quantum cryptography…"
Discover why this Narrative puts SEALSQ at 259% overvalued.
One more angle on SEALSQ that could change the story
There is a separate piece of the SEALSQ picture that sits outside current multiples, which is how professional analysts map out the next few years and how that stacks up against today's pricing. Explore where analysts expect SEALSQ to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com