
Qualys Stock Outlook Gets A Lift From AI Security Demand
- Qualys recently raised its revenue outlook as enterprise AI adoption increases, highlighting growing demand for its TotalAI platform to secure AI deployments and prioritize remediation across development and production environments.
- The renewed focus on AI safety puts Qualys’ cloud-based security and compliance platform closer to critical decision points in corporate risk management, which can influence how customers allocate long term cybersecurity budgets.
- We will now explore how Qualys’ higher revenue outlook tied to its TotalAI offering could reshape the existing investment narrative around AI security.
Scan beyond Qualys to compare how other cybersecurity players are positioned for AI driven demand, using our curated 60 AI infrastructure stocks as a starting shortlist.
Qualys Investment Narrative Recap
To own Qualys, you need to believe the security platform can convert its AI focused tools and cloud apps into steady, higher value relationships even as competition tightens. The recent revenue outlook raise tied to TotalAI supports that thesis in the near term. The key short term catalyst is whether this AI security demand translates into stronger annual recurring revenue than the recent 10.3% pace.
The biggest near term risk is that usage based Flex pricing and QLU adoption lead customers to optimize spend more aggressively than Qualys expects, which could keep ARR growth muted despite a rich product set. Softer demand, described by that 10.3% ARR growth and a modest 8.9% revenue outlook, also keeps pressure on new business momentum.
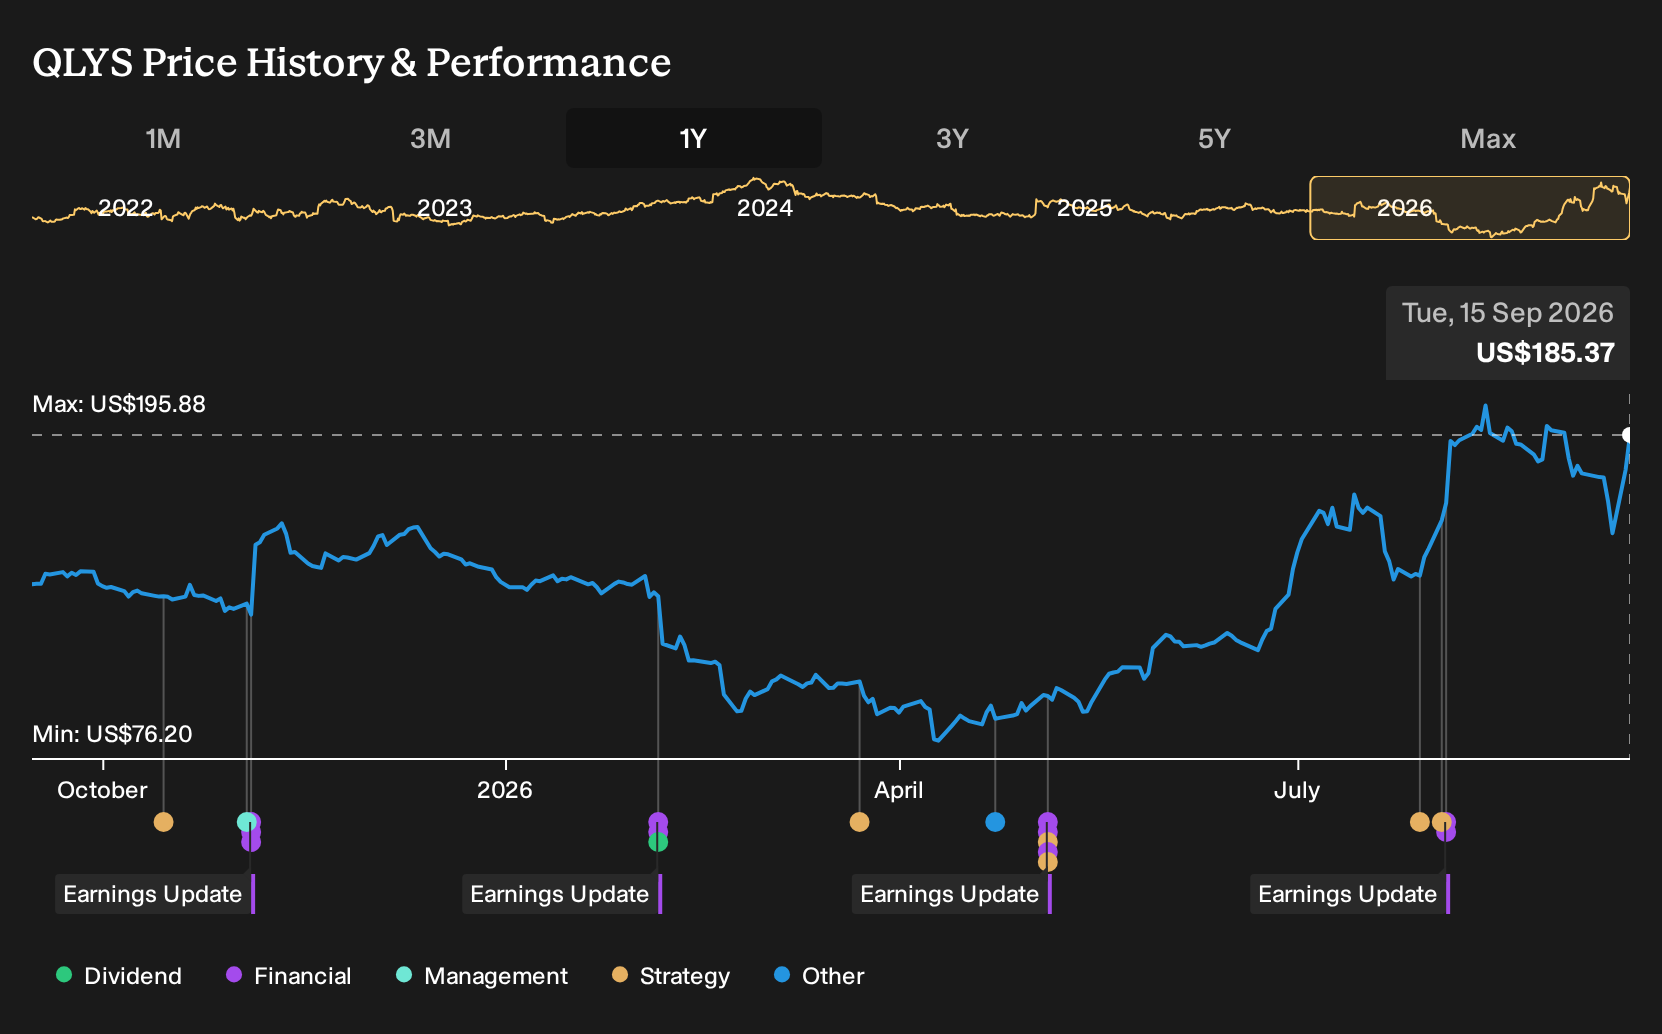
The raised revenue outlook connected to Qualys’ TotalAI platform is the announcement that matters most for this news. It ties the recent 83.7% six month share price move directly to the operational question that counts: whether AI security modules can lift growth from a relatively modest base and support its cloud native risk operations center push.
That same update also frames execution risk. Management is leaning on AI infused offerings to offset competitive pressure and customer tool consolidation, while still running a model that already carries high margins. If TotalAI and ROC adoption do not accelerate usage and upsell, then the current pricing structure and spending on go to market could compress returns over time.
Qualys' current analyst narrative points to US$870.3 million in revenue and US$225.2 million in earnings by 2029. This assumes revenue expands at 7.4% a year and earnings rise by about US$18.7 million from US$206.5 million today.
Uncover why Qualys' fair value indicates a 7% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternate view puts vendor consolidation at the center of the Qualys debate. The lowest analysts were already modelling revenue of about US$863.3 million and earnings of roughly US$202.3 million by 2029, with a much lower P/E of 22.1x. That is a sharply more cautious story. The new TotalAI driven update could shift those expectations, so consider both narratives carefully before you decide how to frame the risk.
Explore 2 other Qualys fair value estimates, including one that indicates as much as 7% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Qualys research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qualys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qualys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Qualys?
Once you have a handle on the Qualys story, it often pays to widen your watchlist with a few different angles across quality, value, and resilience. The Simply Wall St Screener can help you quickly surface stocks that match the type of opportunity you are looking for.
- For investors who want potential mispricing with strong fundamentals, start by scanning a focused set of 34 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and balance sheet strength sit at the top of your checklist, filter for companies in our list of solid balance sheet and fundamentals (22 results) to see which ones fit your risk profile.
- Income focused investors can zero in on cash returns by reviewing a curated 6 dividend fortresses that combine high yields with more robust business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com