
Levi (LEVI) Stock May Look Reasonable Despite Its 60% Run
Levi Strauss has seen its share price move around over the past few years, and that record now raises a simple question for you as an investor. Is the current valuation supported by what the business is earning today and is expected to earn in the future.
- Levi Strauss has delivered a 60.1% gain over the past 3 years, which puts real weight on whether the current earnings profile can carry that kind of share price journey.
- The group’s long history of turning brand strength into recurring cash flow means any change in profitability or cost efficiency can shift how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on Levi Strauss worth weighing. See what analysts think Levi Strauss's shares could be worth.
The issue now is whether the current share price around US$19.82 is justified by Levi Strauss' earnings power when judged against the Fair Ratio benchmark.
If you want to test the same earnings question you are asking of Levi Strauss across a wider set of companies, take a look at 34 high quality undervalued stocks
Does Levi Strauss Look Undervalued on Earnings?
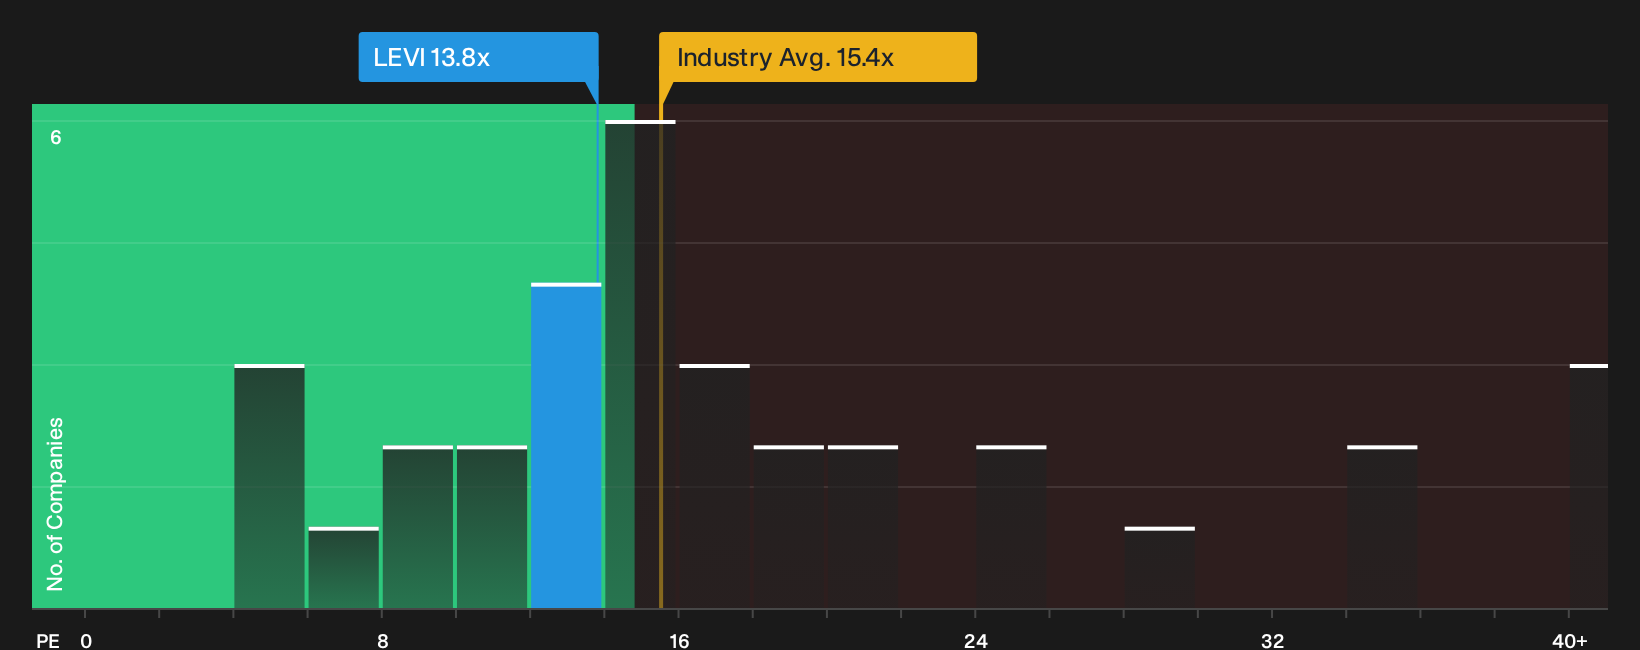
The P/E ratio fits Levi Strauss well because earnings are a key way investors judge a mature consumer brand. At a P/E of 14.0x, the stock trades below the Luxury industry average of about 15.4x and below peers at roughly 18.4x. That places Levi Strauss at a lower earnings multiple than many comparable consumer brands that investors use as reference points.
The Fair Ratio, which reflects what you might expect for Levi Strauss given its sector, size, profitability profile and risks, sits above the current P/E. That gap points to the shares screening as undervalued on this earnings lens, even after accounting for how similar companies are priced. The question for you is whether the current profit trajectory and brand strength justify the market eventually paying closer to that higher benchmark multiple for Levi Strauss. Explore the numbers behind Levi Strauss's P/E valuation.
The Levi Strauss Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question for Levi Strauss leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. Each scenario ties a fair value to a specific story about Levi Strauss' potential catalysts and key risks, so you can track over time which version of events appears to be taking shape on the Community page.
One of the top community narratives on Levi Strauss: 30% undervalued
"Levi's decisive shift to a Direct-to-Consumer-first business, now representing over half of sales, is delivering higher margins, greater control over brand experience…"
Discover why this Narrative puts Levi Strauss at 30% undervalued.
Before you move on Levi Strauss, there is one more angle to check
Valuation only tells part of the story, and Simply Wall St's broader checks on Levi Strauss have highlighted potential concerns that deserve space in your thinking before you act. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com