
ConocoPhillips (COP) Stock Appears Undervalued Despite Its Earnings Premium
ConocoPhillips has delivered a powerful share price run in recent years, which naturally raises a sharper question for you as an investor. Is the current US$141.22 price tag adequately grounded in the earnings the business is generating today and is expected to produce over time, or has sentiment pulled the stock away from what its profits can reasonably support?
- Over the past 5 years, ConocoPhillips has returned 184.2%, which puts real pressure on the question of whether its present earnings profile can carry that kind of step up in market value.
- The group’s results are heavily driven by its ability to convert upstream operations into consistent profits and cash, so any shift in production mix, costs or reinvestment needs can reshape what investors are effectively paying for each dollar of earnings.
- The analysts covering ConocoPhillips have run their own numbers. See what analysts think ConocoPhillips's shares could be worth.
The issue now is whether the stock’s current P/E and related earnings metrics leave today’s price for ConocoPhillips looking well supported by its profit stream or stretched against what the underlying business is delivering.
If you are weighing whether ConocoPhillips’ 184.2% five year return still lines up with its earnings power, it can help to compare it with other profitable operators using the 34 high quality undervalued stocks
Is ConocoPhillips Still Cheap on Earnings?
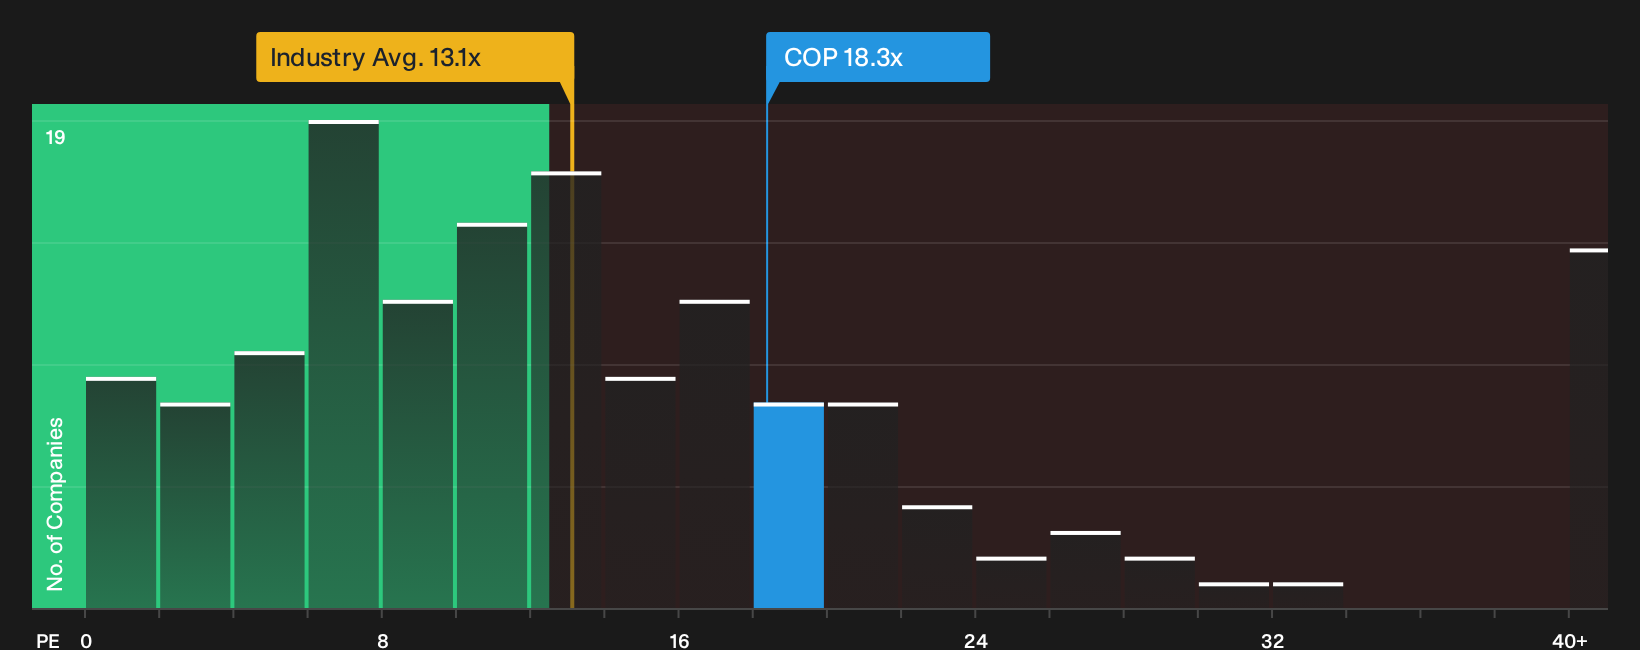
The P/E ratio is a useful way to check how much you are being asked to pay for each dollar of ConocoPhillips earnings today. On this lens, the stock trades at about 18.3x earnings, which is higher than the Oil and Gas industry average of roughly 13.1x but below the peer group level near 20.5x.
The Fair Ratio model, which adjusts for ConocoPhillips specific growth outlook, profitability profile and risk level, suggests the current 18.3x earnings multiple sits below where the business might trade if it were priced more fully. That points to the shares screening as undervalued against this tailored yardstick, even though the market is already assigning a richer P/E than the broader sector average. For a holder or potential buyer, the key judgment is whether the earnings quality and cash generation justify the gap to the sector and the discount to that more customised benchmark. Explore the numbers behind ConocoPhillips's P/E valuation.
The ConocoPhillips Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for ConocoPhillips leaves off, by spelling out the earnings, margin and growth assumptions that would need to hold for the stock to be worth meaningfully more or less than today’s price. Each storyline on the Community page links a fair value estimate to a specific mix of possible catalysts and risks, so you can track over time which version of ConocoPhillips' future appears to be unfolding.
Community views on ConocoPhillips are split between those who see more upside in its project pipeline and those who think expectations are already full.
Bull case: roughly fairly valued
"The company's expanding LNG portfolio and progress on large-scale liquefaction projects (notably in Qatar, Port Arthur, and Willow) are positioned to capture significant market share from robust global gas demand."
Discover why this Narrative puts ConocoPhillips at roughly fairly valued.
Bear case: 12% overvalued
"The plan to drive a $7b free cash flow inflection by 2029, including around $1b of incremental free cash flow per year from 2026 to 2028 and a further $4b from Willow, concentrates expectations on a narrow set of large projects."
Explore why this Narrative puts ConocoPhillips at 12% overvalued.
ConocoPhillips has one more piece of the puzzle you should check
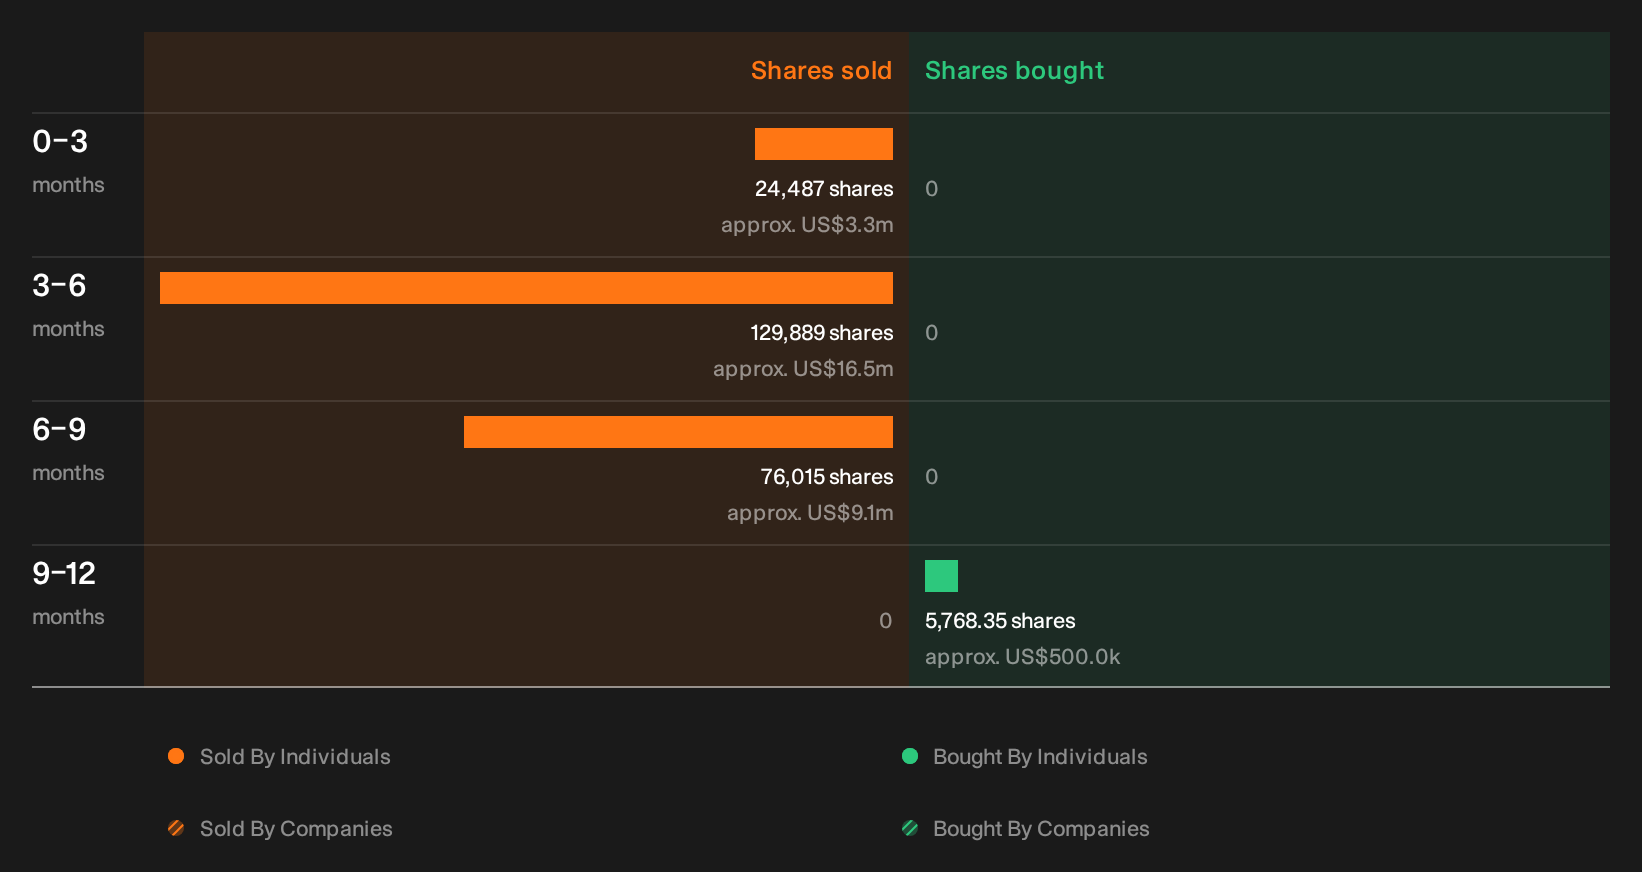
Price and earnings only tell part of the ConocoPhillips story, because recent dealing by people inside the business can signal something very different about conviction and risk. See the recent insider selling flagged for ConocoPhillips.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com