
International Business Machines (IBM) Following NASA AI News Has Its Valuation Back In Focus
International Business Machines (IBM) stock is drawing fresh attention after IBM and NASA released the open-source NASA-IBM Lunar Foundation Model, a scientific AI project that puts the company’s foundation-model ambitions in a new spotlight.
For context, the share price now sits at US$248.37, with a 7-day share price return of 7.01% and a 30-day share price return of 6.00%. However, the year-to-date share price return is down 14.80%, even as the 3-year total shareholder return of 85.93% and 5-year total shareholder return of 136.79% point to a far stronger longer run for International Business Machines than the recent pullback implies. The latest AI headlines, from the NASA-IBM Lunar Foundation Model to new agent governance tools, are arriving just as traders appear to be reassessing both the growth opportunity and the risks around IBM’s enterprise AI push.
Scan other AI infrastructure players moving on similar catalysts through our curated list of 60 AI infrastructure stocks.
International Business Machines just jumped on fresh AI headlines, yet the share price is still down meaningfully for 2026. Does that create a reasonable entry point today, or does it make more sense to remain patient on the sidelines as valuation comes into focus next?
Most Popular Narrative: 3% Undervalued
International Business Machines is trading at $248.37 against a widely followed fair value estimate of $256.08, which frames the current AI excitement as slightly discounted rather than overheated.
IBM represents a defensive growth technology investment transitioning into a software and AI-led enterprise platform company. While topline growth remains moderate, improving mix (software), strong margins, and durable cash flows underpin a compelling long-term investment case, particularly for investors seeking exposure to enterprise AI with lower volatility than pure-play SaaS peers.
See why 45 investors see International Business Machines as 3% undervalued.
Result: Fair Value of $256.08 (UNDERVALUED)
Still, the International Business Machines story can break if AI projects underdeliver on monetisation, or if heavyweight cloud rivals squeeze pricing power faster than expected.
Find out about the key risks to this International Business Machines narrative.
Another View: Multiples Send A Louder Signal On IBM
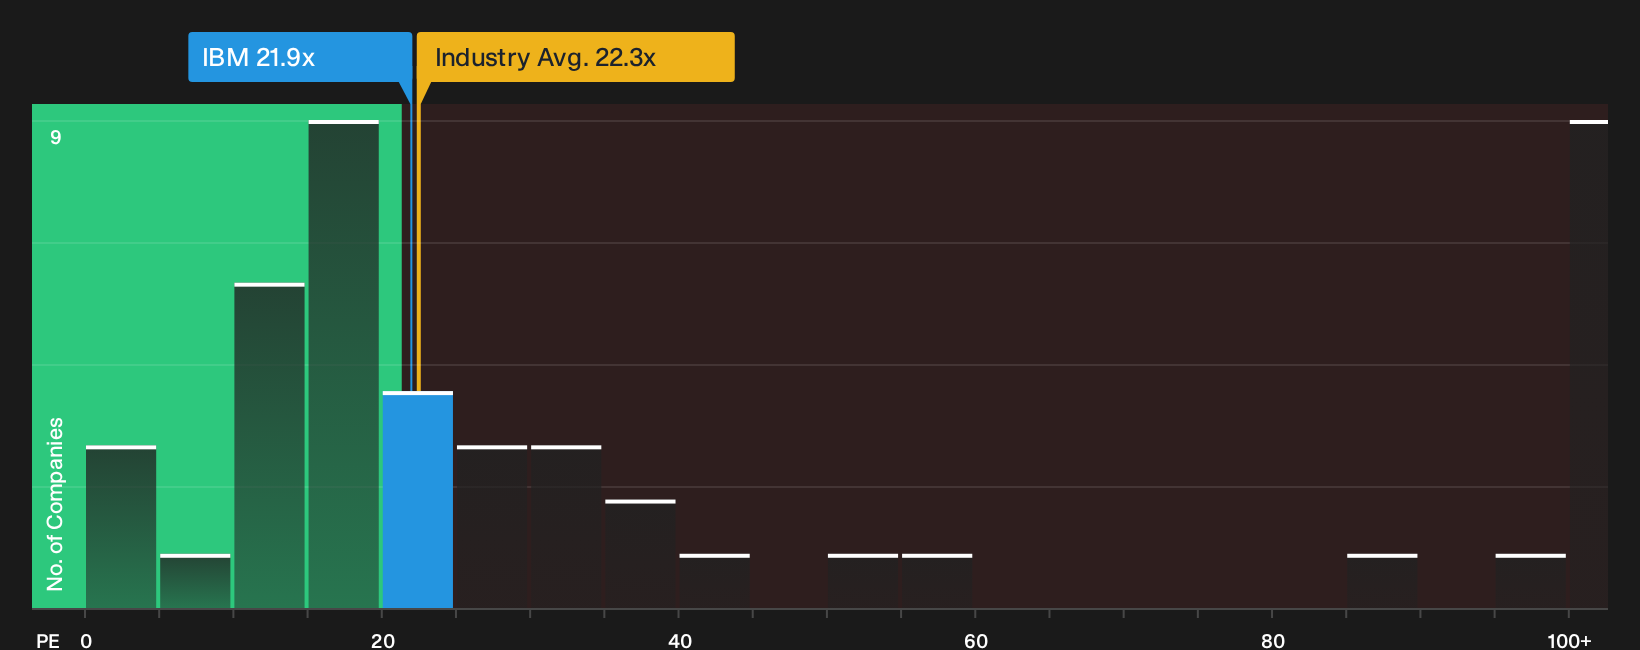
The earlier narrative leans on a fair value of $256.08 and a modest 3% gap, which makes International Business Machines look only slightly mispriced. The earnings multiple tells a sharper story. IBM trades on a P/E of 21.9x, above peer averages of 15x, yet below a fair ratio of 37.5x.
That mix of richer pricing than many direct peers, but a wide gap to the 37.5x fair ratio, frames current AI enthusiasm as a balance of valuation risk and potential upside rather than a clear bargain. It raises a simple question for investors: Which side of that gap do you think the market moves toward next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data or just a complex setup for International Business Machines right now? Consider acting while sentiment is still forming, and weigh both sides by checking the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond IBM?
Do not stop with International Business Machines alone. Use this moment to broaden your watchlist with other clear setups that match your risk tolerance and income goals.
- Target durable compounding potential by scanning a curated pool of companies that screen as mispriced on quality and value using the 34 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses designed to pay out robust yields through the 6 dividend fortresses.
- Protect your downside by zeroing in on firms with stronger finances and resilient balance sheets via the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com