
What’s Going On With Kraft Heinz (KHC)?
Index removal puts Kraft Heinz in the spotlight
Kraft Heinz (KHC) has been dropped from both the Nasdaq 100 and the Nasdaq Composite, a double index exit that pushes investors to reassess how they view this packaged food heavyweight.
The stock recently moved differently from the broader market and carries a Zacks Rank of #3, Hold, while trading at a discount to its industry. This may sharpen focus on valuation and earnings expectations.
Recent price action shows Kraft Heinz losing some momentum over the past month, with a 30-day share price return of down 3.06%. However, the 90-day share price return is up 6.59% and the 1-year total shareholder return is 1.90%, which hints that short term sentiment has softened while longer term performance has been more muted overall.
Scan how Kraft Heinz compares with other potential value ideas by reviewing a curated set of 34 high quality undervalued stocks before sentiment around these kinds of consumer staples shifts again.
Index removal and a share price near US$24.73 sit against analyst targets near US$25 and internal fair value estimates that imply a much wider gap. Which reference point deserves more weight now?
Most Popular Narrative: 29% Undervalued
Kraft Heinz is priced at $24.73 while the most followed narrative pegs fair value closer to $35, which frames the stock as a value story rather than a momentum ticker.
The opportunity is that the stock appears priced as though these problems are permanent while the business itself is showing signs of being merely repairable.
That is often enough. A stable dividend, strong free cash flow, improving share trends, continued productivity, and a renewed willingness to invest behind the brands can go a long way when nobody expects much in the first place.
See why 31 investors see Kraft Heinz as 29% undervalued.
Result: Fair Value of $35 (UNDERVALUED)
Still, Kraft Heinz depends heavily on North America and reported a loss of US$3.40b. Any pressure on pricing power or brand strength could quickly weaken this value angle.
Find out about the key risks to this Kraft Heinz narrative.
Another view on Kraft Heinz valuation
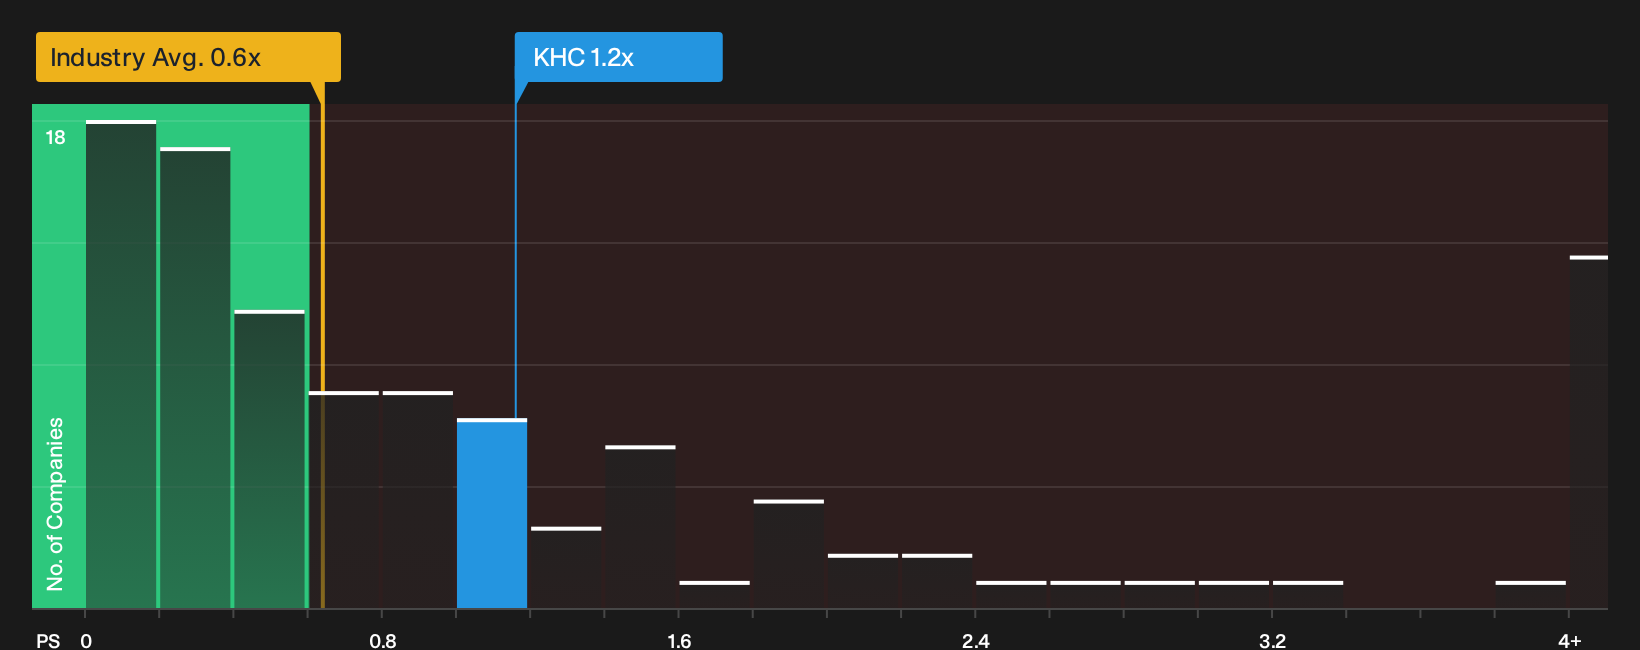
The first story around Kraft Heinz is that it trades well below an estimated fair value, which leans on future cash flow work. A second lens tells something different. On straight P/S, KHC sits at 1.2x versus 0.6x for the wider US Food group and 1.5x for peers, close to an internal fair ratio of 1.3x. That mix points to less of a simple bargain and more of a trade off between perceived quality and slower growth. Which version of value matters more for you right now?
For a closer look at how the market could re rate that P/S gap over time, and where mispricing risk might show up next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Kraft Heinz value and risk can be confusing, so review the underlying data now and shape your own stance using 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Kraft Heinz?
Do not stop with Kraft Heinz. Use this moment to refresh your watchlist with other opportunities that match your risk tolerance and income goals.
- Target dependable income streams by scanning a curated set of 6 dividend fortresses that prioritise yield and balance sheet strength.
- Spot potential bargains quickly by filtering through a focused group of 16 high quality undiscovered gems before the crowd catches on.
- Dial down portfolio volatility by zeroing in on a 11 resilient stocks with low risk scores built around resilient financial profiles and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com